Mortgage rates flat this week, but prepare for uncertainty
Processing Content
- Key Insight: Discover how conflicting Federal Reserve signals and sudden stock market anxiety are shifting bond yields.
- What’s at Stake: Mortgage originators face severe pressure as refinance and purchase activity hit a critical seasonal slowdown.
- Expert Quote: “A Fed pause doesn’t guarantee lower mortgage rates…” — David Busch, Trajan Wealth
Overview bullets generated by AI with editorial review.
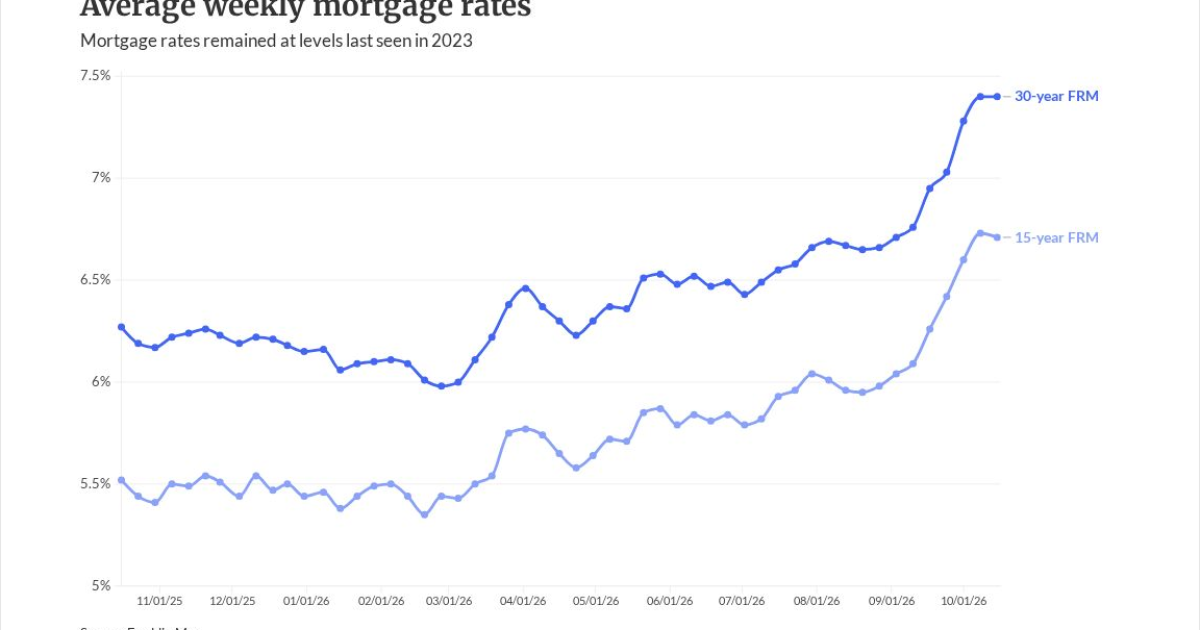
On a point-to-point basis, the 30-year fixed rate mortgage was unchanged from last week, Freddie Mac reported.
The Primary Mortgage Market Survey for the 30-year FRM
The 15-year FRM averaged 6.71%, down from last week when it was 6.73%. For
NerdWallet’s data had rates coming in slightly lower, but this didn’t tell the whole story.
What happened with mortgage rates this past week
“This week mortgage interest rates were pushed and pulled in opposite directions, and in the end it shook out with mortgage rates a little bit softer,” said Kate Wood, NerdWallet’s lending expert, in a Thursday morning comment. “But it wouldn’t take much for one side or the other to force a more decisive shift.”
Wood pointed to conflicting statements from Fed officials, two who commented a more restrictive policy is likely needed, as inflation data released Wednesday and Thursday came in hot.
Meanwhile, two different Fed officials said they don’t think much more tightening is needed to tame inflation.
“Additionally, anxiety over
This was the good news on Thursday morning as the 10-year yield, which closed at or above 5.2% since Sept. 28, and peaked at 5.33%
However, on Oct. 16, 2025, the 10-year closed over a full percentage point lower than the current yield at 3.98%,
Lender Price data on the National Mortgage News website had the 30-year FRM just below 7.7%. This compared with 7.824% one week ago.
The latest probability of an October FOMC increase
While the initial market bets after the CPI news was in support of a rate hike at the Federal Open Market Committee’s October meeting, as of Thursday morning, they were back to 73% supporting the probability of no action, according to CME FedWatch.
The CEO of the deVere Group, Nigel Green believes the Fed is likely to hold this month. But he is among those who expects a December increase.
But the markets are likely to remain turbulent in the short-term.
“Until markets have more certainty on that path, and on the election, every data release is likely to move prices far more than it normally would,” Green said in a commentary released Thursday morning which addressed AI and chip stocks. “I’d expect plenty more days like this, up and down, before the year is out.”
David Busch, CEO of Trajan Wealth, put out a reminder in his weekly comments that even if the Fed pauses, it is the investor community which determines the cost of long-term capital like mortgages.
“A Fed pause doesn’t guarantee lower mortgage rates or cheaper corporate financing,” Busch said. “Higher long-term yields are becoming the hurdle rate for American capitalism.”
How higher rates will affect origination activity
Mortgage origination volume will stay weak, given that the 30-year fixed in the past two week’s PMMS was at the highest since 2023, Bose George of Keefe, Bruyette & Woods said in a flash note commenting on the latest Mortgage Bankers Association Weekly Application Survey.
The elevated mortgage rates “should keep refinance activity depressed while purchase slows on both affordability and seasonality now that the selling season is over,” George said in the flash note. “This backdrop should continue to pressure mortgage originators, but we remain positive on select servicing-heavy names (Rocket/Rithm) where the risk-reward remains relatively compelling.”