Setting aside ₹2,000 per month in PPF can put your child on path to ‘crorepati’ status in long run. We calculate how
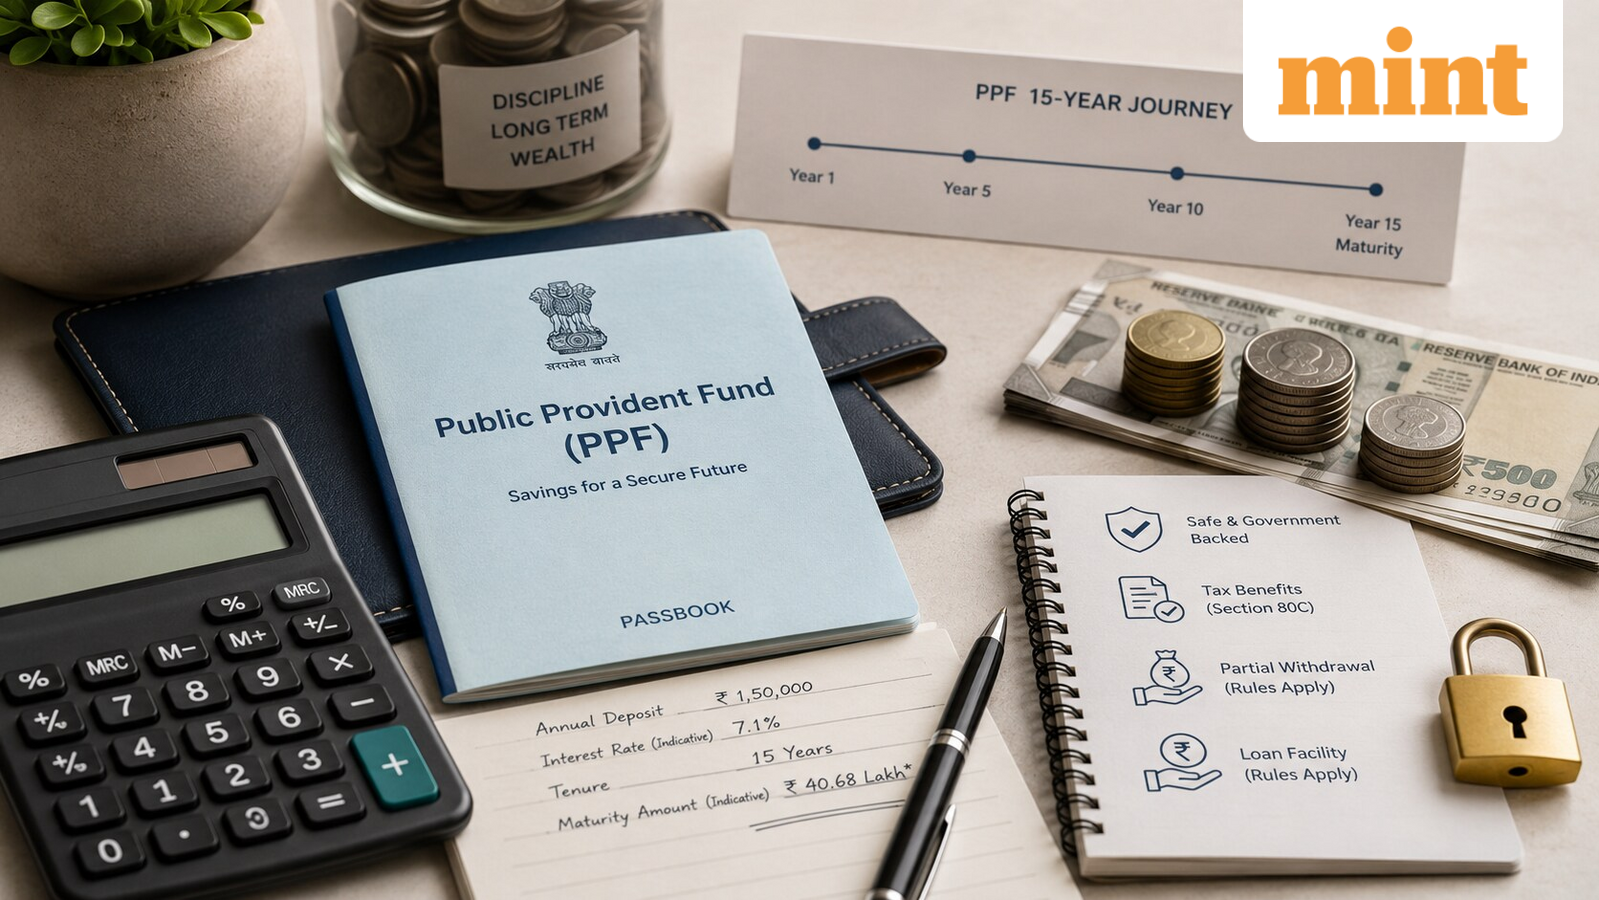
Parent looking to gift their child a secure future, can consider the public provident fund (PPF) — among the preferred options for guaranteed returns when it comes to long-term financial planning. The reliable, low-risk government backed savings scheme can be used to meet financial goals such as funding of wedding, children’s education abroad, buying a house, retirement fund or even building wealth.
A PPF account can be easily opened at any post office or bank branch across India by submitting an application form, photo and mandated KYC documents. For minors, the parent / legal guardian can open an account, which must be converted to major status once the primary account holder turns 18 years of age.
Today, we calculate how setting aside ₹2000 per month for your child can help secure their financial future. Here’s how you can use the government backed PPF facility to set them up for “crorepati” status in the long run.
Crorepati status possible? Invest at least 2,000/month
Notably, the age at which you begin investing at has a large impact on the total PPF corpus accumulated at time of withdrawal (usually between 50-60 years of age). When investing for your children, beginning early has dual advantage — it gives the corpus a longer time to accumulate interest, thus making maximum benefit of compounding interest; and it allows you to significantly reduce the minimum monthly investment required to reach your target.
For example, if you begin investment from the year your child is born, with long-term view of staying invested for the next 50 years, you and later they themselves can steadily invest a minimum ₹2,000 per month in the scheme. This works out to ₹24,000 per year.
If you start PPF investment in year of birth and your child continues the practice, ₹2,000/month deposited at interest rate of 7.1% (subject to change) totals investment of ₹12 lakh and earns interest of more than ₹96.12 lakh, for maturity payout of over ₹1.08 crore at age 50.
Power of compounding: Time is the costliest factor
Reaching the “crorepati” status could be achieved by gradually increasing your investment amount, time is the biggest factor when it comes to capturing the full benefit of compounding. While you begin with ₹2,000, as and when you or your child’s salary increases, the amount can be increased. Up to ₹1.5 lakh is tax-free investment in PPF under Section 80C.
Further, investing larger amounts monthly in PPF also may not be feasible or tax beneficial for most salaried individuals. PPF is offering interest rate of 7.1% at present, below is how the calculation works out for every 5-year delay:
- If you start their investment at age 15: Minimum ₹6,000 per month deposited for 35 years is investment of ₹25.20 lakh and earns interest of more than ₹83.74 lakh, for total maturity payout of over ₹1.08 crore at age 50.
- If you / your child starts investment at age 18: Minimum ₹7,500 per month deposited for 32 years is investment of ₹28.80 lakh and earns interest of more than ₹79.53 lakh, for total maturity payout of over ₹1.08 crore at age 50.
- If you / your child starts their investment at age 20: Minimum ₹8,800 per month deposited for 30 years is investment of ₹31.68 lakh and earns interest of more than ₹77.09 lakh, for total maturity payout of over ₹1.08 crore at age 50.
- If you / your child starts their investment at age 25: Minimum ₹13,100 per month (above tax benefit) deposited for 25 years is investment of ₹39.30 lakh and earns interest of more than ₹68.72 lakh, for total maturity payout of over ₹1.08 crore at age 50. To stay within tax benefit limit investment would have to be capped at ₹12,000 per month and would generate corpus of ₹98.95 lakh.
Please note that PPF tenure is for 15 years, post which you have choice to extend the account in blocks of five years, indefinitely, with or without additional deposits. The accumulated corpus continues to gain interest.
Disclaimer: This story is for educational purposes only. We advise investors to check with certified experts before making any investment decisions.