Home loan rates October 2026: Compare rates starting from 7% across 12 public sector banks
Are you looking for a home loan? Have you decided which lending institution you will take out your home loan with? Do you have a well-planned strategy not only to borrow but also to ensure you repay the home loan seamlessly?
These are some core questions that an aspiring home loan borrower must answer before proceeding with their home loan application, as proper planning is essential to ensure borrowing remains a pleasant experience.
Furthermore, home loan interest rates start from 7% at some prominent public sector banks in October 2026, although the rate applicable to a borrower can vary based on the lending institution, borrower profile, credit score, past borrowing history, loan amount and other fundamental factors.
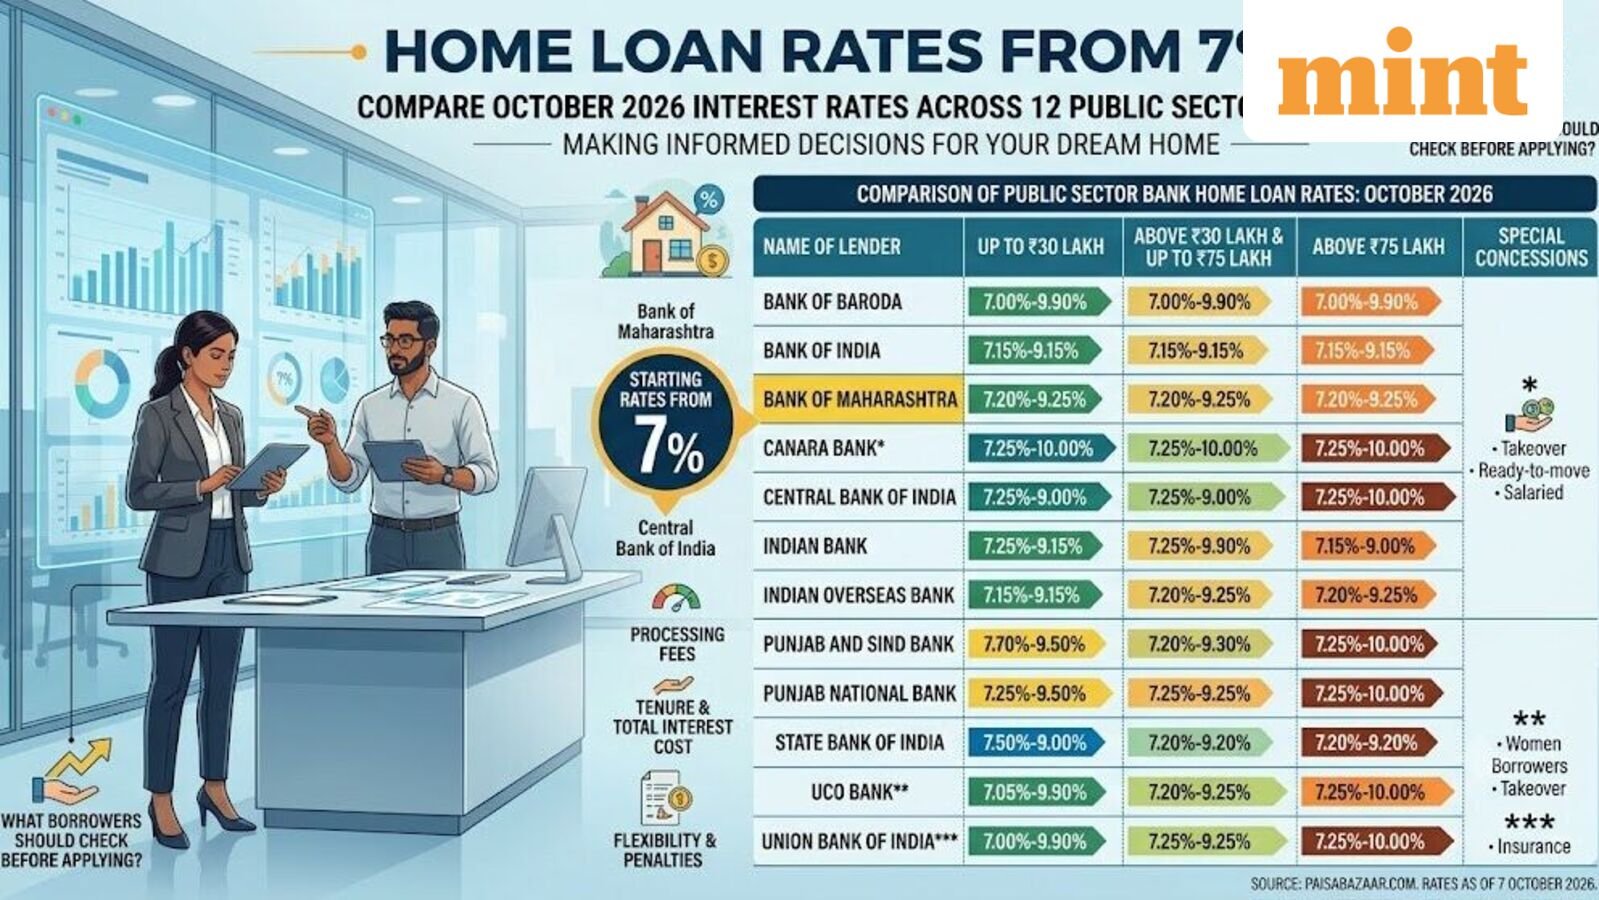
With this in mind, let us look at the home loan rates offered by prominent public sector banks in the country for October 2026. The rates provided below cover three loan slabs: up to ₹30 lakh, above ₹30 lakh and up to ₹75 lakh, and above ₹75 lakh.
It is also important to note that Bank of Maharashtra and Central Bank of India offer starting rates of 7% across all three loan slabs. Bank of Maharashtra’s rate ranges from 7% to 9.90%, while Central Bank of India’s rate ranges from 7% to 9.15%. The complete list of all banks is discussed in detail below.
Public sector bank home loan rates in October 2026
|
Name of lender |
Up to ₹30 lakh |
Above ₹30 lakh & up to ₹75 lakh |
Above ₹75 lakh |
|---|---|---|---|
| Bank of Baroda | 7.20%-9.00% | 7.20%-9.00% | 7.20%-9.25% |
| Bank of India | 7.10%-10.00% | 7.10%-10.00% | 7.10%-10.25% |
| Bank of Maharashtra | 7.00%-9.90% | 7.00%-9.90% | 7.00%-9.90% |
| Canara Bank* | 7.25%-10.00% | 7.25%-10.00% | 7.15%-9.90% |
| Central Bank of India | 7.00%-9.15% | 7.00%-9.15% | 7.00%-9.15% |
| Indian Bank | 7.15%-9.15% | 7.15%-9.15% | 7.15%-9.15% |
| Indian Overseas Bank | 7.20% onwards | 7.20% onwards | 7.20% onwards |
| Punjab and Sind Bank | 7.35%-10.75% | 7.35%-10.75% | 7.35%-10.75% |
| Punjab National Bank | 7.25%-9.25% | 7.25%-9.15% | 7.20%-9.15% |
| State Bank of India | 7.25%-8.55% | 7.25%-8.55% | 7.25%-8.55% |
| UCO Bank** | 7.15%-9.25% | 7.15%-9.25% | 7.15%-9.25% |
| Union Bank of India*** | 7.15%-9.60% | 7.15%-9.60% | 7.15%-9.60% |
Note: *Under CRG-Prime, CRG-1 and CRG-2, Canara Bank offers an additional 5 basis points concession for takeover/ready-to-move home loan proposals and for salaried employees maintaining a salary account with the bank.
**UCO Bank offers an additional 0.05% concession for women borrowers and 0.10% for takeover loans.
***Union Bank of India offers an additional 0.05% interest rate concession to borrowers opting for an insurance policy.
Source: Paisabazaar.com. Rates as of 7 October 2026.
What should borrowers check before applying for a home loan?
It is vital for aspiring home loan borrowers to carefully compare the rate applicable to their loan amount. Focusing only on the headline home loan rate might not provide the complete picture. The home loan must be evaluated holistically, taking into account the processing fee, tenure, overall interest costs, the flexibility offered by the lending institution, and any applicable fines or penalties if repayment does not go as planned.
The table above highlights that the starting rate can differ depending on the loan amount. For example, Canara Bank’s rates start at 7.25% for loans up to ₹30 lakh, 7.20% for loans above ₹30 lakh and up to ₹75 lakh, and 7.15% for loans above ₹75 lakh.
On similar lines, Punjab National Bank’s starting rate falls from 7.25% in the lowest slab to 7.20% in the two higher slabs.
Still, do note that the lowest rate depicted in a lending institution’s range does not simply mean that every borrower will receive the same rate. This is because the final interest rate depends on the borrower’s creditworthiness, credit profile, current credit score, income, employment, total loan amount and a host of other factors.
Therefore, to ensure that a meaningful and beneficial home loan is secured, borrowers should be vigilant and compare rates, applicable fees, processing charges, and other factors relevant to their specific loan amount.
Even a minor difference in the interest rate can impact the total interest payable over the repayment period. Furthermore, if you have any hesitation or doubts, it is wise to seek professional advice from a certified financial advisor to secure the best possible home loan that meets your current financial requirements and future economic needs.
Disclaimer: The interest rates mentioned above are based on data from Paisabazaar.com and are current as of 7 October 2026. Actual rates may vary depending on the borrower profile, loan amount, property and lender-specific terms and conditions. Borrowers should verify the latest applicable rate and charges with the respective lender before taking a home loan.