New data flips the script on winning rollover business
Processing Content
- Key insight: New research challenges the idea that rollovers are mainly a retirement-age event. Advisors who couple technology with a strategy of building early relationships with retirement savers are better positioned to win them as wealth management clients.
- Supporting data: Nearly half — 44% — of retirement plan rollovers happen before savers turn 59½, according to InvestorCOM.
- Expert quote: “If you’re meeting an employee at the moment of termination or distribution from an employer, you’re too late — like, sorry, you haven’t earned that business.” — Brian Brashaw, VP of employer plan solutions, Merit Financial Advisors
Tapping into the opportunity to add new clients through retirement-plan rollovers requires a mix of the right technology and service providers, according to six experts.
But financial advisors must first understand how 401(k) accounts and
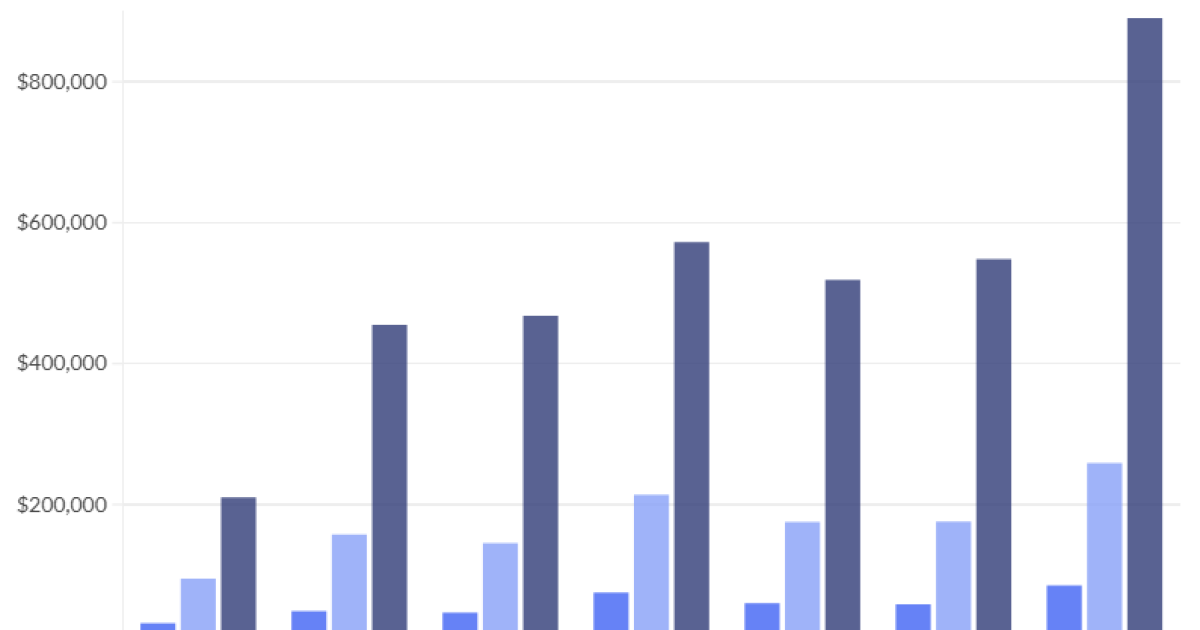
At age 59½, most savers can take penalty-free distributions from their 401(k) or other workplace plans, as well as traditional or Roth individual retirement accounts. However, InvestorCOM’s data shows many rollovers occur before savers reach that age. According to the firm’s analysis of
So the many statistics that reflect the business potential of employer retirement plans in general and, specifically, the estimated $1 trillion in rollovers every year may fail to capture what it actually takes to break into those areas of wealth management. The firms that are most successful have recognized that support for plan participants usually needs to begin “long before they become a client,” said Brian Brashaw, the vice president of employer plan solutions with Merit Financial Advisors, an Atlanta-based registered investment advisory firm aggregator with more than $32 billion in client assets. Simply talking about concepts like a “bridge” to new client relationships or the “convergence” of services or technology won’t suffice.
“Convergence is a byproduct of a larger strategy across the firm to dedicate the firm to supporting advisors on all spots of the investment spectrum — the life cycle of the investment dollar begins at student loan debt for a lot of us, right? Then buying a house, then getting out of that debt, then finally saving, going into the workplace. So that entire life cycle goes basically from degree to death,” Brashaw said. “If you’re meeting an employee at the moment of termination or distribution from an employer, you’re too late — like, sorry, you haven’t earned that business, and if one of the recordkeepers comes in and captures that rollover, like, yeah, that’s because they’ve been the face of their biggest asset in the 401(k) for a really long time.”
At the same time, the theme of convergence speaks to the way that rules from the Labor Department, the Securities and Exchange Commission and the IRS — as well as laws like the two Secure Acts — come into play with those possible new lines of business and vendors that can help advisors open them, according to Bonnie Treichel, the founder and chief solutions officer of retirement regulation consulting firm Endeavor Retirement.
While those requirements differ in the degree to which they impose a fiduciary duty on advisors to put clients’ best interest first, the standards governing advice seem to be converging, evolving into “almost becoming one and the same, with some slight nuances,” she noted. That trend is important because retirement savers need quality advice and recommendations before making consequential rollover decisions.
“It is this coming together of all forces,” Treichel said. “If asked, does a client demand this? Well, a client certainly doesn’t demand the concept of ‘convergence.’ That’s an industry term that we come up with, right? But I think, at the same time, a client does demand convergence. They just don’t realize that’s what they’re demanding, so to speak.”

InvestorCOM
$1T in assets annually in play, amid friction and competition for them
Those demands carry big stakes for any advisor, and they follow some patterns that indicate the “money in motion is far more predictable than the industry has traditionally assumed,” InvestorCOM’s report on the 50,000 transactions said. For instance, the most common types of employers whose plan participants completed those transactions were: healthcare providers (17%); telecom and media (13%); banking, insurance or professional services (12%); automotive and industrial manufacturing (11%); aerospace and defense (9%); technology (8%); and retail and consumer goods (8%). So advisors with a client niche in those fields could find outsize gains to their business from rollovers.
The average rollover value topped $300,000, with 58% above $100,000. While the value “rises sharply with age,” it also jumped substantially among the savers in their 40s and 50s and prior to age 59½, which is “well ahead of traditional retirement age” and challenges “the view that rollovers are primarily a retirement-age event,” the report said. And new business from rollovers isn’t emerging out of some coincidence for the advisors winning it.
“The differentiator isn’t luck: advisors who pair technology with a deliberate strategy capture a disproportionate share of rollover activity, often by building the relationship before the money is even in motion,” the report said. “Rollovers aren’t confined to a single moment near retirement. They’re a continuous, identifiable opportunity that spans age, account size, employer, and industry — and the advisors who combine the right data with a proactive strategy are the ones positioned to capture it.”
To that point, removing technological and bureaucratic layers that may inhibit savers from carrying out rollovers boosts advisors’ ability to win those accounts, said Anuraag Tripathi, CEO of retirement software firm Manifest. His firm, which collaborates with InvestorCOM, has developed tools that reduce the time it takes to do a rollover to “less than 10 minutes of effort,” which, in turn, then “leads to better retirement outcomes,” for the clients, Tripathi said. Advisors can use technology to ease the process.
“Most folks want one account,” Tripathi said. “They want consolidation and help managing those accounts, whether that’s in the workplace through a defined-contribution plan or whether that’s in an IRA. And the common factor that we found for people not taking that decision or that leap to roll over is friction.”
Advisors will encounter competition for those rollovers, given that the share of retirement plan administrators and aggregators who offer wealth management services has expanded to the point that “adoption is now the norm, not the exception,” according to webinar slides presented by Joshua Deitch, the head of U.S. insights at NMG Consulting.
The profitability of so-called specialist firms that derive at least 60% of their revenue from retirement plans is falling relative to more diversified advisory practices that get their business across retirement, full-bore planning, insurance and other aspects of wealth management, he noted. In other words, advisors who work with retirement plans among medium or smaller employers will soon face more competition, if they don’t already.
“If you think about the specialists, they tend to focus on larger plans, and one of the things that we’ve noted over the years is that the fees for those plans have been going nowhere but down,” Deitch said. “In addition, many plans have moved away from basis point fee structures to fixed fees. So, if you’re a specialist, your profit is really just a function of your scale, but your margins are continually shrinking.”
Build it, buy it or outsource it?
Advisors who could soon be vying for that business must resolve “a common problem across the industry,” according to Parham Nasseri, the president of InvestorCOM and moderator of the webinar.
“There are assets in the 401k, and they’re distinct and separate and siloed from the rest of your nest egg, and it’s a common denominator,” he said. “To be able to consolidate all that, the value of financial advice goes up tenfold, in my opinion.”
In order to do so, registered investment advisory firms and other advisory practices must do more than just figure out how to recommend rollovers, noted Tom Reeve, a product lead with InvestorCOM. They also need recordkeeping services, compliance oversight and a technology provider that “allows you to be agile” amid the industry’s shifting regulations and software integrations, he said.
Advisors and firms that “move quickly and make decisions about building out a technology platform to address this strategy can actually scale really quickly, whether it’s rollover dollars or really just integrating the retirement assets into their holistic advice platform,” Reeve said. “Buying or working with a vendor is usually the faster path, and, so, to meet that urgency, they want someone a seasoned provider who can get them up to speed quickly.”
Regardless of whether advisors try to win rollover business at the convergence of retirement plans and wealth management, they could help many people and grow their business in the process.
“It touches on so many of the value propositions of a true financial advisor,” Nasseri said. “The advisor can now do much more in that relationship that they have with their end investor.”