Titan Company shares fall 4% after Q2 business update. What is Nomura saying?
Titan added 78 net stores during the quarter, taking the total store count across its consumer businesses to 3,758 as of September 2026. Domestic businesses grew 22% year-on-year, while the international business grew 97%, according to the exchange filing.
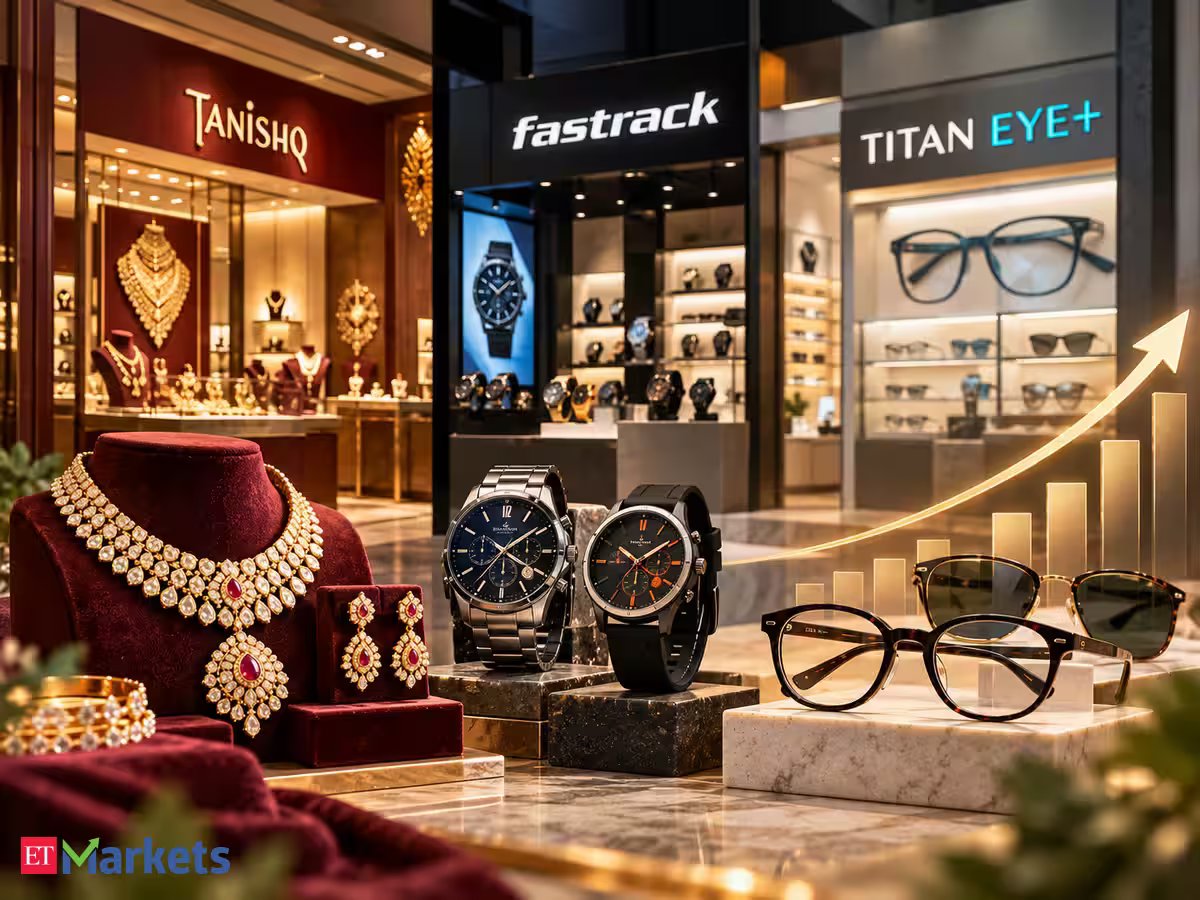
Titan’s jewellery business grew around 21% year-on-year in Q2FY27. Consumer demand remained healthy through most of the quarter, although it moderated towards the end as the festive calendar shifted to the third quarter of FY27.
Studded jewellery grew in the early thirties, helped by the ‘Festival of Diamonds’ campaign and brand-level promotions, while plain gold jewellery increased around 20% year-on-year. Investment-driven demand for coins declined from a high base, leading to a high single-digit year-on-year fall.
At the overall portfolio level, jewellery buyer growth was in the mid-single digits, while average ticket sizes increased in double digits. Tanishq, Mia, Zoya and beYon together recorded 20% growth, while CaratLane grew 32%. The jewellery business added 42 net stores during the quarter, taking its total store count to 1,269.

The watches business grew around 30% year-on-year, continuing to benefit from premiumisation. Analogue watches grew in the early thirties, while the smartwatch business recovered with high single-digit growth. The division added 34 net stores, taking its store count to 1,379 as of September 2026.
EyeCare reported 28% year-on-year growth in Q2FY27, supported by execution across key strategic priorities. Titan said its multi-brand strategy, continued upgrades to its existing store network and a sharper merchandise portfolio were enhancing the overall customer experience. The division had 847 stores as of September 2026.The company’s international business grew 97% year-on-year in Q2FY27. Jewellery businesses Tanishq, Mia and CaratLane continued to see strong double-digit momentum in North America. The GCC business remained resilient amid a volatile geopolitical environment, with Tanishq reporting improving growth, while Damas showed early signs of recovery, the company said. The international business added one net store during the quarter, taking its total store count to 164 as of September 2026.
Buy, sell or hold Titan shares?
Nomura has retained its Buy rating on Titan with a target price of Rs 5,425. The brokerage noted that Titan is currently trading at 53x Mar-28F EPS of Rs 86.1.
Nomura expects Titan to face a high base in jewellery sales growth, with the company cycling growth of 40% in Q3, 45% in Q4 and 38% in Q1. The brokerage also expects the benefit from elevated gold prices to moderate if prices remain at current levels, which could result in an optical moderation in revenue growth on a quarter-on-quarter basis from Q3 onwards.
Despite these near-term factors, Nomura expects Titan to deliver strong consolidated FY27F sales and EBIT growth of 19% and 23%, respectively. It also maintained its forecast for consolidated jewellery sales and EBIT CAGR of 19% and 18% over FY26-30E, indicating continued visibility on strong growth.
The brokerage said any optical moderation in sales growth due to the high base, and a resulting correction in the stock price, could provide an opportunity for investors to accumulate Titan shares. Nomura continues to include Titan among its top sector picks and forecasts an EPS CAGR of 22% over FY26-29F. It values the company at 60x Jun-28F EPS, with all estimates unchanged. The key risk to the view is a slowdown in sales growth due to high gold prices and competition.
Disclaimer: This article has been written by Veer Sharma, who is not a SEBI-registered Research Analyst or an Investment Adviser. Veer Sharma and his ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.