Rivian vs. Lucid: Only 1 of These EV Stocks Survives to 2030. Here’s Which One.
Wall Street has become less optimistic about the future of electric vehicles (EVs) since they boomed in 2020. Two stocks that went public during the EV boom and are subsequently down more than 90% from their highs are Rivian Automotive (RIVN -3.12%) and Lucid Group (LCID -1.43%).
Both stocks have tried to build premium EV businesses to compete with Tesla, but have struggled to turn a profit. However, based on their respective balance sheets, I think only one will survive to 2030. Here’s why, and whether the EV stock belongs in your portfolio today.

Today’s Change
(-3.12%) $-0.46
Current Price
$14.30
Key Data Points
Market Cap
Day’s Range
$13.96 – $15.36
52wk Range
$12.39 – $22.69
Volume
60.9M
Avg Vol
27.8M
Gross Margin
2.06%
Shaky growth, new product releases
Lucid Group introduced an ultra-premium EV sedan, the Lucid Air, priced from $100,000 to $250,000, in 2021. It followed up the sedan with the Gravity SUV in 2024, which is also in the premium price range. Growth has been mixed but has been up in recent quarters, with deliveries up 19% year over year to just under 4,000 in the second quarter of 2026.
On the other hand, Rivian is aiming for more rugged premium vehicles, as seen with its Rivian R1T and R1S trucks and SUVs. These are still expensive vehicles, but not as expensive as a Lucid, with deliveries at 12,000 last quarter. While deliveries are down from their peak, they have recently been climbing and could expand significantly with the launch of the cheaper R2 SUV, projected to have over 20,000 deliveries by the end of 2026.
Lucid has a cheaper vehicle, the Cosmos, slated to launch in 2027, which will hopefully compete with the Tesla Model Y, the world’s most popular EV. However, the roll-out of the Cosmos has frequently been delayed, which should temper investor expectations for delivery growth in a business that is already subscale.
Image source: Getty Images.
Margin and financing differences
A big issue with these EV start-ups has been cash burn and profit margins. In the automotive business, there are many upfront manufacturing costs. Until manufacturing reaches scale, most of these businesses have weak or negative gross margins.
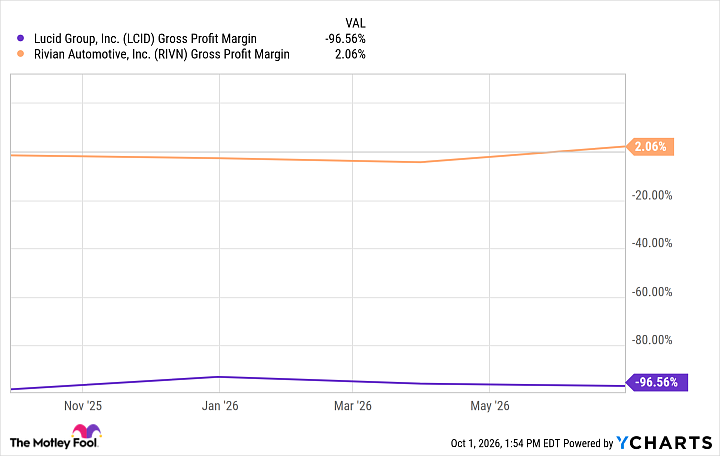
Lucid is feeling the pinch from both sides. Its gross margin is close to negative 100 %, meaning it is losing a dollar on every dollar of revenue before accounting for overhead costs. Free cash flow was negative $5 billion over the last 12 months, despite Lucid generating just $1.5 billion in revenue.
Rivian does not have sparkling-clean financial statements, but it is in a better spot than Lucid, with a positive 2% gross margin and negative $3.5 billion in free cash flow on $5.83 billion in revenue. If the R2 starts scaling up deliveries, you can envision Rivian achieving positive free cash flow, as long as gross margins continue to improve.
Financing sources are a mixed bag. Lucid has a partner in the Saudi Arabian government’s investment fund, but it runs with little cash on its balance sheet today and will need to keep raising funds. Rivian has more cash as of this writing and a partnership with Volkswagen to keep infusing it with capital.
LCID Gross Profit Margin data by YCharts
Why Rivian can survive to 2030
For anyone reading this far, you can guess why Rivian is my choice as the EV player that survives to 2030. It has deeper financing partners, better unit economics, and a clearer path to scale than Lucid. This does not mean Lucid is going bankrupt, but it is a possibility for the business with shares down 99% from their highs.
I also want to reaffirm that Rivian is not a slam-dunk buy just because it has a path to survival until 2030. There needs to be evidence of sustainable margin expansion, positive free cash flow, and consistent delivery growth for Rivian to justify its current $21 billion market cap. I think there is easier money to be made in the stock market today.