Are you building a house or commercial property? Know when TDS applies to contractor payments under Income Tax Act 2025
If you have hired a contractor to repair, renovate, design, or build your house, office, or business premises, you need to know whether TDS applies before making the payment.
For payments made on or after 1 April 2026, TDS on contractor payments is governed by Section 393(1) of the Income-tax Act, 2025.
So, when do you need to deduct TDS on payments to a contractor, what rate applies, and when is TDS not required? Here’s what you need to know.
Who must deduct TDS on construction payments?
The person making the payment to the contractor is responsible for deducting TDS.
For payments covered under Section 393(1), Table Sl. No. 6(i), the payer must be a “designated person” covered by the law. This includes specified entities such as companies, firms, government bodies, local authorities and other persons covered by the provision.
For payments to a resident contractor for carrying out work under a contract:
- 1% TDS applies when the contractor is an individual or HUF.
- 2% TDS applies when the contractor is any other person or entity.
TDS must be deducted either when the contractor’s payment is recorded in the payer’s books or when the payment is actually made, whichever happens first.
An individual or Hindu Undivided Family (HUF) making payments covered under Section 393(1), Table Sl. No. 6(ii), is also required to deduct TDS if the amount or aggregate of such payments during the tax year exceeds ₹50 lakh. The TDS rate in this case is 2%. This provision can apply to payments made for personal as well as commercial purposes.
Who is the contractor?
A contractor, for these purposes, is a resident person or entity receiving payment for carrying out work under a contract, including supplying labour for carrying out that work.
For construction-related payments, this can include payments made to a contractor engaged to carry out work on a project under an agreed contract.
When does TDS apply?
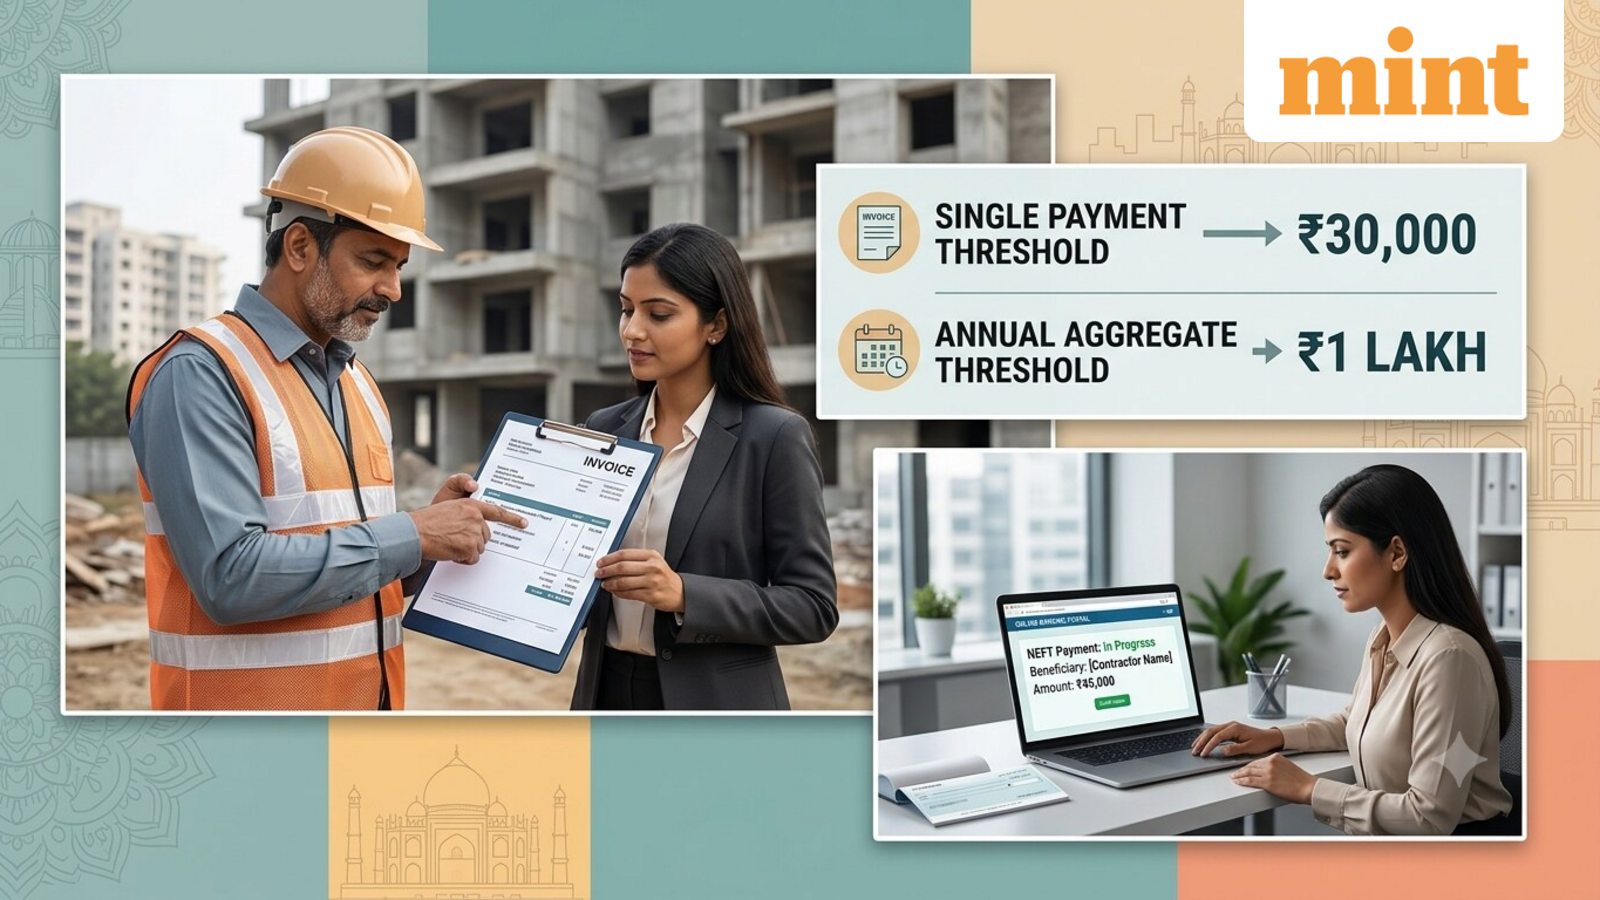
TDS is not required on a single payment of ₹30,000 or less under the contractor provision for designated persons. However, if the aggregate payments to the contractor during the tax year exceed ₹1 lakh, the TDS requirement is triggered.
For example, if a company pays a construction contractor ₹25,000 in one payment, no TDS is required on that payment by itself. But if the aggregate payments to the same contractor during the tax year exceed ₹1 lakh, TDS becomes applicable under the applicable provision.
However, if an individual pays a contractor ₹45 lakh during the year for constructing a house, no TDS is required under this provision. If the total payments exceed ₹50 lakh, TDS at 2% applies.
In simple terms, the payer deducts the applicable TDS from the contractor’s payment and deposits it with the government. The contractor receives the balance amount after TDS and can claim credit while filing the ITR.
Disclaimer: This is only for informational and educational purposes. Please consult a qualified expert for the latest laws and regulations.