Mortgage lending growth expected in 2026 despite rate uncertainty, says EY
Mortgage lending growth in the UK is expected to rise from 3% in 2025 to 3.3% this year due to lower rates in the second half of last year, analysis found.
The EY UK Bank Lending Outlook suggested that it would be the only major lending segment to see accelerated growth this year, with corporate lending to halve from 5.3% to 2.1% and consumer credit growth to fall from 3.4% to 1.9%.
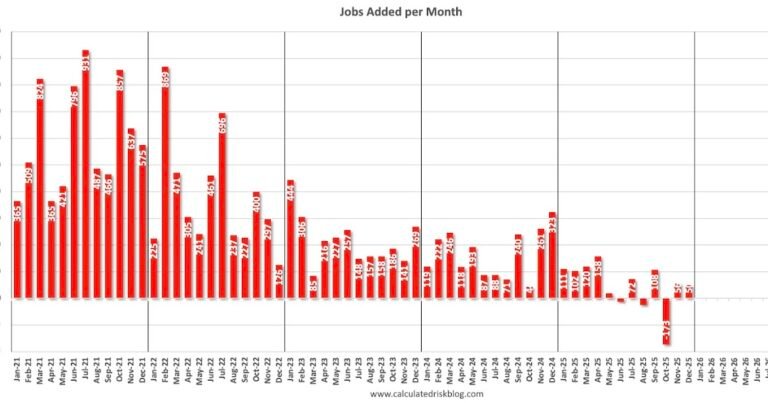
However, growth in the sector is forecast to slow to 2.2% in both 2027 and 2028, impacted by higher unemployment and slower income growth, which will weaken housing demand.
EY noted a steady rise in mortgage write-off rates since 2022, as households moved off lower fixed rates and paid higher monthly repayments.
It said most of this refinancing adjustment was complete and that, with rates predicted to rise marginally from 0.008% last year to 0.01% in 2026, 0.011% in 2027 and 0.01% in 2028, this would remain low by historical standards.
Overall, UK bank lending is expected to slow over the next two years, from 3.6% in 2025 to 2.1% this year, then rise moderately to 2.8% in 2027.
Episode 2: Affordability : Powered by Partnership podcast from Newcastle for Intermediaries
Sponsored by Newcastle for Intermediaries
UK bank lending growth to continue amid geopolitical uncertainty
Martina Keane, EY UK and Ireland’s financial services leader, said: “Ongoing geopolitical tensions continue to create uncertainty for businesses in the UK. While the bank lending forecast reflects the impact of global economic challenges, it is important to keep this in perspective, with growth still set to continue across all major categories. The UK banking sector remains resilient and well-positioned to navigate this period of slower activity and banking leaders should remain focused on the longer-term picture, while being ready to adapt quickly should conditions change.
“At the same time, prolonged economic uncertainty means changing customer needs – households may look for greater financial flexibility, while businesses often take a more targeted approach to investment. As banks support customers through these near-term pressures, those who continue to invest in artificial intelligence, emerging technology and broader transformation programmes to tailor their services will be best positioned to capitalise on future opportunities as the economy strengthens.”
Dan Cooper, EY UK and Ireland’s head of banking and capital markets, added: “The moderation in lending activity is broad-based, as households and businesses become more cautious in response to economic uncertainty and higher costs. Business investment, housing activity and consumer borrowing are all anticipated to remain subdued in the near term. Importantly, though, write-off rates are expected to remain low and stable across all categories, suggesting slower demand rather than a deterioration in credit quality.
“The UK’s banks enter this period from a position of strength, having built robust capital positions, greater resilience, and disciplined risk management. This means they are well-placed to support customers while continuing to invest for the future, so they are ready to meet demand as the economy stabilises and borrowing appetite returns.”