Senior citizen paid ₹9.91 lakh tax on tax-free bond interest by mistake: How he got a refund
A senior citizen who mistakenly paid ₹9.91 lakh in excess tax on interest from tax-free bonds has secured relief from the Income Tax Appellate Tribunal (ITAT), after the assessing officer initially refused to correct the error.
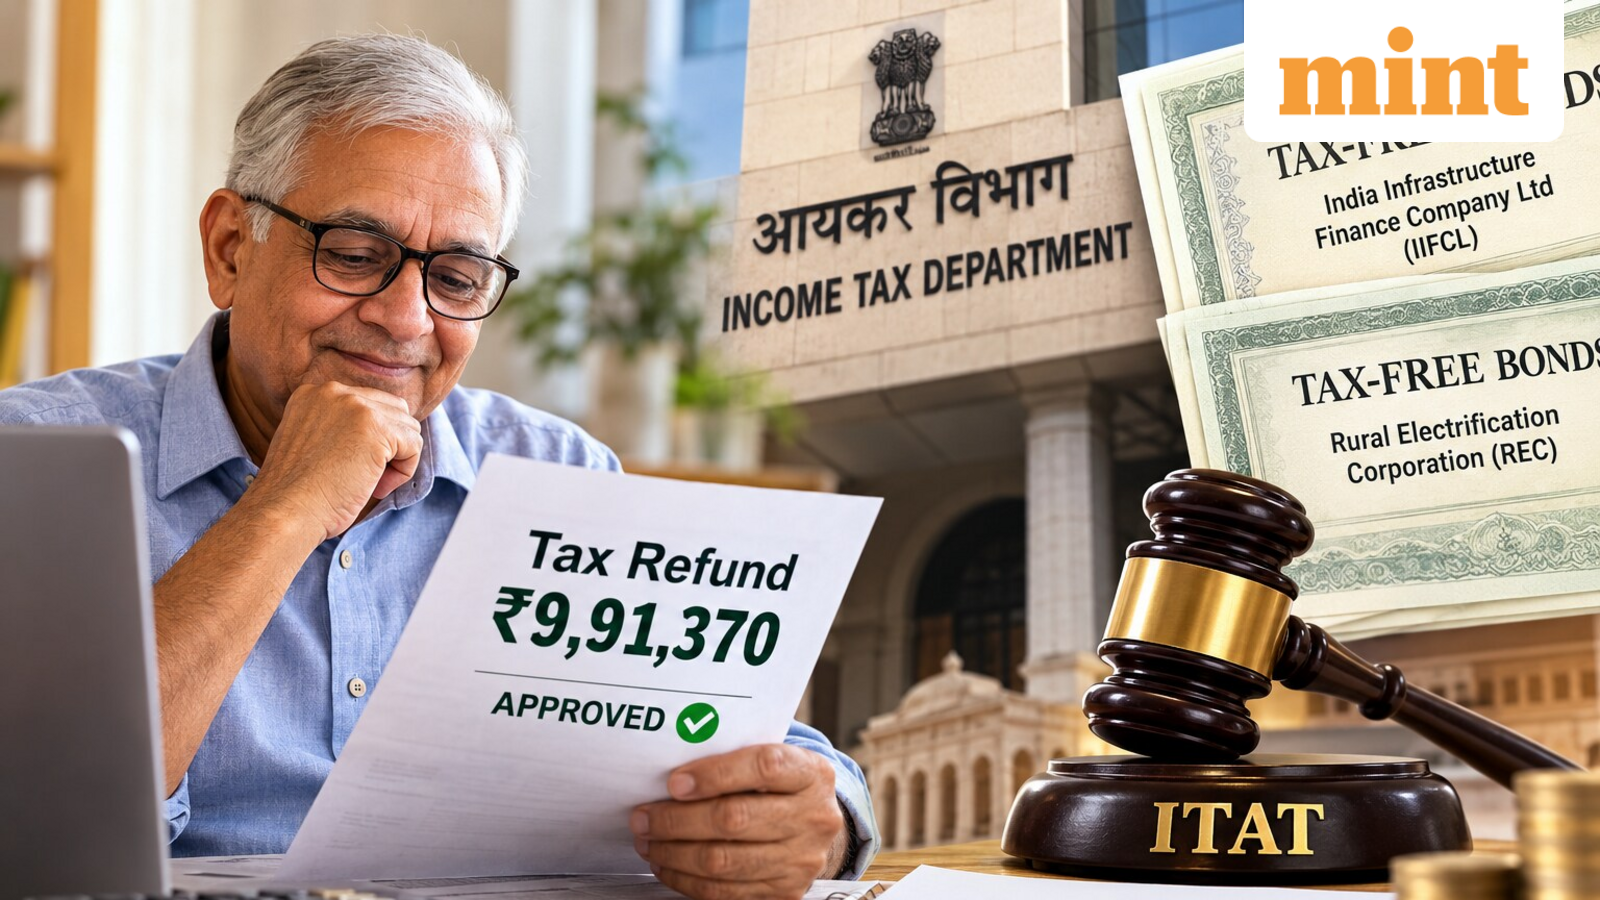
The case concerns Ajay Kumar Bakaya, a resident senior citizen from Gurugram, who had invested ₹3 crore in tax-free bonds and had regularly reported the interest as exempt income in his income-tax returns, Upstox reported.
The ITAT has now directed the assessing officer to treat the interest as exempt and grant him a ₹9,91,370 refund, along with interest as admissible under law.
Senior citizen invested ₹3 crore in tax-free bonds
In February 2013, Bakaya invested ₹3 crore in tax-free bonds:
- ₹2 crore in India Infrastructure Finance Company Ltd (IIFCL) 8.48% tax-free bonds
- ₹1 crore in Rural Electrification Corporation (REC) 8.46% tax-free bonds
Interest earned from both bonds is exempt under Section 10(15)(iv)(h) of the Income-tax Act, 1961.
Bakaya reported the interest as exempt income in his tax returns for assessment years 2018-19 to 2024-25.
However, for AY 2022-23, he mistakenly included ₹25.42 lakh of interest as taxable income under “income from other sources”. This comprised ₹16.96 lakh from IIFCL and ₹8.46 lakh from REC, resulting in excess tax of ₹9,91,370.
Why the Income Tax Department initially rejected the refund
By the time Bakaya discovered the mistake, the deadline for filing a revised return under Section 139(5) had passed, Upstox reported.
He therefore approached the assessing officer on January 19, 2024, under Section 154 seeking rectification of the mistake and a refund.
The assessing officer rejected his application in an order dated April 7, 2025. The AO relied on the Supreme Court’s ruling in Goetze (India) Ltd. v. CIT, holding that the “Jurisdictional Assessing Officer cannot entertain a claim for deduction otherwise than by filing a revised return”.
However, according to the ITAT order, the assessing officer had himself recorded a “categorical factual finding” that the bond income was “erroneously added as taxable income while filing the tax return” and should have been treated as exempt.
The CIT(A)/NFAC subsequently sustained the addition, after which Bakaya approached the tribunal.
What the ITAT said
The ITAT agreed with Bakaya’s counsel that he was not making a fresh claim because the interest income had already been disclosed in the original return. The mistake was only in its classification.
The tribunal observed that “the rectification sought by the assessee is a correction of a mistake apparent from the record and not a fresh claim” and held that the Goetze (India) Ltd. ruling was not applicable to the facts of the case.
The bench also relied on its coordinate bench ruling in Kapil Dev Nikhanj v. ACIT, which stated: “right amount of tax should be collected from the right person in accordance with law.”
The earlier ruling also held that when a particular receipt is exempt under law, “the said receipt cannot be brought to tax merely because the assessee had offered erroneously in the return of income”.
It further stated that “revenue cannot take advantage of ignorance of the assessee while determining the taxable income.”
ITAT orders ₹9.91 lakh refund
The tribunal directed that the bond interest be treated “as exempt under section 10(15)(iv)(h)”.
It also directed the assessing officer “to grant the consequential refund of ₹9,91,370 to the assessee, along with interest as admissible under law”.
What taxpayers can take away
The case highlights the distinction between making a fresh claim and correcting a mistake already apparent from the tax return.
In Bakaya’s case, the bond interest had already been disclosed in the return; the error was that exempt income was classified as taxable. The ITAT therefore allowed the rectification and ordered the refund despite the revised-return deadline having passed.
For investors holding tax-free bonds or other exempt investments, the case also underscores the importance of checking how exempt income is reported before filing an income-tax return.