₹1.25 crore received under power of attorney: When can taxman treat property money in your account as taxable income?
Receiving money in your bank account does not automatically mean the amount belongs to you for income-tax purposes. A recent Income Tax Appellate Tribunal (ITAT) ruling has highlighted this distinction in a case involving ₹1.25 crore received by a taxpayer while acting as a power-of-attorney (PoA) holder in a property transaction.
The Chennai bench of the ITAT, in its 22 September 2026 order in the case of Duraisamy Victor vs ITO, deleted an addition of ₹1.25 crore that the tax department had treated as unexplained money under section 69A of the Income Tax Act. The tribunal found that the taxpayer had received the money on behalf of three property owners under a registered PoA and subsequently passed it on as an advance for another property.
The ruling is relevant for people who handle property transactions on behalf of family members or other owners, particularly where large sums temporarily move through their bank accounts.
Money received under PoA does not automatically become your income
The taxpayer, Duraisamy Victor, was acting as a power-of-attorney holder for three property owners. The PoA, executed in 1996, authorised him to receive advances and sale consideration on behalf of the owners.
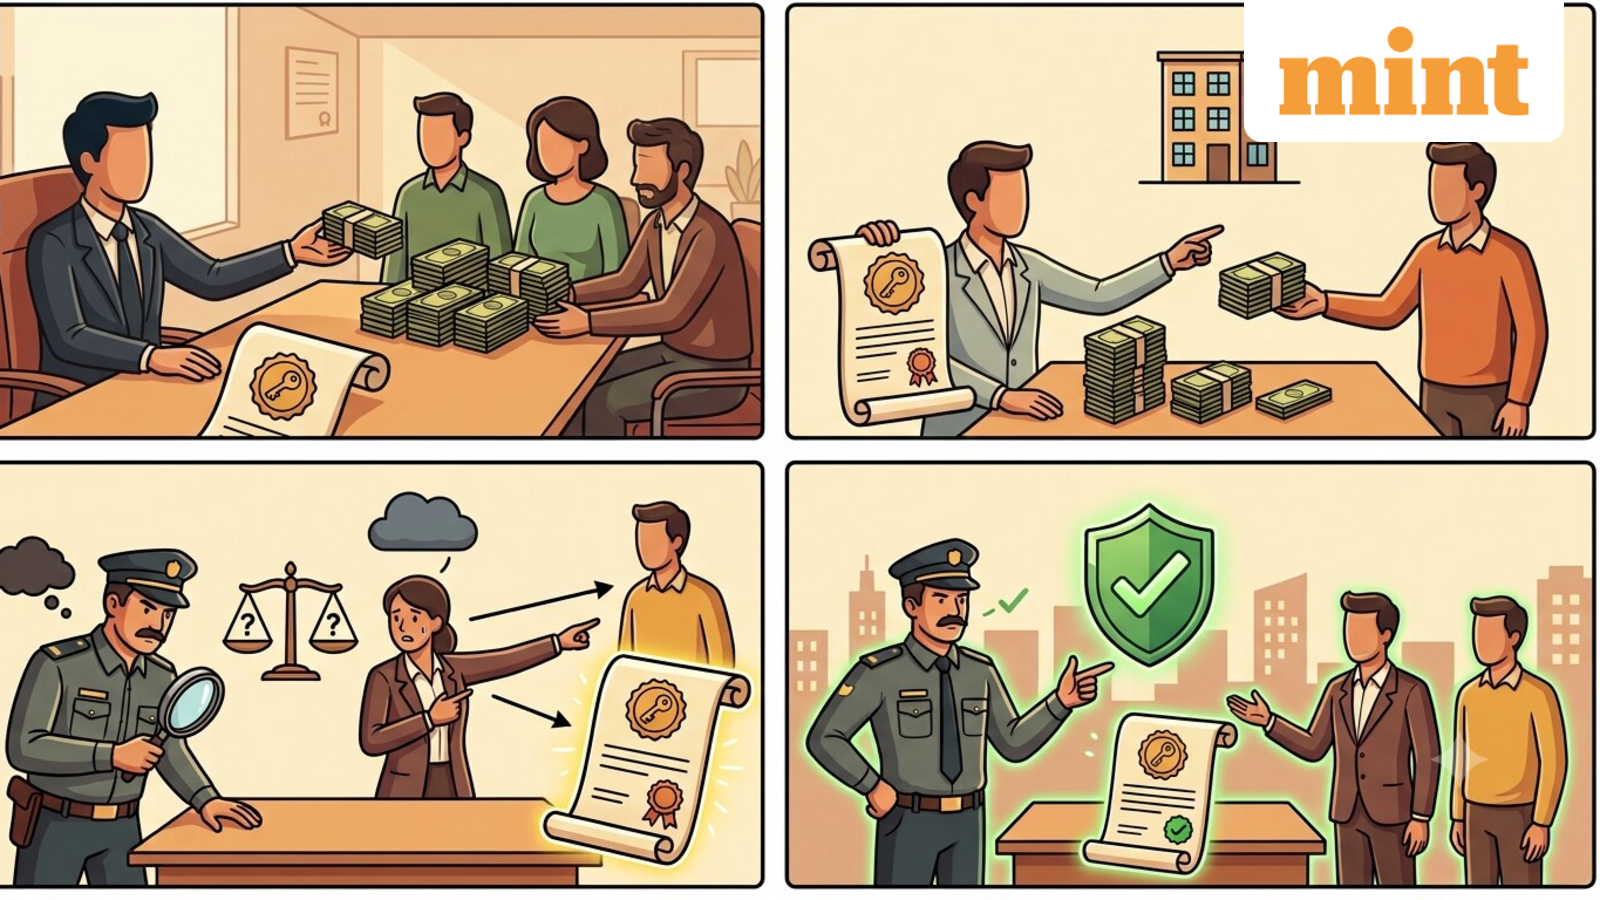
During July and August 2016, three purchasers paid a total of ₹1.25 crore to Victor in 16 instalments. The taxpayer’s explanation was that he was only acting as an intermediary. On instructions from the property owners, he subsequently paid the corresponding amounts to another property owner, Nalini Selvaraj, as an advance for purchasing her property.
The assessing officer, however, treated the ₹1.25 crore as unexplained money in Victor’s hands under section 69A.
The tribunal examined the flow of funds and noted that the amounts received from the purchasers corresponded with the amounts subsequently paid to Selvaraj. It also took note of the fact that the tax department had examined the same transaction in the assessment of Selvaraj and had not made an addition in respect of the ₹1.25 crore.
The bench therefore found that the evidence supported Victor’s explanation that he was acting as a PoA holder rather than receiving the money for his own benefit.
For taxpayers, the broader takeaway is that the person whose bank account receives the money and the person to whom the money actually belongs need not always be the same. However, the nature of the arrangement needs to be established through documentary evidence and the actual movement of funds.
A PoA by itself does not make every receipt tax-free. The crucial question is whether the taxpayer can establish that he was acting on behalf of the principal and that the money was ultimately meant for, or transferred to, that principal or another party as part of the authorised transaction.
Why documentation matters when you handle someone else’s money
The case also shows why people handling property money for someone else should maintain a clear documentary trail.
In Victor’s case, the tribunal considered the registered PoA, details of the payments received from the purchasers, the subsequent payments and the surrounding property documents. The matching movement of the ₹1.25 crore helped support his claim that the money was not his own.
The ITAT also deleted a separate addition of ₹66 lakh relating to cash deposits in Victor’s bank account. He had explained the deposits through current-year earnings, accumulated savings and ₹37 lakh received from his late brother’s estate. The tribunal found that the explanation was supported by the available records.
The ruling does not mean that large property-related receipts can simply be excluded from taxable income because someone claims to be acting as an agent or PoA holder. If the taxpayer cannot establish the capacity in which the money was received, the source of the funds and what happened to the money subsequently, the tax department can question the receipt.
For people acting as PoA holders, therefore, maintaining the registered PoA, sale agreements, payment instructions, bank statements, receipts and evidence showing onward transfer of the money can be important in establishing that the funds did not belong to them personally.
In Victor’s case, the ITAT ultimately held that the ₹1.25 crore could not be treated as his unexplained money and deleted the addition.