Who gets more time for tax audit and ITR filing as CBDT extends deadlines? Eligible taxpayers vs exclusions
The Central Board of Direct Taxes (CBDT) has extended the income-tax return (ITR) filing deadline for a specific category of taxpayers for Assessment Year (AY) 2026-27.
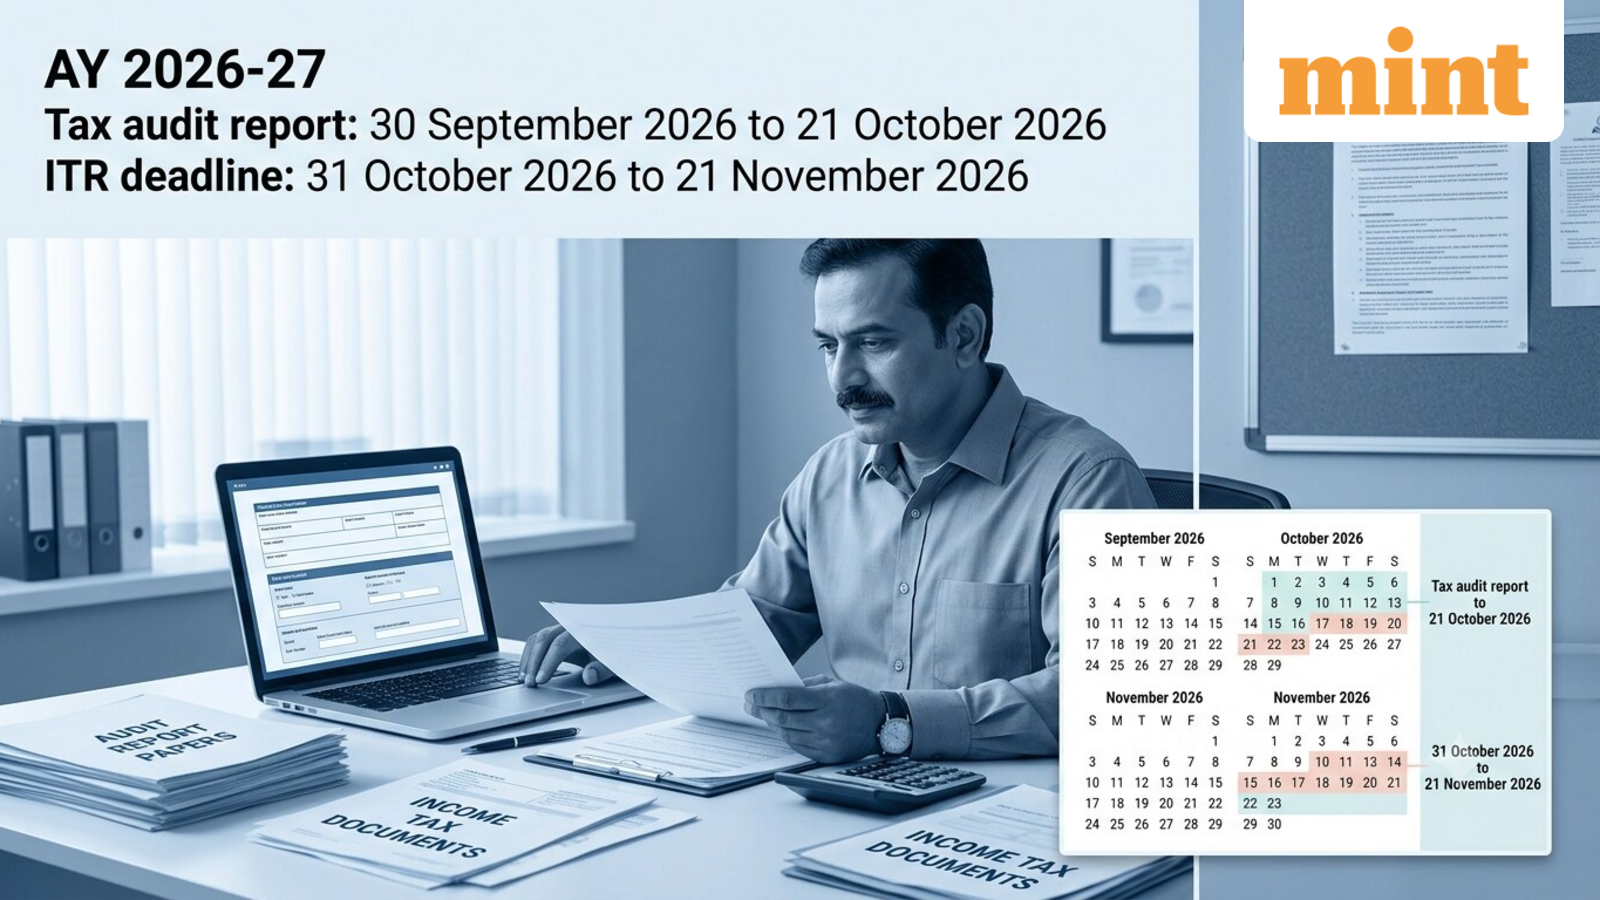
The ITR deadline has been extended from 31 October 2026 to 21 November 2026, while the deadline for furnishing the tax audit report has been extended from 30 September 2026 to 21 October 2026.
According to the X post by the Income Tax Department, “The Central Board of Direct Taxes (CBDT) has decided to extend the due date of furnishing of Return of Income for Assessment Year 2026-27 in the case of persons mentioned at S. No. 2 in the Table below Explanation 2 to sub-section (1) of section 139 of the Income-tax Act, 1961 from 31st October, 2026 to 21st November, 2026.”
But who exactly gets this additional time, who is excluded, and which ITR and tax-audit forms apply?
Which taxpayers are covered by the extension?
The extension relates to taxpayers covered under Sl. No. 2 of the Table in Explanation 2 to section 139(1) of the Income-tax Act, 1961, where the provisions of section 92E do not apply.
This category broadly covers:
- Companies
- Taxpayers other than companies whose accounts are required to be audited under the Income-tax Act or any other law
- Partners of firms whose accounts are required to be audited, including a spouse of such a partner where the provisions of section 5A apply.
The exact ITR form depends on the taxpayer’s status and the nature of income.
For example, ITR-6 is applicable to companies other than those claiming exemption under section 11, while ITR-3 applies to individuals and HUFs having income from profits and gains of business or profession. ITR-5 covers specified persons such as firms, LLPs, AOPs and BOIs.
Who is not covered by this extension?
Taxpayers required to furnish a report under section 92E are not covered by this particular extension. Section 92E applies where a taxpayer has entered into international transactions or specified domestic transactions and is required to obtain an accountant’s report in Form 3CEB.
For such taxpayers, the ITR due date under section 139(1) is 30 November of the assessment year, rather than 31 October. The Income Tax Department specifically distinguishes section 92E cases from the other audit-related category under section 139(1).
What are the new ITR and tax-audit deadlines?
The revised deadlines for taxpayers covered by the CBDT extension are:
- Tax audit report: 30 September 2026 to 21 October 2026
- ITR deadline: 31 October 2026 to 21 November 2026
In other words, taxpayers covered by the CBDT announcement get 21 additional days for both compliances.
The audit report needs to be furnished first, after which the taxpayer can use the audit-related information while completing the ITR. For taxpayers covered under section 44AB, the applicable forms include Form 3CA-3CD or Form 3CB-3CD, depending on the circumstances.
This means taxpayers covered by the extension can use the additional time to complete their audit, ensure that the audit report is correctly furnished, reconcile the figures with their ITR, and file the return by 21 November 2026.
Disclaimer: This is for informational purposes only. Please visit the official website for the latest updates.