Tax audit deadline September 30: Why AIS, TDS and GST figures may not match your ITR and what to do
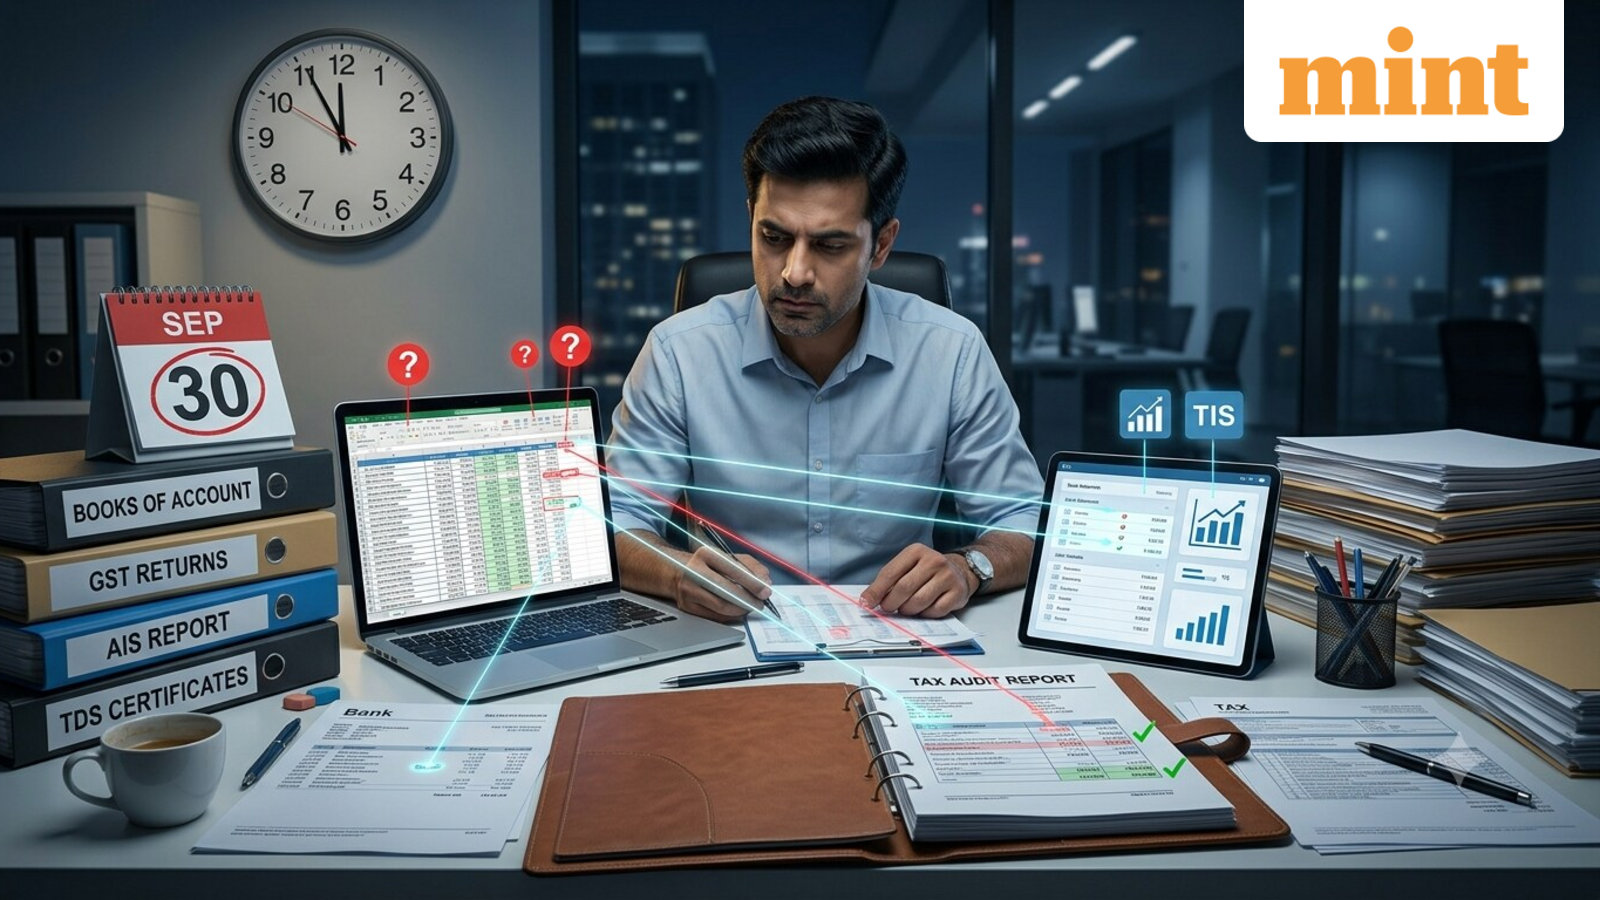
With the September 30 tax-audit deadline approaching, taxpayers should not assume that every figure in their books, GST returns, Annual Information Statement (AIS), Taxpayer Information Summary (TIS) and Form 26AS will necessarily be identical.
Differences can arise because of timing variations, duplicate reporting, incorrect information submitted by another entity or differences in accounting treatment. The important part is to identify the reason for the mismatch and ensure that the income-tax return and tax audit report are supported by the underlying records.
Sumeet Hemkar, Partner, Deloitte India, said taxpayers should ensure that the figures reported in their financial statements, books of account and tax audit report are consistent and reconciled with other statutory filings and reports.
Why your GST turnover may differ from your tax return
One of the areas taxpayers should examine is the difference between turnover reported in the books and turnover reported in GST returns.
A difference does not necessarily mean that one of the figures is incorrect. However, taxpayers should understand the reason for the variation and maintain supporting records.
The same reconciliation should be done for income and transactions appearing in AIS and TIS. Hemkar said taxpayers should compare these with their books of account and other relevant records rather than simply assuming that the information reported to the tax department is correct.
For taxpayers undergoing a tax audit, the figures in the financial statements, books and tax audit report should also be consistent with the relevant statutory filings.
AIS and TIS can show transactions that are not automatically taxable
AIS and TIS give taxpayers visibility into information reported to the tax department by banks, financial institutions, employers and other reporting entities.
This can include interest income, dividend income, securities transactions, professional or business receipts and other reportable transactions. However, taxpayers should not assume that every item appearing in AIS or TIS necessarily represents taxable income, Hemkar said.
The information should be checked against the underlying books, bank statements, tax certificates and other source documents. A difference could arise because of a timing variation, duplicate reporting, incorrect reporting by the concerned entity or differences in accounting treatment.
Therefore, if a transaction appears in AIS but does not correspond to the income reported in the ITR, the taxpayer should first establish what the transaction actually represents.
If the information reported in AIS is incorrect, the taxpayer can submit appropriate feedback through the AIS portal and, where necessary, seek correction from the reporting entity.
TDS mismatch can affect your tax credit
Taxpayers should separately reconcile their TDS and TCS credits with Form 26AS, AIS and the relevant TDS/TCS certificates. A mismatch can arise because of incorrect PAN reporting, an error by the deductor or collector, or non-filing or delayed filing of the relevant TDS/TCS statement.
Hemkar said taxpayers should identify the reason for the mismatch rather than automatically claiming the credit or deciding to leave it out of the return.
For example, if TDS has actually been deducted but the deductor has incorrectly reported the taxpayer’s PAN, the taxpayer should seek correction from the deductor. An unresolved mismatch can potentially result in denial of the tax credit and an additional tax demand.
Your tax audit report also needs to match the ITR
Reconciliation should not stop with GST, AIS and TDS.
Hemkar said taxpayers sometimes omit income, deductions, tax adjustments, brought-forward losses or unabsorbed depreciation in the tax audit report, creating inconsistencies with the return of income.
Taxpayers should also check whether relevant tax disallowances have been properly considered. These can include disallowances arising from TDS non-compliance, cash payments beyond prescribed limits, delayed deposit of statutory dues and delayed payments to micro and small enterprises.
This is important because the profit shown in the books may not always be the same as the taxable income after applying the provisions of the Income-tax Act.
What taxpayers should do before September 30
The September 30 deadline should therefore not be treated simply as the date by which the audit report has to be completed. Taxpayers should use the time before the deadline to reconcile the numbers appearing across their records.
- Books vs GST returns: Reconcile turnover and identify the reason for differences.
- Books vs AIS/TIS: Check interest, dividends, securities transactions and other reported income or transactions.
- Books vs Form 26AS: Verify TDS and TCS credits.
- TDS/TCS certificates vs tax credits: Check whether the deductor or collector has reported the information correctly.
- Tax audit report vs ITR: Ensure income, deductions, tax adjustments, losses and other relevant disclosures are consistent.
“Taxpayers should not rely solely on AIS or TIS. The information reflected in these statements should be verified against the books of account, source documents, bank statements, tax certificates and other relevant records,” Hemkar said.
For taxpayers, the objective is not to make every number across every system identical. It is to understand and document legitimate differences and correct errors before filing.