Can money collected for someone else be taxed as your income? ITAT ruling on ₹20.33 lakh cash deposits
An 89-year-old retired school principal’s explanation for ₹20.33 lakh in cash deposits has prompted the Income Tax Appellate Tribunal (ITAT) to order a fresh examination of whether the money actually belonged to him or was collected on behalf of an education society.
According to the 22 September 2026 order of the Bengaluru bench of the ITAT in Suleekere Kallegowda Rajashekar v. Income Tax Officer, Ward-1, Tumakuru, ITA No. 2405/Bang/2025, the taxpayer said the deposits represented hostel fees collected from students of Sri Vidya Peetha (R) Education Society, with only ₹2,251 allegedly remaining as surplus.
Why the tax department questioned ₹20.33 lakh deposits
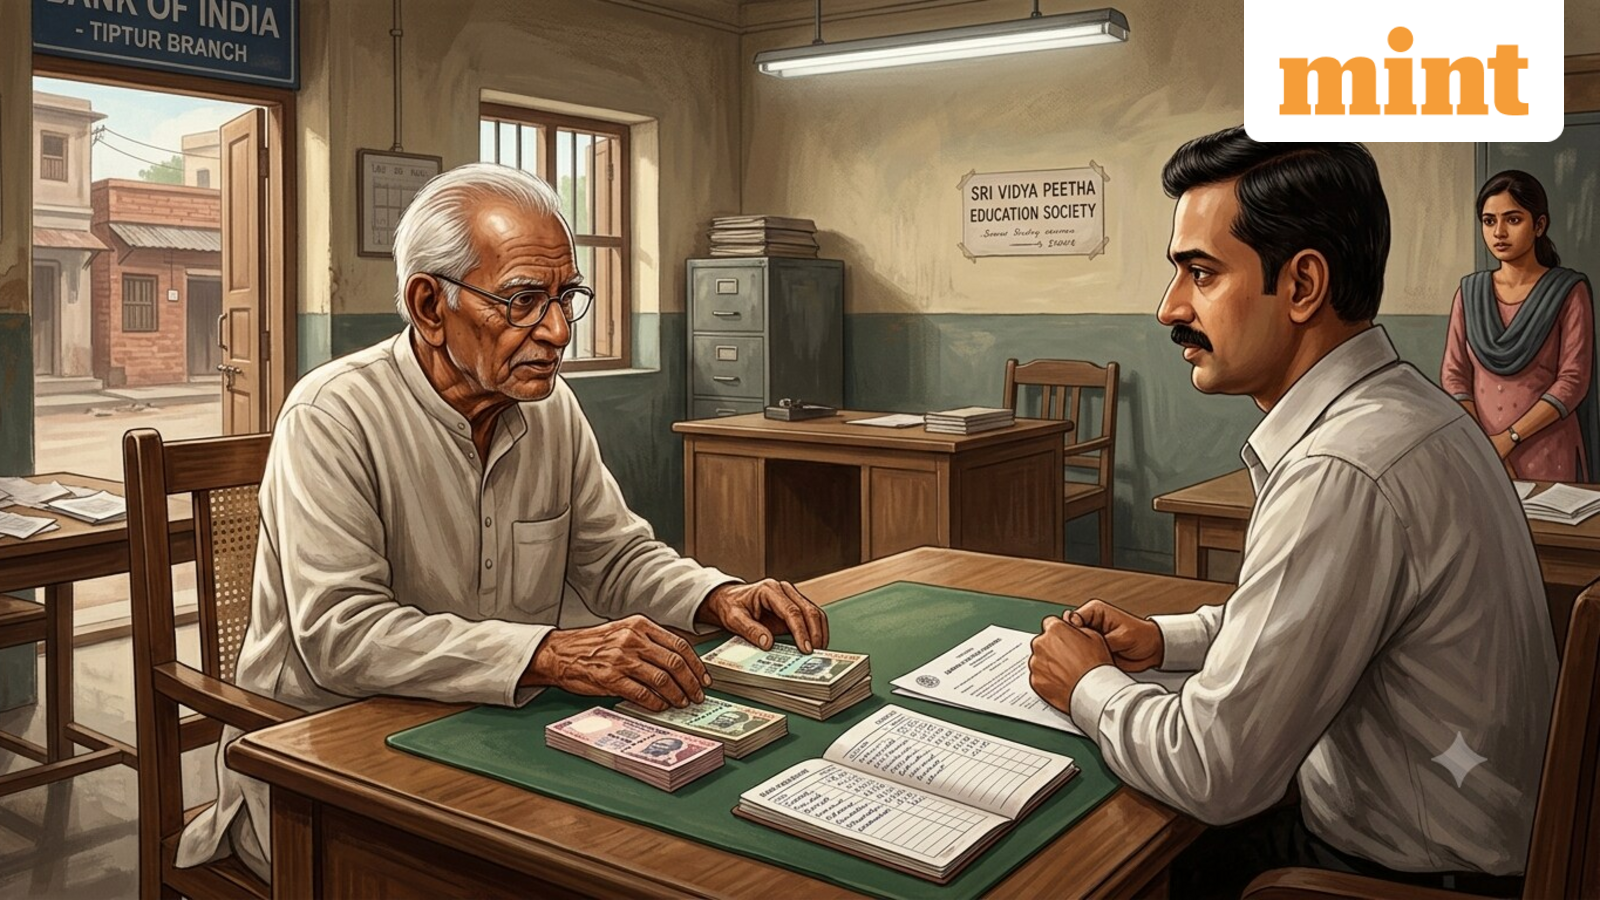
The case relates to assessment year 2017-18. The taxpayer had deposited ₹20.33 lakh in cash into two Bank of India accounts at Tiptur.
According to the order, ₹19.23 lakh was deposited through more than 50 entries in one account, while another ₹1.10 lakh was deposited through four entries in the second account.
The taxpayer’s return had declared total income of ₹5.72 lakh from salary, house property and other sources. The return was subsequently selected for limited scrutiny to examine the cash deposits.
The taxpayer explained that the money represented hostel fees collected from students. He said he was managing a ladies’ hostel for Sri Vidya Peetha (R) Education Society and that the hostel was being run on a no-profit basis.
He claimed that the collections were deposited into his personal bank accounts for administrative convenience and that the same accounts were used to meet hostel-related expenses. After accounting for the expenses, only ₹2,251 remained as surplus, which he had offered to tax.
The Assessing Officer (AO), however, was not satisfied with the explanation. The taxpayer had not produced sufficient supporting documents, including original hostel-fee receipts and a complete income-and-expenditure statement, to establish the source and utilisation of the cash.
The AO consequently treated the entire ₹20.33 lakh as unexplained money under section 69A of the Income-tax Act.
The Commissioner of Income Tax (Appeals) subsequently upheld the addition.
ITAT asks tax officer to verify society’s records
Before the ITAT, the taxpayer again argued that he had merely collected the hostel fees on behalf of the education society and that the deposits did not represent his personal income.
The tribunal did not accept the explanation without verification. Instead, it restored the matter to the AO for a fresh examination of the underlying records.
The ITAT directed the AO to verify whether the ladies’ hostel was being operated by the taxpayer on behalf of or in connection with Sri Vidya Peetha (R) Education Society. It also directed the tax officer to examine whether the hostel receipts were issued by the society and whether those receipts were recorded in its books.
If the receipts were found to belong to the society and were duly accounted for in its books, the tribunal said the addition in the taxpayer’s hands should be deleted.
However, if the receipts were not issued in the society’s name or were not recorded in its books, the taxpayer would have to explain how the total collections resulted in only ₹2,251 of surplus after meeting the hostel’s expenses.
The tribunal therefore did not hold that money deposited in a taxpayer’s personal bank account on behalf of another entity is automatically outside the scope of taxation. Instead, it stressed the need to establish who actually owned the money and whether the claimed collections and expenses were supported by records.
The ITAT also condoned a 666-day delay in filing the appeal. The tribunal noted that the taxpayer was 89 years old and had cited age-related health and mobility issues for the delay.
The appeal was ultimately allowed for statistical purposes, with the disputed addition remanded to the AO for fresh examination.
The ruling highlights an important issue for taxpayers who collect or handle money on behalf of societies, associations, institutions or other entities: a bank deposit does not by itself establish that the entire amount is the account holder’s income, but the taxpayer needs documentary evidence to establish the actual ownership and purpose of the funds.