FD rules change from 1 October: What depositors should know about bulk deposit rates
Fixed deposit investors in commercial banks are set to witness key changes in how banks disclose, present, and apply interest rates on bulk fixed deposits, starting from 1 October 2026.
This is because the Reserve Bank of India (RBI) has introduced revised rules aimed at making bulk deposit rates transparent, easy to understand, and ensuring that similar deposits receive consistent rates across a bank’s branches.
The revised framework applies to commercial banks, small finance banks, regional rural banks (RRBs), local area banks, payment banks and urban cooperative banks. These new changes and developments are extremely important for customers placing large deposits, as bulk deposits are treated differently from regular retail FDs.
Bulk FD rates to be disclosed every working day
From 1 October, banks will have to publish their applicable bulk-deposit interest rates on their official websites by 10 am on every working day. A 10-minute grace period means the rates can be updated up to 10:10 am.
Banking institutions will also be mandated to follow the rates displayed on their websites when paying interest on eligible deposits. This will give depositors a straightforward reference point when negotiating or booking a larger term bulk deposit.
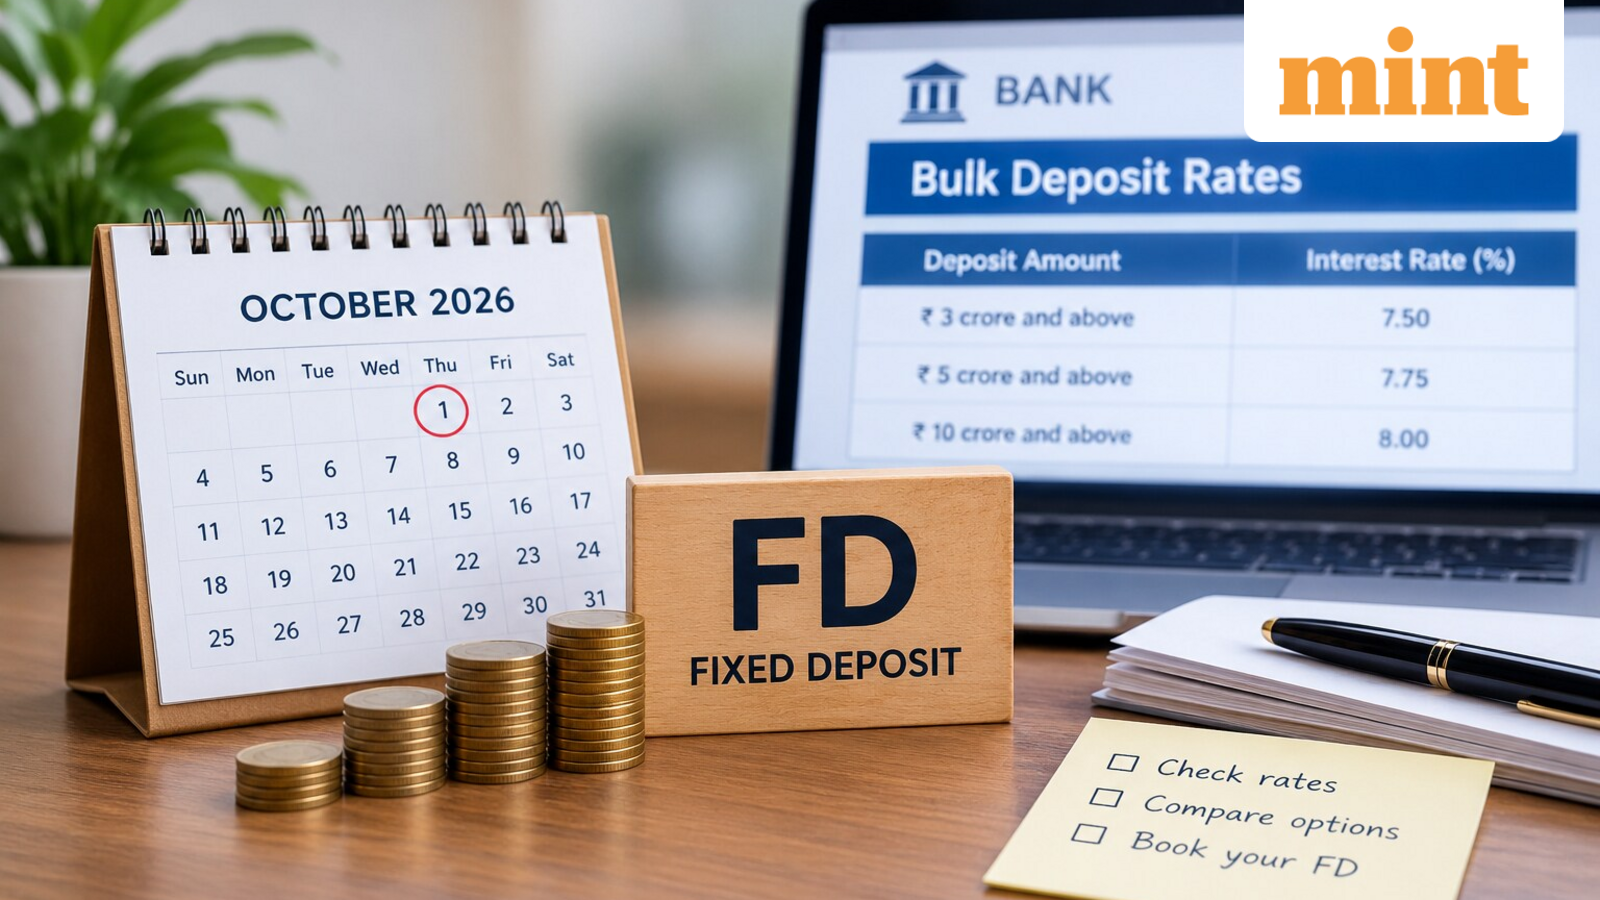
It is important to keep in mind that for scheduled commercial banks, a bulk deposit generally refers to a single-rupee term deposit of ₹3 crore and above. Still, the applicable threshold differs for some categories of banks.
Same rate across branches, with an important exception
Another significant change to be implemented is that banks will not be permitted to offer different interest rates for similar bulk deposits merely because they are booked at different branches.
This will ensure that, for deposits of a similar amount accepted on the same day, the applicable rate is consistent across the bank’s branches.
However, banks can differentiate rates for bulk deposits based on the ‘Liquidity Coverage Ratio’ (LCR) treatment applicable to the deposit. The same flexibility will also apply to certain rupee deposits held by non-residents.
This means that banks can offer different interest rates to eligible individuals on bulk deposits by taking into account the applicable run-off rate under the LCR framework. Furthermore, the new rules affect not only domestic deposits but also certain bulk deposits held under the non-resident rupee deposit framework.
What is the meaning of these changes for fixed deposit investors?
Now, for most retail fixed deposit (FD) investors, these changes do not mean that their existing FD interest rates will automatically change or get amended in any way starting from 1 October 2026. The new framework is primarily about how banking institutions will determine, disclose and apply rates on bulk deposits.
In summary, for depositors depositing large sums, checking the bank’s published rate on the date of booking will be relatively easy and particularly important. Such a disclosure by the banks will also provide a way for aspiring bulk fixed deposit investors to carefully compare the applicable rate and understand whether different treatment is based on the deposit’s characteristics or regulatory requirements.