EPF withdrawal rules: What happens if you withdraw full amount due to unemployment and later get a new job
Losing a job and being unable to find another one, or staying out of the workforce due to other issues for a long period can put pressure on your savings, including the money accumulated in your Employees’ Provident Fund (EPF) account.
For members facing an extended spell of unemployment, withdrawing the accumulated PF balance can seem like an option to manage expenses. Salaried individuals are allowed to make partial withdrawals, known as EPF advances, for certain purposes, with eligibility conditions.
Withdrawal on leaving employment
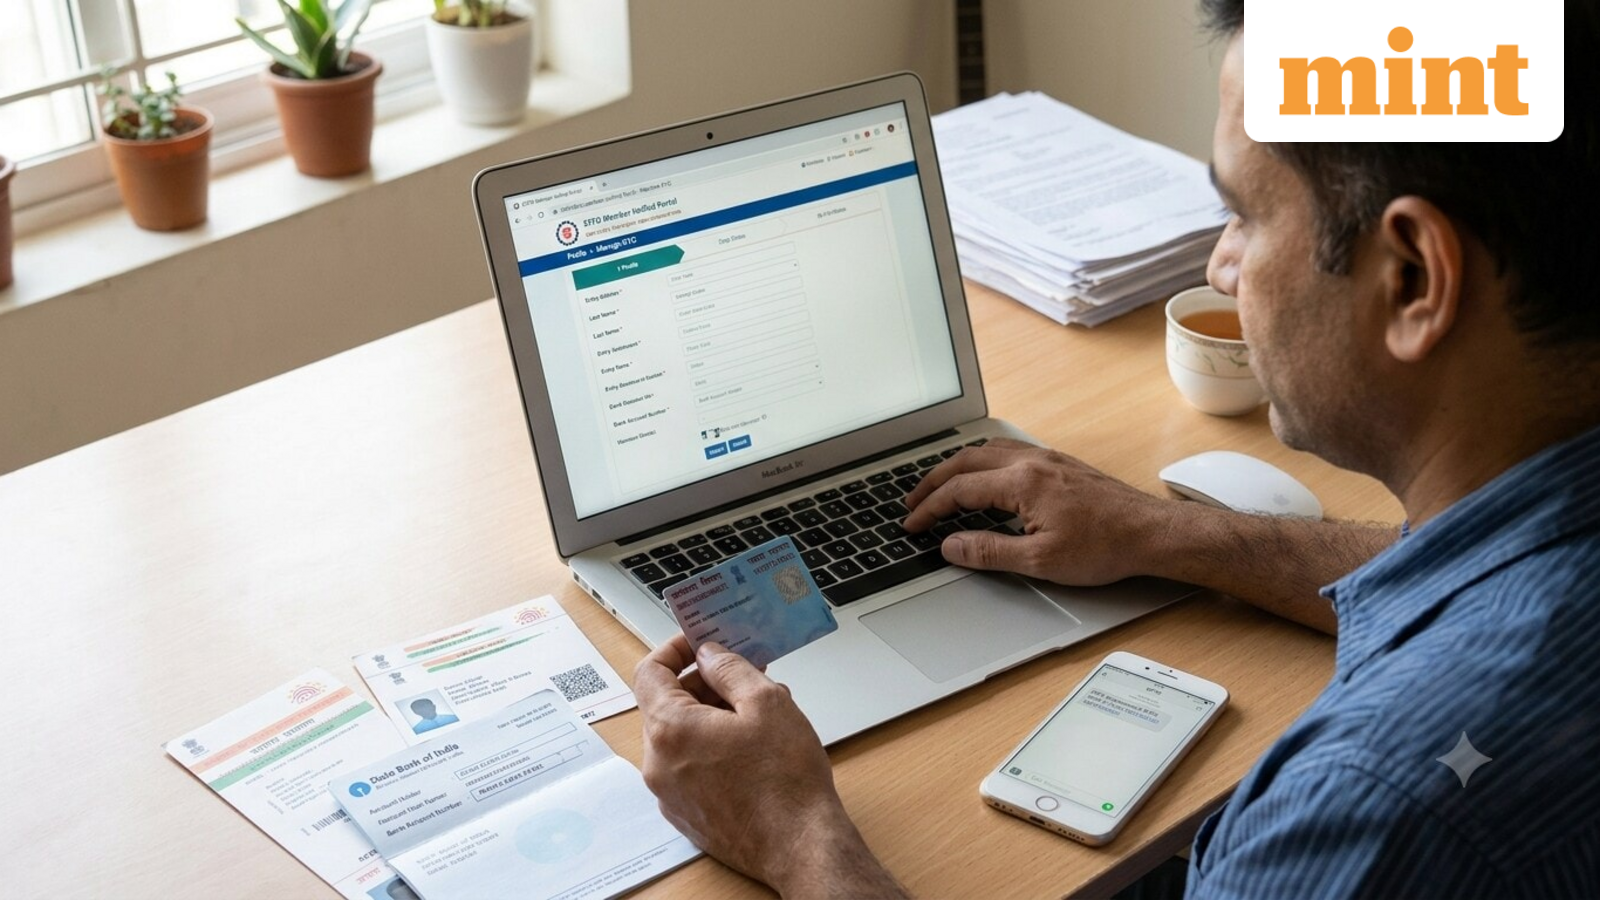
After leaving employment, an individual can apply to the Employees’ Provident Fund Organisation (EPFO) for withdrawing their PF balance.
Under the EPF Scheme, 2026, members can withdraw up to 75% of their PF balance immediately after losing a job. The remaining 25% stays locked in until the member completes 12 months of continuous unemployment. Only then does full withdrawal open up, which includes the employee share, employer share and accumulated interest.
Earlier, full withdrawal was allowed after two months of unemployment. But that changed with the introduction of the new scheme in July this year.
However, the 12-month waiting period will not apply to female members who have resigned from their job for getting married.
What if you become employed again?
If an individual finds a job after making a full withdrawal under the prescribed conditions, the person will have to qualify again for membership of the fund, and they will be treated as a fresh member, according to information available on the official website of the retirement fund body.
In simple terms, getting employed again does not reverse the earlier EPF withdrawal. Instead, the new employer will generally create or link EPF contributions to the member’s existing UAN, allowing fresh contributions to accumulate under the new employment.
Early EPF withdrawal can attract tax
However, individuals must remember that if provident fund is withdrawn before completing five years of continuous service and the withdrawal amount exceeds ₹50,000 in a financial year, it may become taxable.
For example, if you withdraw your EPF balance after three years of service, the withdrawal may have tax implications if the termination does not qualify for an exemption under the applicable rules.
Certain situations, such as termination due to circumstances that are beyond the employee’s control, are treated differently, and the withdrawal will be exempt from tax, according to a blog post by Ujjivan Small Finance Bank.
In other cases, if EPF is withdrawn before completing five years of continuous service and the withdrawal amount exceeds ₹50,000, TDS is deducted at 10% provided the employee has furnished PAN details. If PAN is not available, then TDS (tax deducted at source) may be applicable at a higher rate of 20%.
However, employees whose total taxable income, including the EPF withdrawal amount, falls below the taxable limit can submit Form 121 to avoid TDS deduction. In such cases, no TDS is deducted if the form is validly submitted.