DeFi Was Never Going to Get Its Clarity from US Congress
Last week’s failed CLARITY Act cloture vote
will be read as a setback for crypto. That reading misses where decentralized
finance (DeFi) compliance was actually heading.
London’s trading industry is coming home!
Investors have been watching legislative
headlines while the decisions that will govern DeFi access, sanctions
screening, and pre-settlement risk checks get written elsewhere.
CLARITY Doesn’t Set the Rules
The industry treated CLARITY as the moment it
would finally get regulatory certainty. The bill was never going to deliver
that. It covered a lot of ground, including AML program requirements,
protections for developers, and jurisdictional lines defining which agencies
would regulate different kinds of cryptocurrencies.
The questions that actually determine how much of DeFi stays open to
anyone with a wallet,
and how much becomes gated by compliance checks, would continue to be kicked
down the road. The bill handed those specifics to agency rulemaking, and for
AML-type screening, the relevant agency is Treasury.
A failed vote doesn’t pause regulation because
CLARITY was never delineating the rules. Treating the failure that way just
means DeFi keeps waiting to react to rules it could be helping shape.
The SEC Has Already Shown Us What’s Coming
Rulemaking didn’t need CLARITY and won’t wait
for it or another bill like it. The SEC has already shown how it plans to
regulate the industry. Rather than writing one comprehensive framework, the
agency has been issuing narrow, conditional rules one at a time, each with
tight limits on who qualifies and how long the relief lasts.
In August of this year, the SEC announced Regulation Crypto
Assets, proposing new
rules for how crypto projects can raise money by selling tokens. The exemptions
are tightly capped: $5 million over four years for early projects, and $75
million a year for larger raises only if the issuer provides financial
statements and ongoing reporting.
Last week, two days after the CLARITY cloture
failed, they followed this up with the Innovation Exemption, clarifying how
permissioned pools could legally offer tokenized equities. The exemption is
similarly constrained, with caps on how many stocks each venue can list and how
much each can trade, as well as requiring venues to screen who can trade. It
expires after five years.
Together, these two announcements show what
rulemaking for crypto is likely to look like in action. The industry should
expect regulation to happen under a very narrow set of conditions as the SEC
collects data on the effect regulated DeFi will have on existing markets. Once
that is better understood, a broader set of conditions and legislation from
Congress is likely to follow.
The emergence and adoption of AI is likely to
slow Congressional legislation timelines down even further, as it becomes the
emerging tech sector that demands regulators’ attention.
Crypto shouldn’t expect sweeping regulation to
come quickly. The SEC’s slow and steady progress on specific interpretations of
existing laws is more likely to be the default.
Crypto Needs Its Own Enforcement Layer
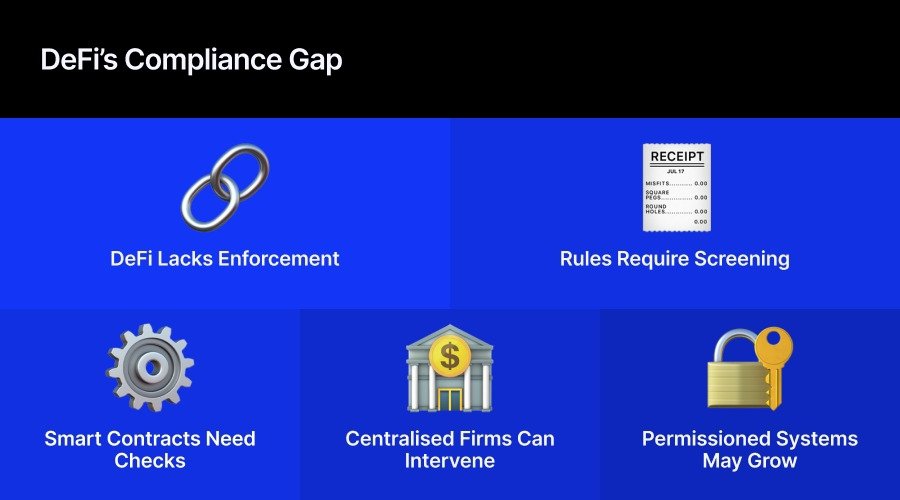
Either way, DeFi isn’t structurally prepared
for regulation. The rules being written elsewhere all assume DeFi can enforce
them, but right now only permissioned venues, like centralized exchanges, are
positioned to actually enact them.
Smart contracts ensure trustlessness only
within very specific parameters. As more rules take effect, the code will need
enforceable ways to check that transactions comply.
In traditional finance, that job belongs to
payment networks like Visa, but crypto has no equivalent layer. That gap leaves the industry exposed, putting
at risk the openness that decentralization promised. Without a way to run these
authorization checks natively, centralized companies will run them instead.
If DeFi doesn’t build that enforcement layer
itself, the only blockchain infrastructure that can actually comply will be the
kind banks run: permissioned, gated, and pointed back at the same institutions
DeFi was built to route around. The SEC has shown it won’t wait for permission
from Congress. DeFi shouldn’t either.
This article was written by Mohammad Akhavannik at www.financemagnates.com.