‘The alt solution is the prime solution’: Alternative borrowers increasingly staying put
Alternative lending was long treated as a temporary stop for borrowers with bruised credit on their way to qualifying with a major bank. Lenders now say that path is outdated.

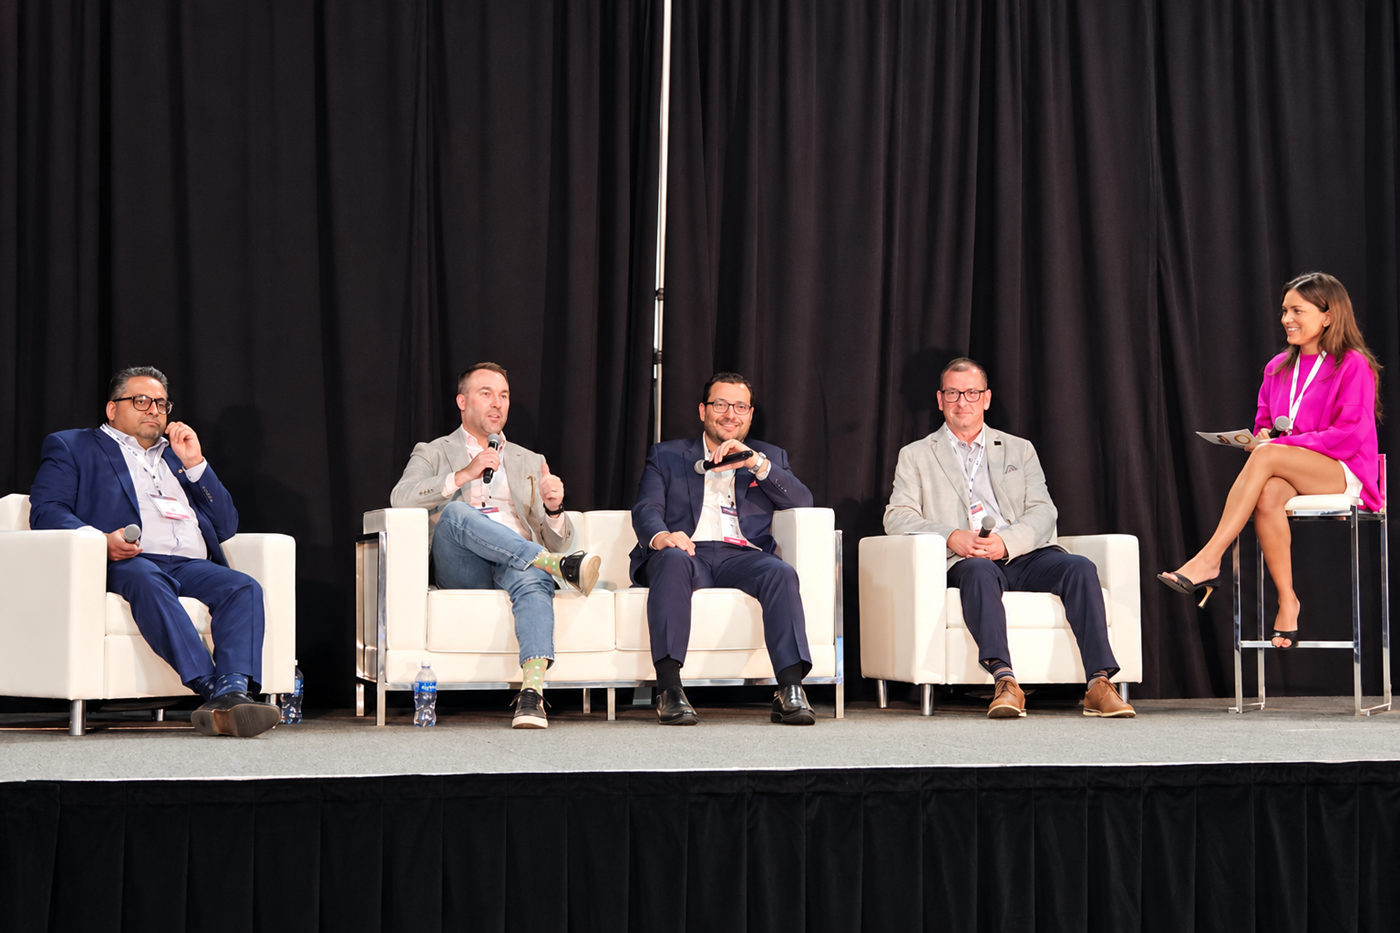
“Historically, alt business was perceived as a short-term solution for clients,” Prakash Bector, interim vice president of sales and distribution at EQ Bank, said during an alternative lending panel at an industry event in Toronto on Wednesday. “In many, many cases now, the alt solution is the prime solution for these clients.”
The panel also included Grant Armstrong, chief growth officer at WealthONE Bank of Canada; Cam DelliPizzi, regional sales director at MCAN Financial; and Joe Cote, chief operating officer at Haventree Bank. It was moderated by Sarita Free, a mortgage agent with Mortgage Intelligence.
From bruised credit to big balance sheets
Panelist Joe Cote, chief operating officer at Haventree Bank, suggested the definition of an alt borrower has widened considerably in a relatively short period.
He said Haventree’s borrowers now range from aging clients and people dealing with divorce, CRA debt or bankruptcy to small business owners affected by tariffs, investors with multiple properties and owners of rental or seasonal properties.

“There are millions of Canadians that do not fit the prime big six credit box on a full-time basis,” Cote said.
Panelist Grant Armstrong, chief growth officer at WealthONE Bank of Canada, added that bruised credit is now a much smaller share of the business than it was 15 or 20 years ago.
He said the average credit score in WealthONE’s portfolio is 763, which he noted compares favourably with borrowers at the big banks. Many of those borrowers are entrepreneurs, investors with multiple properties or clients with significant net worth. Armstrong attributed their exclusion from the banks’ credit box in part to tighter rules around how banks assess income.
“Banks have very, very specific ways of looking at income,” Armstrong said. “That’s where the alternative lenders come in.”
Bector argued that many of these borrowers aren’t using the alt lender as a stepping stone, pointing to EQ Bank’s pandemic-era 5-year fixed rate of 2.59%. “You know how many clients took us up on the 5-year fixed term?” he said. “Close to zero.”
Bector explained that most clients instead renewed with EQ Bank or moved to another alternative lender. For many alt borrowers, Bector said, brokers should focus on the most suitable solution rather than simply the lowest rate. That means working out what a client would have to change about their business or how they report income to qualify for a better rate, and whether those changes are realistic.
“Is it feasible? Can they do it? How much time will it take them? How much would it cost them to actually shift how they structure their business?” he said.

For clients who do want to move to prime eventually, Cam DelliPizzi, regional sales director at MCAN Financial, said brokers should plan the exit strategy from the start, looking one to three years ahead rather than focusing only on getting the initial approval. He noted that MCAN offers a graduation program to help clients make that transition.
Armstrong also encouraged brokers to work with lenders that pay compensation at renewal, since these clients often remain with the lender long term.
“The alternative space is part of your prime option. It’s as simple as that,” Cote said. “And if you’re not thinking about it that way, you’re losing opportunity for yourself.”
Package the file for the lender, not yourself
For self-employed borrowers, Cote said lenders look past the borrower’s personal earnings to what the business generates, using either bank statements or business financials.
As a result, he said the onus is on the broker to understand what kind of business the client runs, where its customers come from and what its overhead costs are. Brokers should also watch for personal expenses running through the business, he said.

Down payments also need the same scrutiny. Cote said the classic file, where funds sit in savings for 90 days with no movement, is increasingly rare. Whether the money comes from overseas, a relative, business income or elsewhere, brokers need to be able to document and explain its source.
When Armstrong asked how many of the more than 100 brokers in attendance had ever called a lender to ask how it calculates income, only two audience members raised their hands.
“I encourage every one of you: call your BDM, ask to meet with an underwriter, and ask the simplest question: How do you calculate income?” he said. “Then build the package for the lender. Because if you build it for yourself, it doesn’t help the lender.”
Armstrong said that approach made him one lender’s largest referral source for more than seven years when he was a broker. He added that brokers who push back on document requests put their approvals at risk.
“You could say, ‘You don’t need this,’ and we could also say we’re not approving it,” he said. “The best brokers collaborate, not become adversaries.”
Armstrong also suggested that brokers should flag problems, such as outstanding taxes or an unexplained wire transfer, proactively rather than wait for the lender to find them. “It’s better for you to put the red flag up when there’s a problem and come and ask for a solution than for us to put the red flag up and assume the worst,” he said.
Bector agreed, adding that complicated files aren’t what sink deals. “What kills deals are surprises,” he said. “The more info that we know up front, the better equipped we are to try to navigate a solution.”
DelliPizzi added that some of the best brokers he works with complete the employment verification calls themselves before submitting a file, so they know what the lender will hear.
Asked whether alternative lending will gain market share, Armstrong said the mortgage market continues to grow and brokers who stay out of the alt space are leaving opportunities on the table.
“A customer walks into your office and says, ‘I’m self-employed, I want to refinance to pay out the CRA,’” he said. “If you’re not in that space, you’re essentially saying, ‘I’m only interested in doing a teeny, weeny little part of the mortgage market.’”
Visited 5 times, 5 visit(s) today
alternative lenders alternative lending Cam DelliPizzi conference Grant Armstrong Joe Cote lender panel panel Prakash Bector
Last modified: September 24, 2026