Taxman called a penny-stock gain bogus after ₹70,000 became ₹1.93 crore, here’s what Mumbai ITAT said
A Mumbai investor’s ₹70,000 investment in Toyam Industries Ltd turned into a ₹1.93 crore long-term capital gain. The tax department treated the gain as an accommodation entry linked to alleged manipulation in the stock. The Mumbai Income Tax Appellate Tribunal, however, found that the department had not established a specific link between the investor and the alleged manipulation.
The ruling is significant for investors because the tribunal focused less on whether the stock itself had been investigated and more on what evidence existed against the individual taxpayer. In its 4 September 2026 order, the Mumbai bench deleted the ₹1.93 crore addition made under Section 68 of the Income Tax Act.
The ₹70,000 investment and ₹1.93 crore gain
Sanjaykumar Mehta had purchased 35,000 shares of Toyam Industries in April 2013 for ₹70,000. The shares were initially allotted in physical form and were later dematerialised through his broker, Inventure Growth & Securities, in August 2014.
Between September 2014 and February 2015, he sold the shares on the BSE at prices ranging from ₹447 to ₹556 a share. His overall long-term capital gains from shares were ₹2.14 crore, of which ₹1.93 crore came from Toyam Industries. The sale transactions were carried out through a recognised stock exchange, with STT reflected in the contract notes and sale proceeds received through the broker into his bank account.
Why the tax department rejected the gain
The case was reopened after information from the Income Tax Department’s Insight portal based on an Investigation Wing report. Toyam Industries was among 18 scrips identified as penny stocks in which the investigation alleged that artificial or pre-arranged transactions were used to generate bogus long-term capital gains and short-term capital losses.
The assessing officer said the sharp rise in Toyam Industries’ share price was not supported by the company’s financial fundamentals. According to the assessment, the scrip had been manipulated to create fictitious profits and facilitate the introduction of unaccounted money as capital gains.
The AO therefore treated Mehta’s ₹1.93 crore gain as unexplained cash credit under Section 68. The CIT(A) subsequently upheld the addition, holding that the investment had been made to obtain an accommodation entry.
But the tribunal identified a gap in the department’s case.
ITAT: Where is the evidence against this taxpayer?
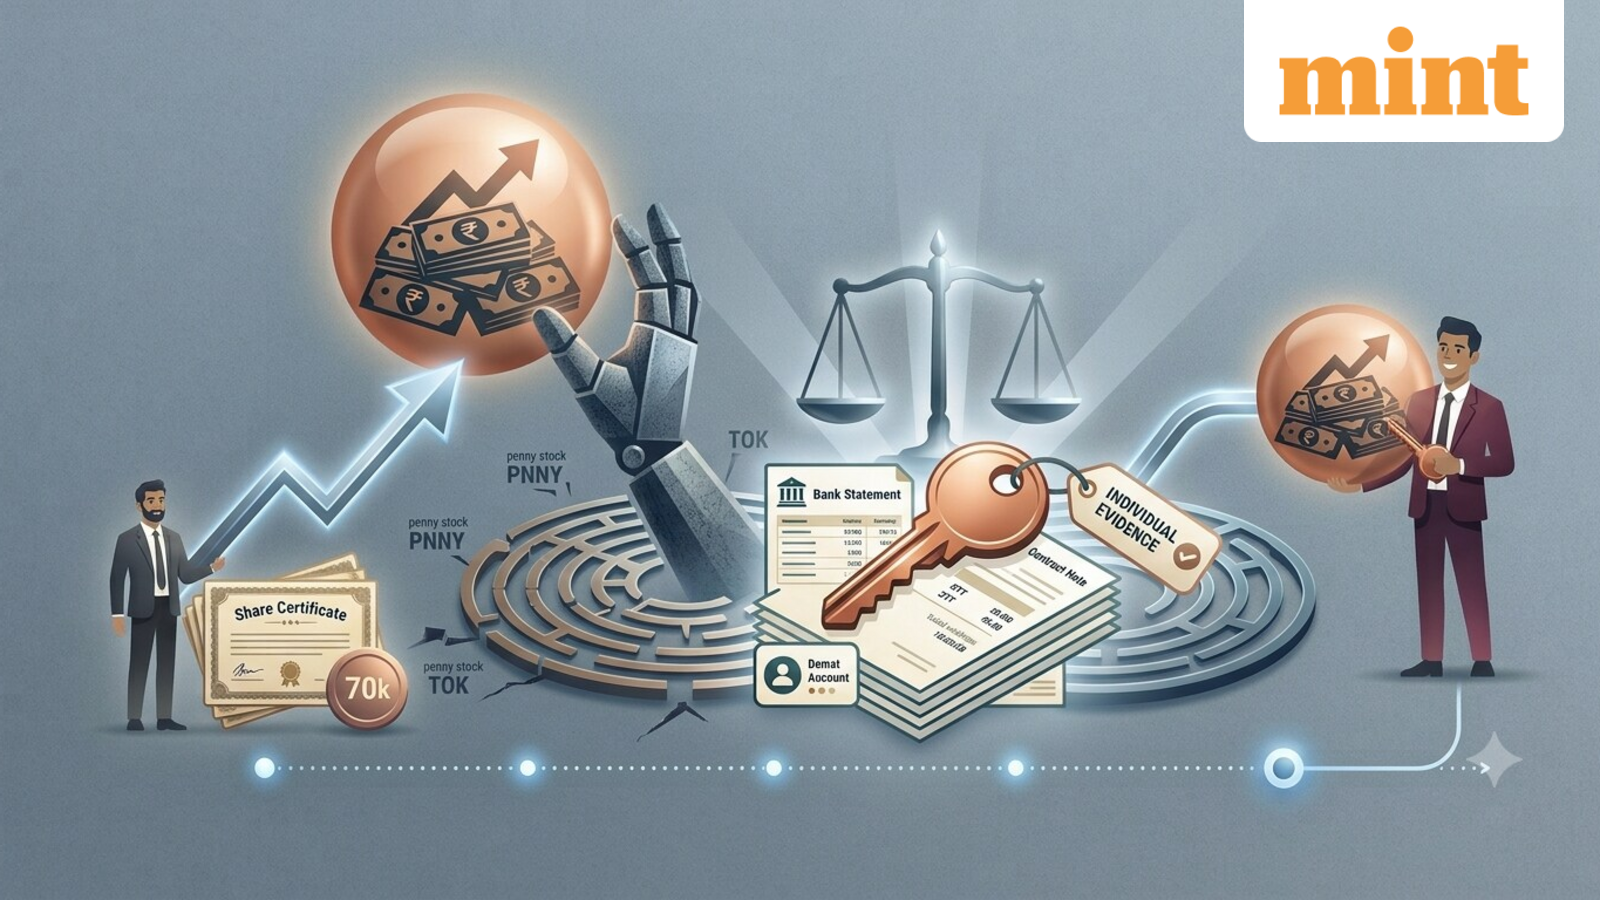
The tribunal noted that Mehta had submitted bank statements, demat statements, purchase and sale contract notes and other supporting documents. It also noted that the shares had been held for more than a year and were sold through a recognised stock exchange.
More importantly, the tribunal said the Revenue had not produced specific material demonstrating that Mehta himself was involved in price rigging, manipulation or any unlawful activity connected with the scrip.
The tribunal also referred to earlier ITAT decisions involving Toyam Industries and noted that similar additions had been deleted where taxpayers had produced documentary evidence supporting their transactions.
The Revenue had relied on the Calcutta High Court’s decision in PCIT v. Swati Bajaj, where certain penny-stock transactions were found to be manipulated. But the Mumbai ITAT distinguished that case, pointing out that in Mehta’s case there was no specific evidence of his involvement or collusion with an operator, broker, promoter or exit provider.
The tribunal ultimately held that Mehta had discharged the prima facie burden under Section 68 and directed the Assessing Officer to delete the ₹1,93,30,395 addition. It left the other legal grounds, including the challenge to reopening of assessment, undecided because the addition had already been deleted on merits.
What the ruling means for investors
The order does not mean that gains from penny stocks will automatically be accepted by the tax department or courts.
Instead, it highlights the importance of the evidence connecting an individual taxpayer to an alleged accommodation-entry arrangement. In this case, the tribunal relied on the documented transaction trail and the absence of specific evidence against the taxpayer.
For investors, that makes the record of a share transaction particularly important. Purchase documents, demat statements, contract notes, bank records and evidence of exchange-based sales can become relevant if the transaction is later questioned by the tax authorities.
The underlying distinction in the ruling is therefore between evidence that a particular scrip was allegedly manipulated and evidence that a particular investor participated in that manipulation.