Visa Says Small Merchants Could Move Faster on AI Shopping
Small merchants are preparing for a customer who may find them through artificial intelligence before ever visiting their website, app or store.
They aren’t particularly ready. Just 11% of small- to medium-sized businesses (SMBs) qualify as agent-ready, compared with 19% of large merchants. The PYMNTS Intelligence report “2026 Global Digital Shopping Index: Merchant Edition,” a collaboration with Visa Acceptance Solutions, found in June that 15% of merchants overall have structured product data for agent access. Yet 68% expect AI agents to account for at least 5% of digital sales within two years, and 38% expect more than 15%.
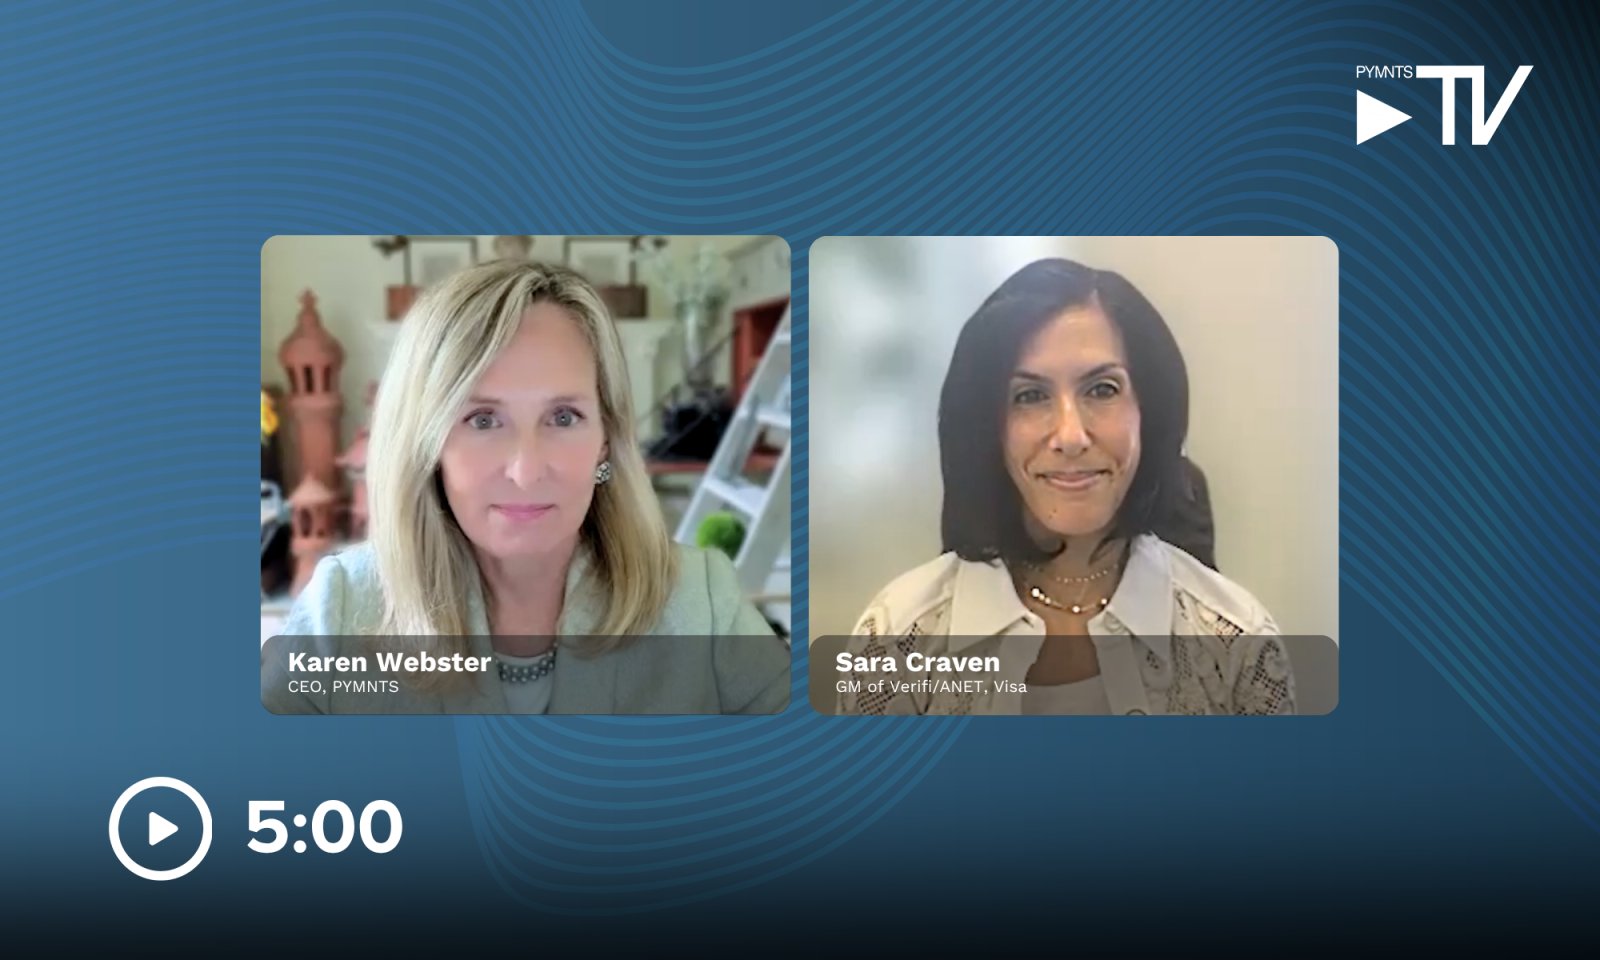
Sara Craven, general manager of Verifi/ANET at Visa, told PYMNTS CEO Karen Webster that SMBs may be able to close the gap faster than their larger competitors.
“Small businesses have a distinct ability to pivot faster, to move faster,” Craven said, adding that “with AI, they have the ability to learn a lot faster.”
One place to start is the product catalog.
A description written for someone browsing a website may not give an AI model enough information to answer a specific shopping request. Merchants need precise descriptions, inventory, sizes, prices and payment options, Craven said. Loyalty information can also affect recommendations when consumers ask AI to account for memberships or rewards.
For an SMB, the data can determine whether it makes the consideration set.
Webster illustrated the point with a shopper looking for a dress for an October wedding in Paris, asking AI to consider the destination, weather, occasion and other requirements. Craven took the example to a local Paris merchant.
If the business has accurately described a small gold dress, its location and October availability, AI could surface it for a shopper who might never encounter the merchant through conventional search.
“That helps the small businesses in Paris,” Craven said, by way of example. “The agentic world and AI has now helped you to find something you otherwise would never have found if you were just doing a standard search.”
For now, much of that opportunity remains at the discovery stage. A shopper can ask AI to find a blue sweater in a particular size and at a specified price, but having an agent independently complete that purchase from beginning to end isn’t broadly available yet.
“Consumers are using it today as just a better search, and they’re buying where they always buy,” Webster said.
The distinction creates a measurement problem. Only 23% of merchants can clearly identify both AI-driven traffic and completed purchases, while 37% can’t distinguish AI-driven traffic from other digital traffic.
Without that visibility, merchants can’t readily determine how much business AI is producing or adjust their approach to capture more of it.
“It is a different channel, and it is a channel that you have to modify how you sell [in order] to get the pickup in transactions and conversions,” Craven said.
Merchants Get More Selective About What They Build
The investment in AI comes as merchants are showing more restraint elsewhere.
Kiosk pickup, voice ordering, scan-and-go and curbside availability all became less accessible among merchants surveyed for the 2026 Global Digital Shopping Index. Merchants are concentrating instead on checkout, payment choice and fraud controls that can contribute more directly to growth, Craven said.

We’d love to be your preferred source for news.
Please add us to your preferred sources list so our news, data and interviews show up in your feed. Thanks!
Apps offer one indication of where that money is going. Sales through merchants’ own apps grew for 57% of merchants, more than any other channel measured, and apps outperform the same merchants’ websites on 11 of 14 digital payment capabilities.
“Everything is happening in the app,” Craven said, citing authorization, account verification, settlement and fraud.
Stored credentials, one-click checkout, biometrics and payment choice have also raised the standard consumers apply elsewhere. For SMBs, the issue isn’t simply offering another feature or payment method, but making it part of the same operating system.
Craven pointed to tap-to-pay. A merchant may turn a phone into a point of sale, but the transaction still needs to connect with online operations so inventory, credentials and disputes can be managed together.
Agentic commerce will put similar pressure on fraud controls.
Every fraud category measured in the study improved, but 60% of merchants remain very or extremely interested in better fraud protection. Merchants preparing for agentic transactions will have to distinguish legitimate user-directed agents from unwanted automated activity without rejecting good customers along the way.
The same data that helps merchants make that distinction has uses across the transaction. Product and inventory information can make an SMB visible to AI. Traffic and transaction information can show whether AI contributed to a purchase. Purchase records can help determine later whether a dispute represents fraud or a legitimate transaction the customer doesn’t recognize.
The broader change is occurring while merchants are still working on the checkout consumers use today. The report found that 87% of merchants said their checkout needs some improvement, while only 13% called it optimal.
That’s why Webster cautioned against allowing the attention around agents to obscure the existing customer experience.
“It really is about getting the very basic things that consumers expect when they show up to work flawlessly, every single time,” she said.
For SMBs, agentic commerce adds a new requirement to those basics. Their products must be understandable to AI before the shopper ever reaches checkout.
Watch the full interview with Visa’s Sara Craven to learn:
- How AI is changing SMB customer acquisition and what merchants need to know about agent-generated traffic.
- How apps are reshaping checkout expectations.
- Why merchants are pruning some shopping features and how fraud controls will have to accommodate transactions initiated by consumers and their agents.
For all PYMNTS AI coverage, subscribe to the daily AI newsletter.