BDLA reports slowdown in bridging activity
Q2 lending data from the Bridging & Development Lenders Association (BDLA) reported falling applications, completions and loan book values across both bridging and development finance.
Bridging applications worth £7.3bn were made in Q2, down 26.3% from Q1. Furthermore, completions totalled £1.6bn in Q2, a reduction of 15.2% compared with last quarter.
Total reported lender loan books fell by 10.6% to £10.3bn by the end of June.
Development finance activity saw lending volumes slipping to £273.5m from £276.5m in Q1.
Meanwhile, second charge completions dropped to £101.1m from £131.3m. Average loan to values (LTVs) increased to 57.66%, and the value of defaulted loans was 0.4% lower than the previous quarter.
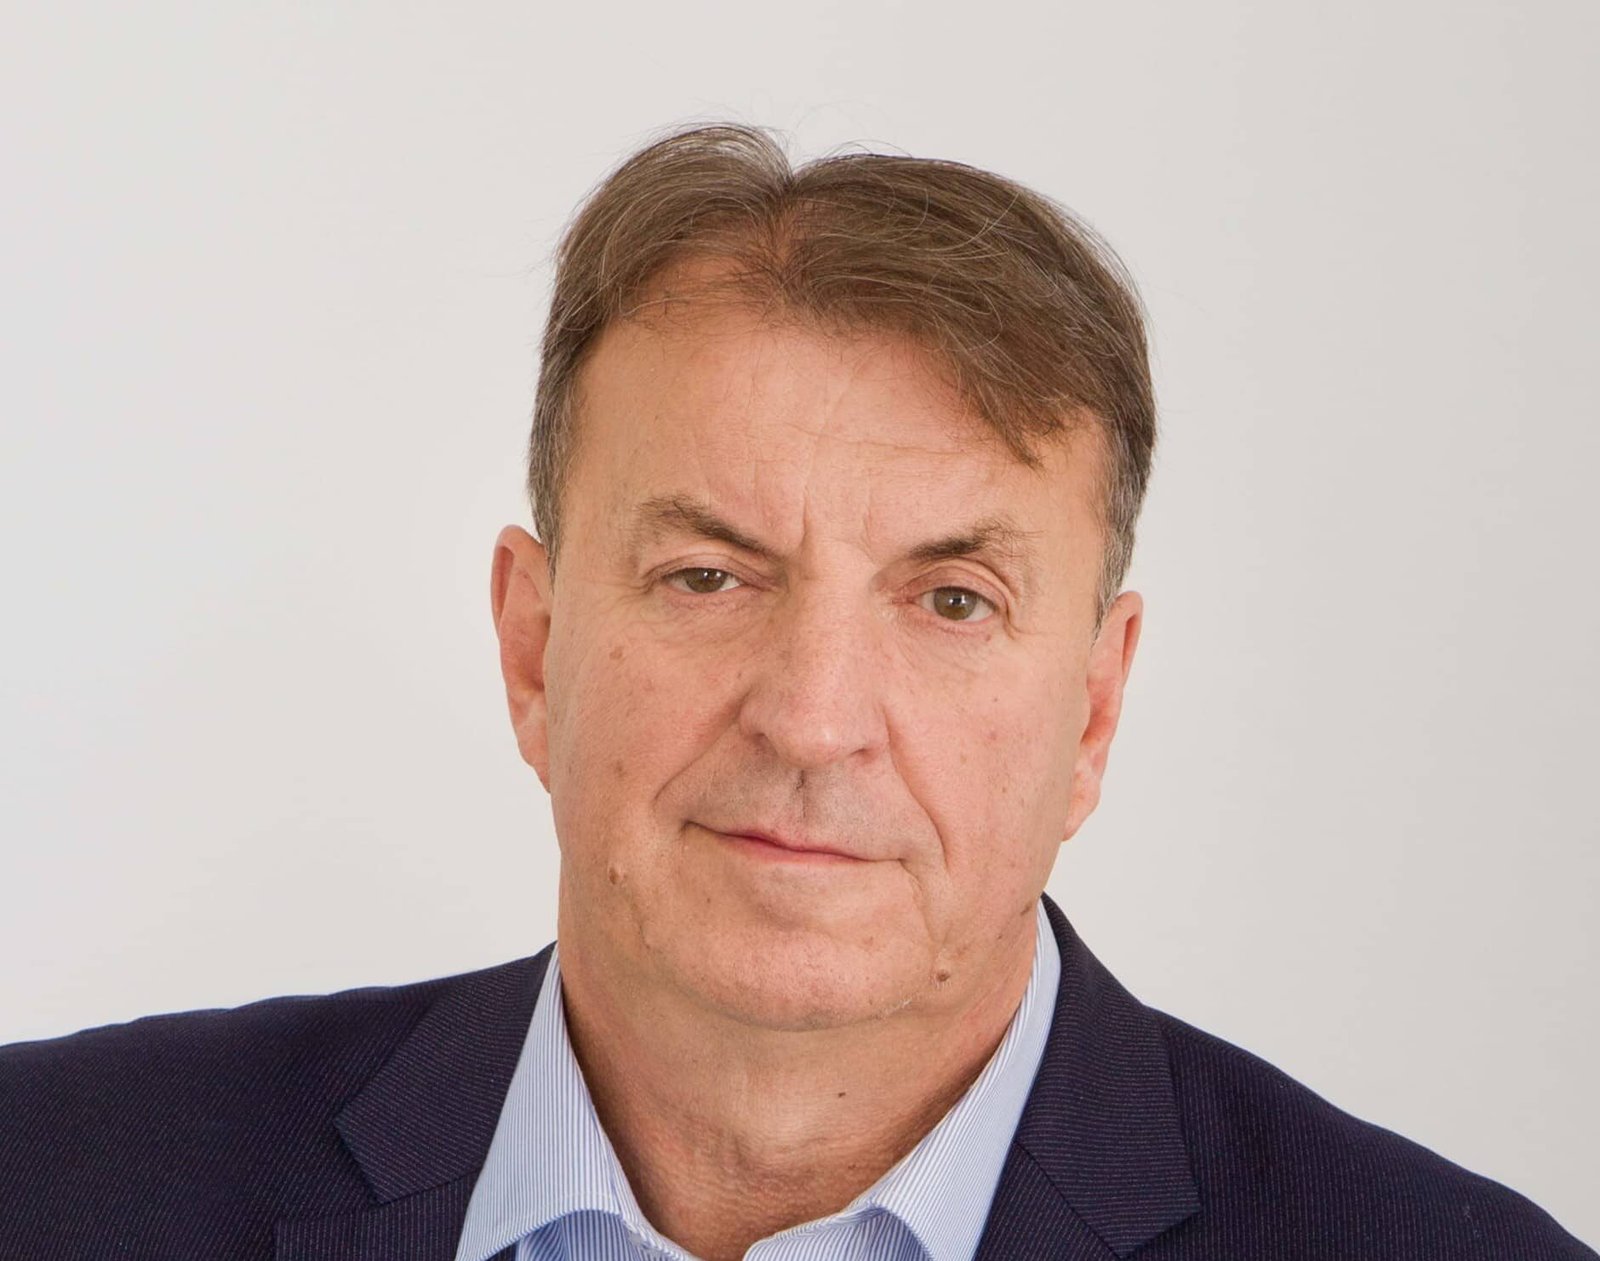
Adam Tyler (pictured), CEO of the BDLA, said bridging and development lenders were not exempt from feeling the consequences of a slower property market.
Episode 1: First-time buyers : Powered by Partnership podcast from Newcastle for Intermediaries
Sponsored by Newcastle for Intermediaries
“These figures show that the slowdown in lending activity continued into the second quarter of this year, but bridging and development lenders are not alone in experiencing a quieter market. Feedback from across the property sector is that transaction levels are subdued and deals are often protracted,” he said.
Tyler suggested that the volatility in the sector affirmed the significance of exit strategies on short-term loans.
“Where a loan is expected to be exited through a property sale, lenders need to consider not just the anticipated sale price, but how long that sale could realistically take and what alternatives are available if it does not complete within the agreed term,” he added.
Questions and concerns were raised by Tyler, who implored: “The health of the bridging and development finance market is closely connected to wider property activity, housing delivery and business confidence”.
Tyler continued: “That brings the question of housing market stimulus into a wider economic discussion.
“What’s preventing transactions and developments from progressing, is there intervention that would help and what difference would potential measures make? Understanding those barriers is central to assessing the effects on transaction activity, housing supply and affordability.”