Missed ₹431 on credit card bill, charged ₹30,000 interest; know the consequences of not making the full payment
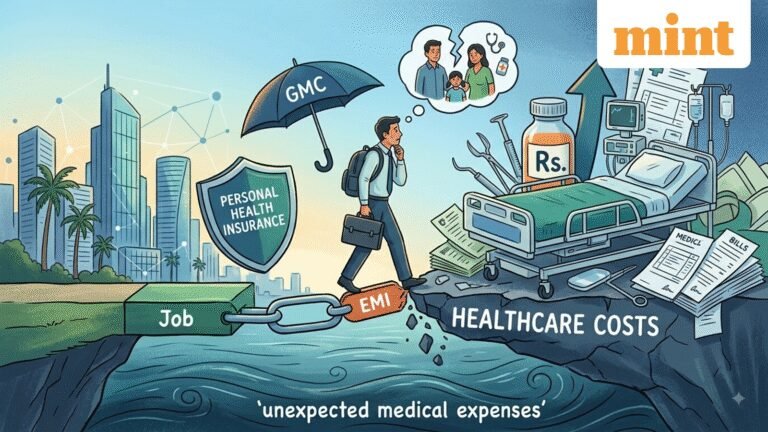
An Reddit user recently shared their experience on the social media platform, claiming that they were charged hefty finance charges after falling short on their credit card payment by just ₹431.
The incident highlights how even a small unpaid amount on a credit card bill can potentially trigger additional interest and other charges when the full outstanding is not cleared by the due date.
According to the post, the user’s total credit card bill stood at ₹4,17,770.38 and the person paid ₹4,17,339 before the due date.
Despite the small shortfall, the user said the bank subsequently levied finance charges of around ₹25,794. In addition, GST of about ₹4,643 was also charged on the finance charges, taking the total additional amount to about ₹30,437.
Disclaimer: This report is based on user-generated content from social media. Livemint has not independently verified the claims and does not endorse them.
Consequences of not clearing the full dues
The user noted that the most confusing part about the situation was that, even though they made multiple part-payments, the bank’s app did not clearly show how much of the statement balance was still outstanding.
The Reddit post has drawn attention to the importance of checking the total amount due on a credit card statement and ensuring that the entire outstanding balance is paid within the due date.
A credit card grace period is the interest-free time between the end of your billing cycle and your payment due date. So, if you don’t pay your bills by the due date, or even pay only the minimum amount due, the bank charges interest on the balance amount. This will keep adding up until you make the full payment.
In addition, fresh purchases made in the subsequent billing cycle may also lose the grace period and can start accruing interest immediately until the entire outstanding balance is cleared, according to experts.
“Credit cards offer an interest-free period only when the full outstanding amount is cleared by the due date. Even a small unpaid balance converts the account into revolving credit and when that happens, interest applies not only on the unpaid amount but also on new purchases from the transaction date,” according to Adhil Shetty, chief executive officer (CEO) of BankBazaar.
Why paying minimum due is not enough
Paying only the minimum amount due can help you avoid late payment charges, but the unpaid balance may continue to attract finance charges. This can significantly increase the cost of carrying the outstanding balance, as illustrated by the Reddit user’s experience.
For most credit cards, the finance charges can go up to 42% per annum, according to Santosh Agarwal, the CEO of Paisabazaar. However, this can happen only if the credit card holder does not understand the concept of compounding interest.
“When there is an unpaid balance in your account, all new purchases become ineligible for the interest-free period, which means they will incur finance charges from the first day,” she said.
This can cause the outstanding balance to grow rapidly, particularly when a cardholder continues making only the minimum payment over several billing cycles. Such a situation can also lead to a debt trap if you use other credit cards to make payments for an old credit card bill and vice versa.