Expectation vs reality: Why you should not assume 20%+ equity returns—what Nifty 500 historical data reveals
When equity markets deliver strong returns, it can be easy for investors to start treating those gains as a new baseline. But history suggests that very high returns are not what investors experience most often.
In an X post, Niranjan Avasthi, President at Edelweiss Asset Management, highlighted the importance of keeping return expectations realistic. “When markets deliver unusually strong returns, it is tempting to treat those outcomes as the new normal,” he noted.
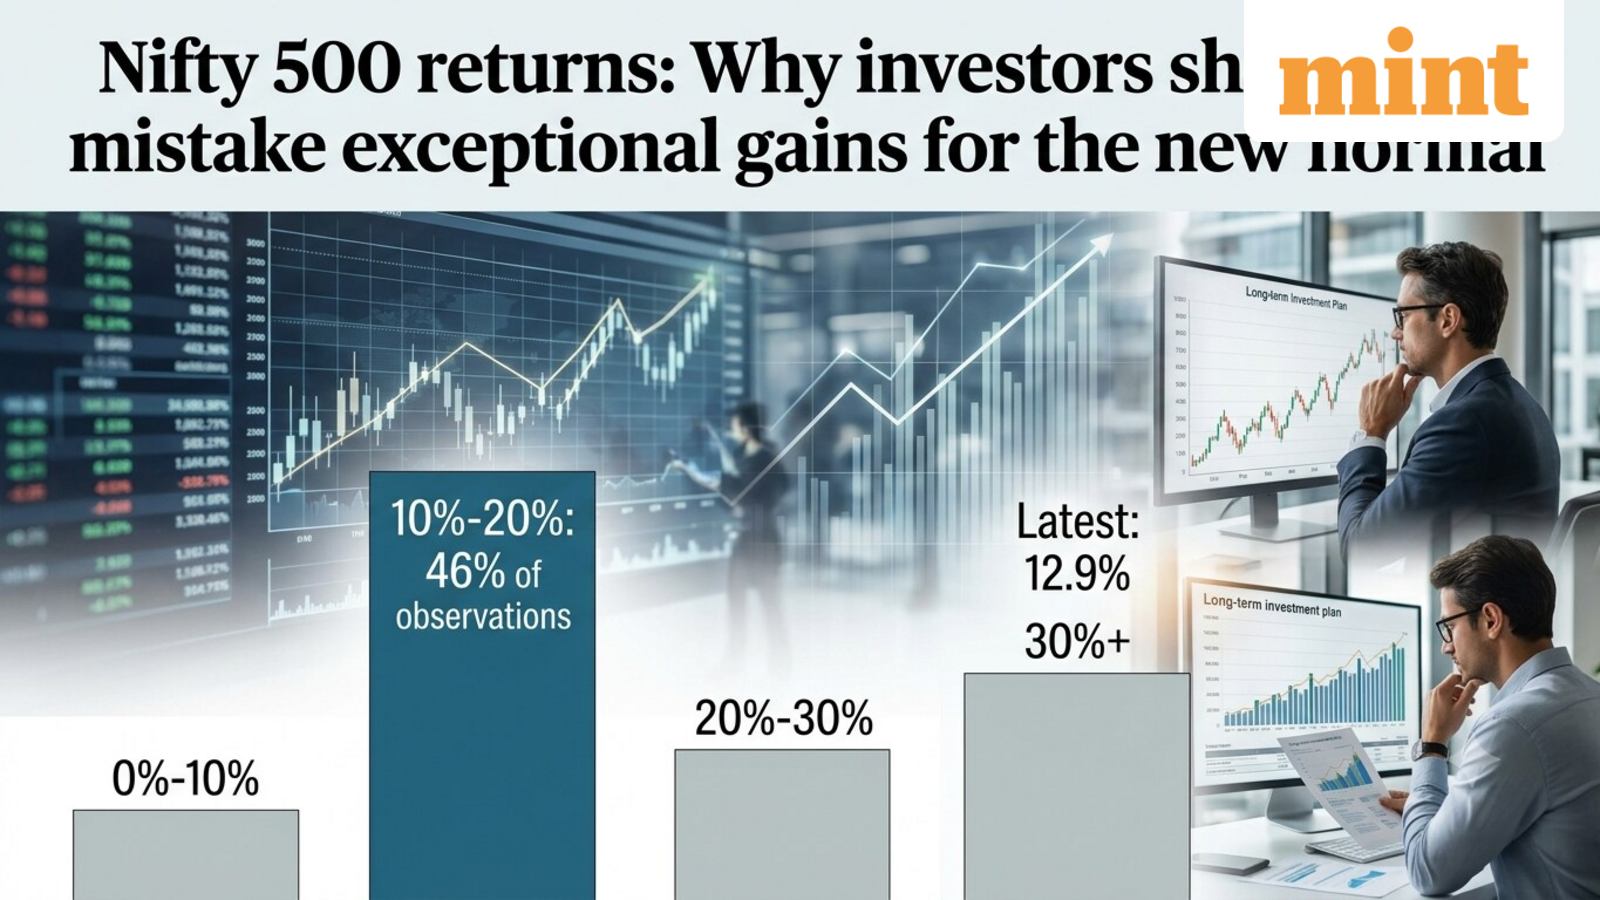
Data reveals that across 258 three-year rolling return observations for the Nifty 500 TRI since 2005, the most common outcome was a CAGR of 10%-20%. This range accounted for 119 observations, or 46% of the total.
What does a three-year rolling return mean?
A three-year rolling return measures the annualised return earned over every possible three-year period within the data set, with the observation moving forward month by month.
For example, one observation would measure the annualised return from January 2005 to January 2008, the next from February 2005 to February 2008, and so on. This gives investors a much broader picture of the range of outcomes than simply looking at the Nifty 500’s return over one fixed three-year period.
What has been the most common three-year return range?
The data shows that a three-year CAGR between 10% and 20% was the most frequently observed outcome.
“Across 258 monthly observations of rolling 3-year CAGR returns since 2005 for the Nifty 500, the most common outcome was a return between 10% and 20%. This range occurred 119 times, i.e., 46% of all observations, making it the clearest centre of gravity in the data,” Avasthi mentioned.
“The latest rolling three-year CAGR is 12.9%, broadly within this dominant band. This does not indicate weak performance; rather, it is consistent with the return experience investors have encountered most frequently,” he added.
This does not mean investors will earn 10%-20% in every three-year period. Equity returns can vary sharply depending on when an investor enters and exits the market.
How often did the Nifty 500 deliver returns above 20%?
The data shows that strong three-year outcomes were relatively less frequent. “Higher-return periods do occur, but they should be viewed as a bonus rather than the baseline,” he noted.
He added, “Returns between 20% and 30% appeared in 32 observations, or 12% of the sample. Returns above 30% occurred 41 times, representing 16%. These phases can materially accelerate wealth creation, but their relative rarity makes them unsuitable as permanent assumptions for financial plans or investor expectations.”
At the other end, 13 observations, or 5%, recorded returns between -10% and 0%. Another 53 observations, or 21%, delivered returns between 0% and 10%. No three-year rolling period in the dataset recorded a CAGR below -10%.
Should investors plan around the average return?
Not necessarily.
“The historical average is 17.5%, while the median is 15.0%, reinforcing that mid-teen expectations are a more practical planning anchor than exceptional bull-market outcomes,” he noted.
According to Avasthi, this suggests that investors may find mid-teen return expectations more practical for financial planning than assuming that exceptionally strong market returns will continue.
He summed up the point: “Equity investing rewards patience, but expectations matter. Investors who plan around sustainable mid-teen outcomes are less likely to be disappointed by normal market cycles or tempted to chase risk after unusually strong periods.”
“Mid-teen returns are the planning anchor; exceptional returns are like bonus,” he noted.
Disclaimer: This is purely for educational/informational purposes and should not be taken as any sort of investment advice. Always consult a SEBI-registered advisor before making any investment decisions.