Taxpayer left ₹38 lakh income out of ITR, paid ₹19.89 lakh tax later; why ITAT cancelled the ₹23.94 lakh penalty
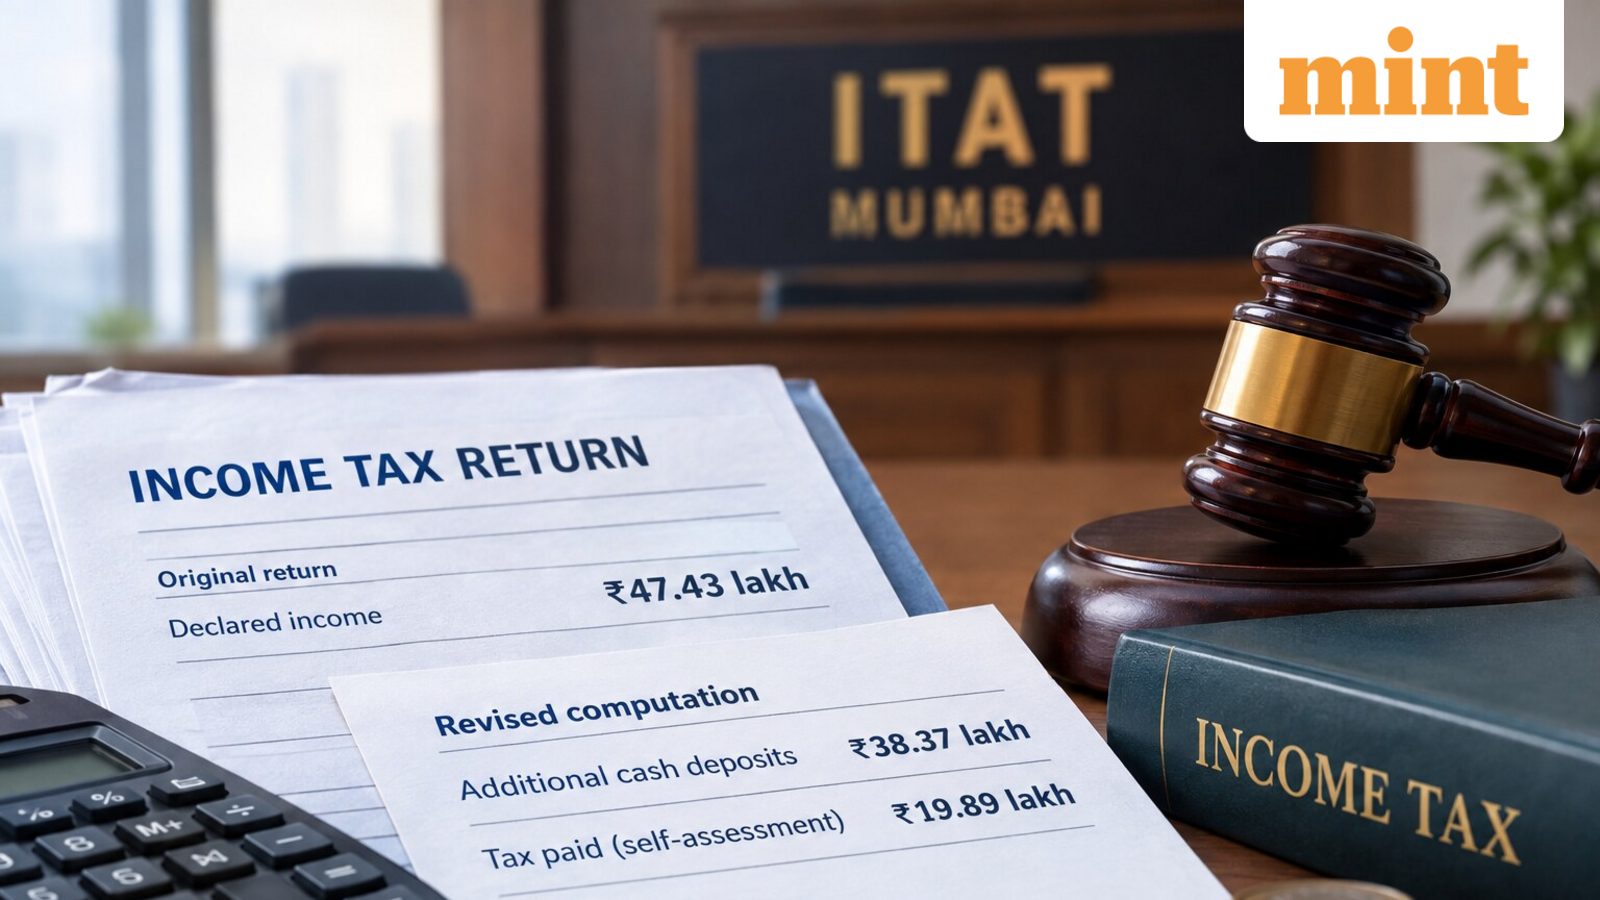
A Mumbai ITAT ruling has provided relief to a taxpayer who had omitted ₹38.37 lakh of cash deposits from his original ITR but disclosed the amount during assessment proceedings and paid ₹19.89 lakh in tax.
The tribunal held that simply describing the omission as “misreporting” was not enough to justify the 200% penalty under section 270A of the Income-tax Act.
The order was pronounced on 10 September 2026 in Manoj Kumar Divakaran v. DCIT, Circle 42(2)(1), Mumbai, ITA No. 1297/Mum/2026 for AY 2022-23
Taxpayer originally declared ₹47.4 lakh income
The case concerns Manoj Kumar Divakaran and assessment year 2022-23. He had filed his original income-tax return on 5 July 2022, declaring income of ₹47.43 lakh.
His return was subsequently selected for scrutiny. During the assessment proceedings, the taxpayer filed a revised computation on 25 November 2023. This included cash deposits totalling ₹38.37 lakh in two bank accounts. The taxpayer told the authorities that the deposits had been left out because of a communication gap with his tax adviser.
He also paid ₹19.89 lakh as self-assessment tax on the revised computation.
The Assessing Officer later completed the assessment on 26 March 2024 and treated the ₹38.37 lakh as income from other sources. The taxpayer did not challenge this addition.
However, the tax department also initiated penalty proceedings under section 270A, treating the income as having been under-reported as a consequence of misreporting.
Why was a ₹23.94 lakh penalty imposed?
The distinction between under-reporting and misreporting was important because the latter can attract a penalty of 200% of the tax payable on the under-reported income.
The Assessing Officer ultimately imposed a penalty of ₹23.94 lakh. The taxpayer then appealed against the penalty.
The taxpayer had also applied for immunity from penalty under section 270AA on 30 April 2024. According to the tribunal’s order, he had paid the tax and interest and had not filed an appeal against the underlying assessment.
The application, however, was not accepted by the Assessing Officer. The penalty was maintained on the ground that the case involved misreporting.
ITAT says ‘misreporting’ cannot simply be used as a label
The Mumbai bench of the Income Tax Appellate Tribunal examined whether the circumstances actually amounted to misreporting under section 270A.
The tribunal noted that the taxpayer had disclosed the ₹38.37 lakh in his revised computation during the assessment proceedings and paid the resulting tax. The revised computation was not rejected by the Assessing Officer.
The tribunal also referred to the fact that the penalty proceedings did not specify which particular limb of section 270A(9), which sets out circumstances constituting misreporting, applied to the taxpayer’s case.
It relied on the Delhi High Court’s decision in Prem Brothers Infrastructure LLP v. NFAC, where the court had held that merely referring to “misreporting” without identifying the applicable limb and explaining how its requirements were satisfied was insufficient.
The Mumbai ITAT also referred to an earlier tribunal decision involving a revised computation where the additional income had been accepted by the Assessing Officer. In that case too, the tribunal had held that the circumstances could amount to under-reporting but not under-reporting as a consequence of misreporting.
₹23.94 lakh penalty deleted
The Mumbai ITAT ultimately allowed Divakaran’s appeal and deleted the penalty.
The tribunal held that there was no justification for treating the income as under-reported in consequence of misreporting on the facts before it. It also held that the taxpayer was entitled to immunity from penalty.
Importantly, the tribunal did not delete the underlying ₹38.37 lakh income addition. The taxpayer had accepted the assessment and had not challenged that addition. The relief was specifically against the ₹23.94 lakh penalty.