Post-crisis mortgage rules are locking creditworthy buyers out
The numbers tell a blunt story. In 2000, lenders originated roughly 1.08 million home purchase mortgages to applicants with credit scores between 601 and 660.
By 2024, that figure had plunged to 293,000, a 73% drop that Pew says cannot be explained by improvements in the broader population’s credit profile.
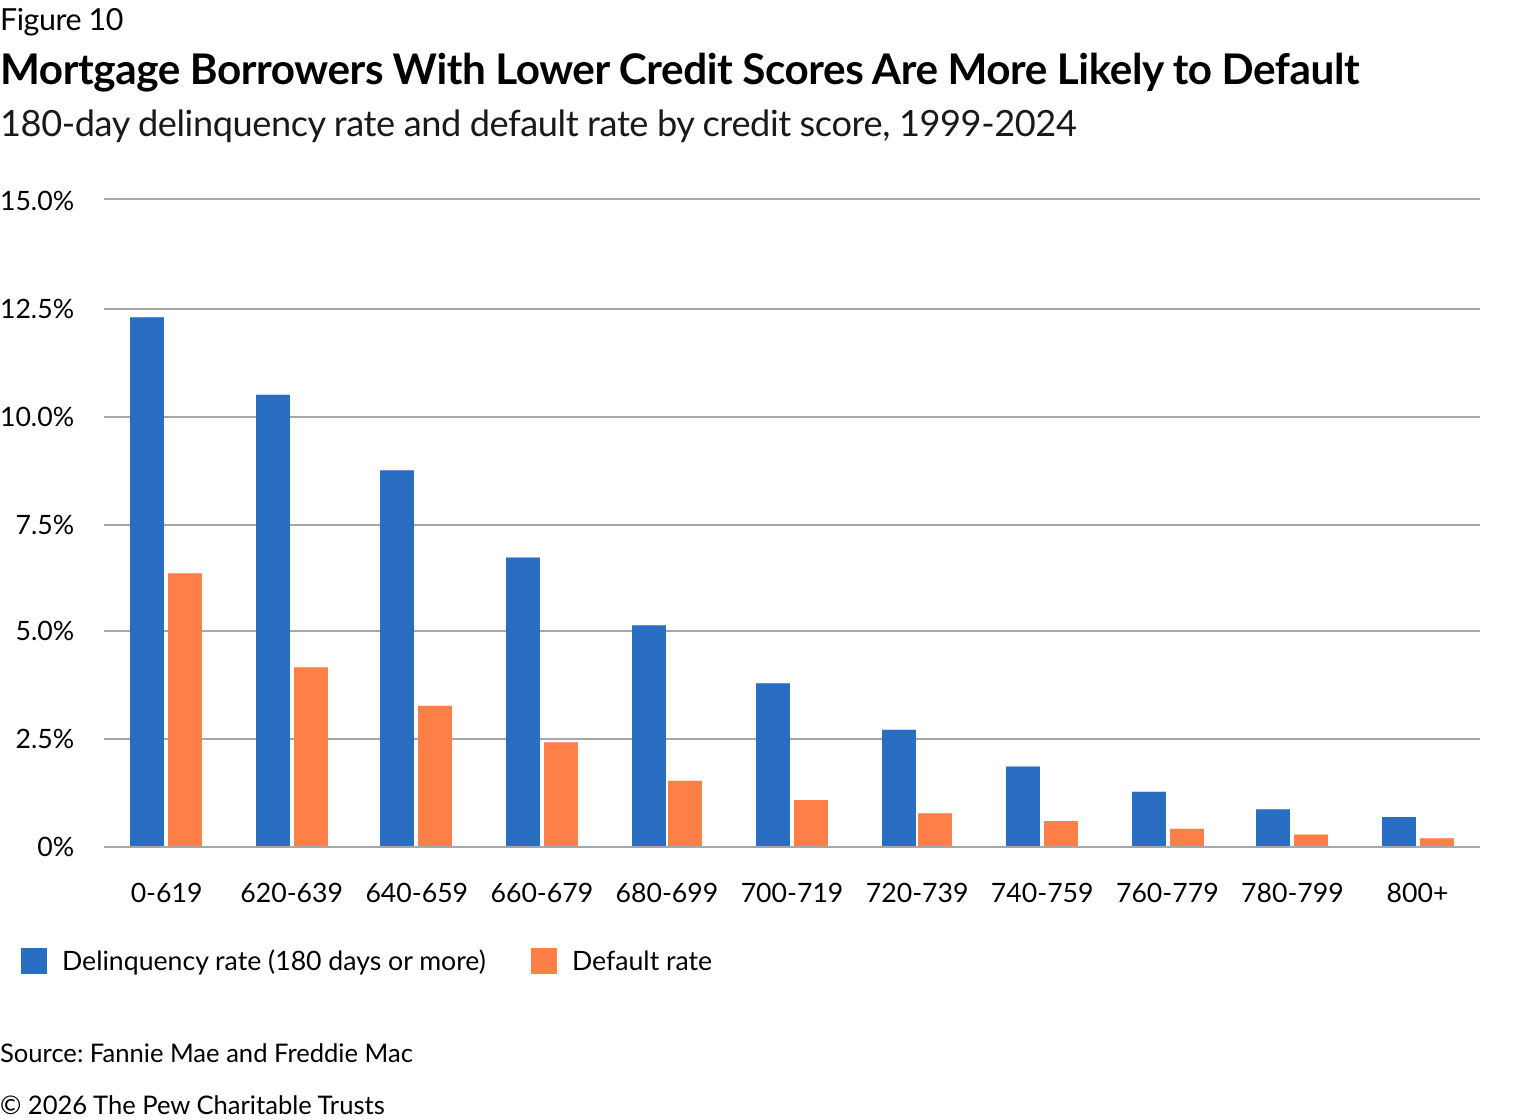
From 2005 to 2024, the share of originations for borrowers in the 600-699 credit score range fell by 13.3 percentage points to 22.3%, while borrowers above 700 gained 24.9 percentage points of origination share.
Who gets left behind
The excluded borrowers skew young, lower-income, and non-white. Pew data shows 37.5% of Black mortgage borrowers and 26.9% of Hispanic borrowers held credit scores in the 600-699 range, as did 33.5% of buyers under 25 and 26.8% of first-time purchasers.