Tax breaks, refinancing support dominate financial sector’s Budget pitch | Finance News
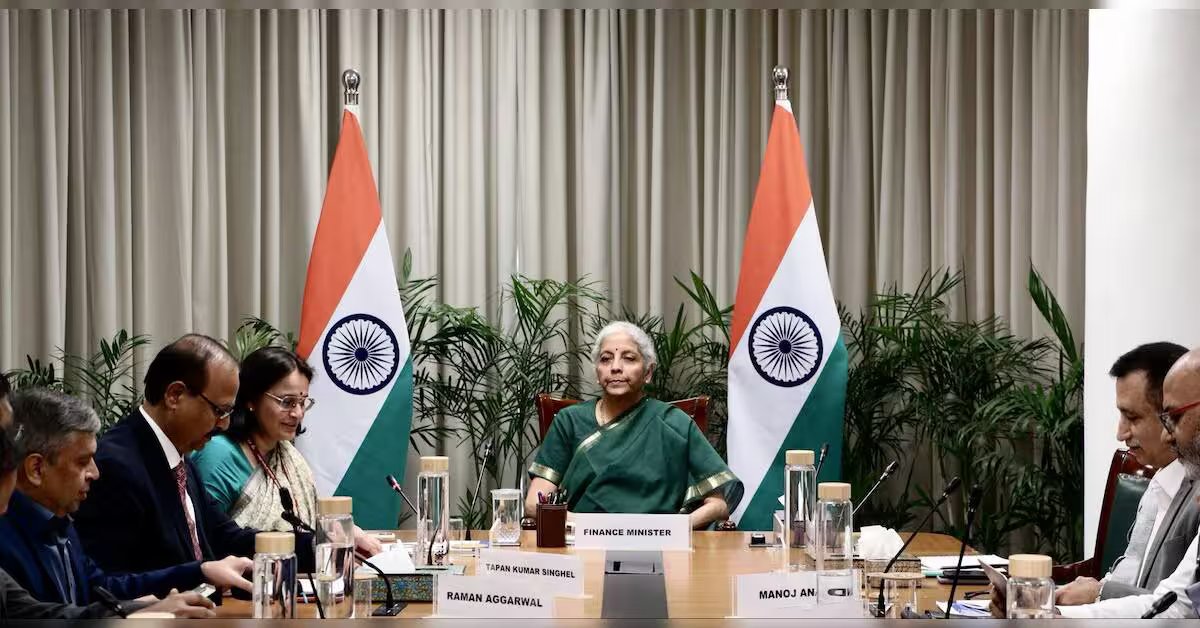
Capital market and financial sector stakeholders on Wednesday sought a series of tax and policy changes at a pre-Budget meeting with Finance Minister Nirmala Sitharaman. These included the restoration of indexation benefits on debt mutual funds (MFs), rationalisation of taxation for alternative investment funds (AIFs), and dedicated refinancing support for non-banking financial companies (NBFCs) and microfinance institutions.
Representatives of the AIF industry association, the Association of Mutual Funds in India, the real estate investment trusts industry body, online bond platforms, and market infrastructure institutions attended the meeting. Representatives of the Finance Industry Development Council (FIDC), the General Insurance Council, and microfinance self-regulatory organisations were also present.
Sources said MF industry representatives reiterated their suggestions to boost participation in debt MFs, including a rollback of the earlier changes that removed indexation benefits on debt schemes. Industry participants said the removal of these benefits had created challenges for debt MFs and that restoring them could help deepen the corporate debt segment.
The AIF industry, meanwhile, sought a relaxation of the taxation framework for Category III AIFs and private credit funds.
FIDC, which represents NBFCs, has sought the creation of a dedicated refinancing fund through the Small Industries Development Bank of India (Sidbi), using the shortfall in banks’ priority sector lending (PSL) targets. The proposed fund would provide refinancing support to NBFCs, particularly small and mid-sized players.
FIDC has proposed that funds arising from the PSL shortfall be transferred to a dedicated fund, with Sidbi as the nodal agency, to refinance NBFCs. The funds received by NBFCs through this mechanism would be used exclusively for on-lending to priority sectors, including micro, small and medium enterprises (MSMEs), small businesses, and agriculture-related activities. Green financing segments, including electric vehicles, rooftop solar, and biogas plants, have also been proposed for inclusion.
The industry body has also sought an exemption for NBFCs, including housing finance companies, from tax deducted at source (TDS) on interest payments under Section 194A of the Income-Tax Act, on a par with banks, insurance companies, and public financial institutions. It has argued that the existing TDS requirement increases the compliance burden on borrowers and NBFCs, blocks working capital and creates complications in co-lending arrangements.
FIDC has also sought a reduction in the minimum loan threshold for NBFCs to invoke the Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest (Sarfaesi) Act from ₹20 lakh to ₹1 lakh, bringing it in line with the threshold applicable to banks. It has also sought access to debt recovery tribunals (DRTs) for NBFCs to initiate recovery proceedings.
Separately, microfinance industry representatives have sought an extension of the credit guarantee scheme by another year, particularly for smaller and mid-sized microfinance companies, sources said. They have also sought a dedicated fund to help microfinance companies access funds at lower interest rates, along with additional support for raising equity capital.
A day earlier, stockbrokers and other market participants met officials of the Central Board of Direct Taxes, seeking the withdrawal of long-term capital gains (LTCG) tax on equity investments, the removal of securities transaction tax (STT) on delivery-based cash market transactions, and the revival of certain rebates on business income under Section 88E, according to people familiar with the developments.
The Association of NSE Members of India, a stockbrokers’ association, argued that STT was introduced in 2004 as a substitute for LTCG tax, but investors are now required to pay both.
It has also sought that intraday cash trades be treated as business income rather than speculative income. Other demands include allowing business losses to be carried forward for eight years instead of four and permitting them to be set off against income other than salary.
Section 88E provided a rebate equivalent to the STT paid on business income arising from taxable securities transactions. The provision reduced the income tax payable by those engaged in securities trading and was not a general rebate available to all investors. The rebate was effectively withdrawn from Assessment Year 2009-10.
In the Union Budget 2024-25, the government raised the LTCG tax rate on equity investments from 10 per cent to 12.5 per cent on gains exceeding ₹1.25 lakh, without indexation benefits. In the cash segment, STT of 0.1 per cent is levied on both the purchase and sale of equity shares.