How lenders can improve construction loan readiness

- Key Insight: Uncover how strong-credit borrowers can still present weak residential construction proposals.
- What’s at Stake: Lenders risk holding incomplete collateral and facing severe refinancing exposure.
Overview bullets generated by AI with editorial review.
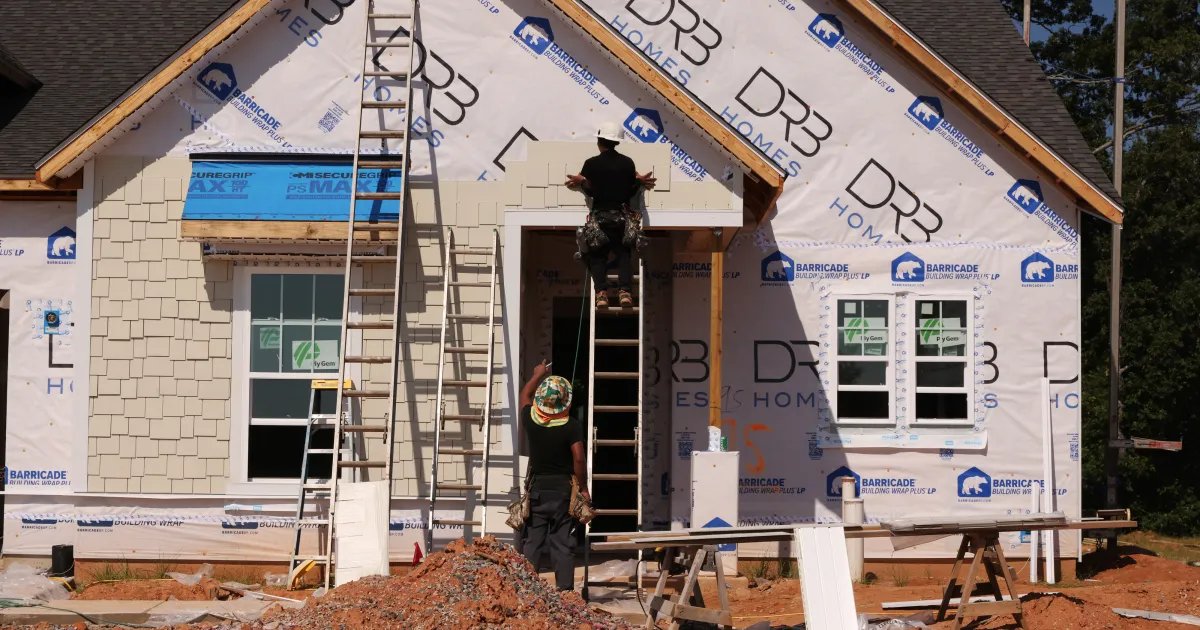
Residential construction loans expose lenders to risks that conventional purchase mortgages do not. Unlike typical mortgages, the collateral is not yet complete, the final cost remains subject to change, and disbursements depend on work completed after closing. A borrower with strong credit may still present a weak construction proposal.