No “Yeah Buts” in Today’s CPI. It’s All Bad For Bonds
No “Yeah Buts” in Today’s CPI. It’s All Bad For Bonds
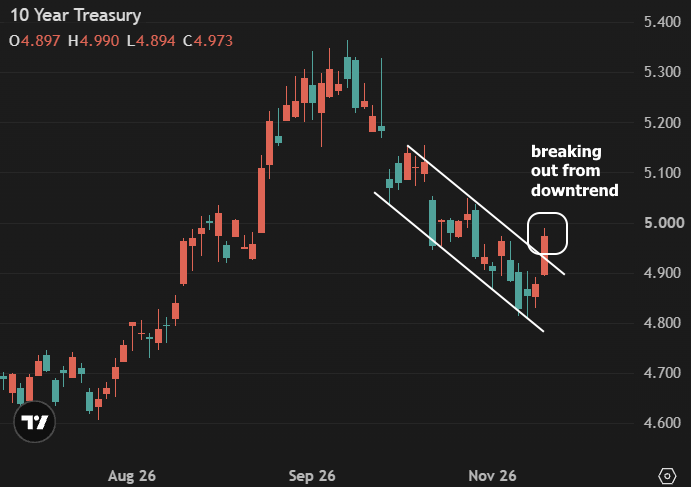
Some inflation reports have counterpoints even if they appear high at first glance. This one is just all-around not great for bonds. It would be a genuine surprise to see a meaningful reversal from this morning’s weakness without a major, unexpected news headline or massive stock sell-off.
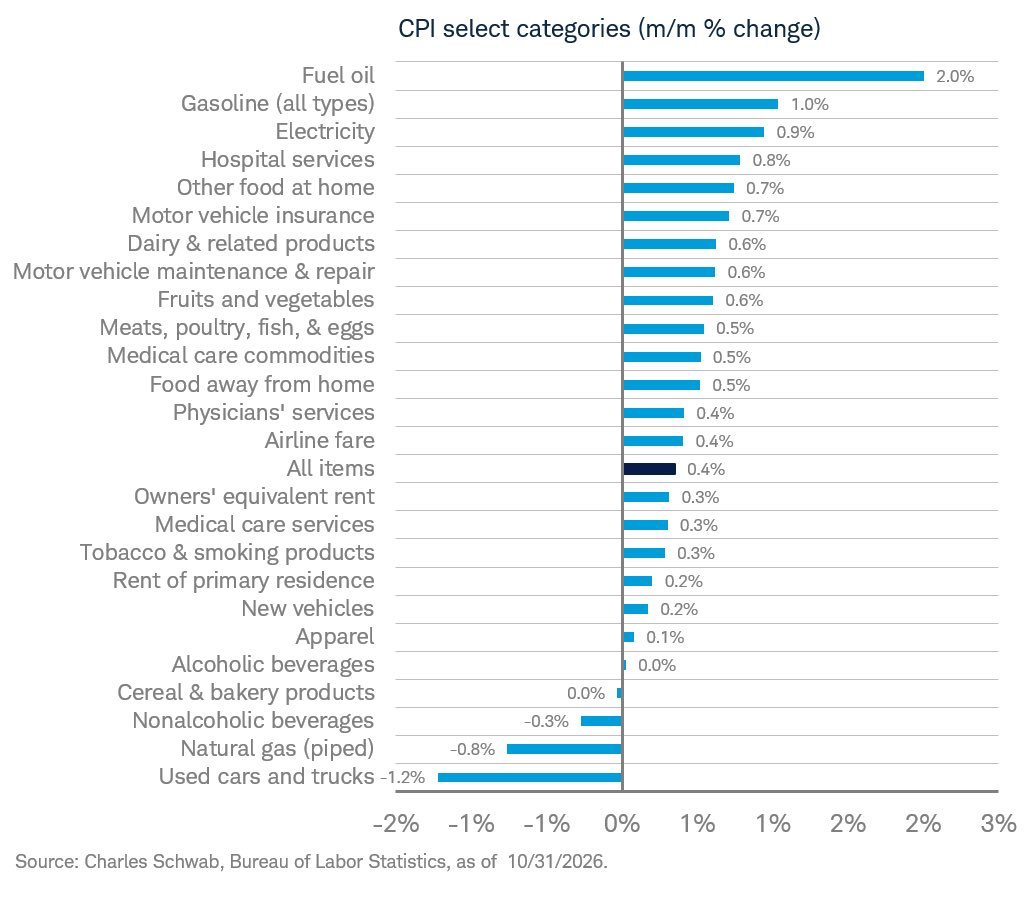
Really the only way someone could try to find a silver lining would be to say that month-over-month inflation moved a hair lower in a few key categories, but considering last month’s report saw very high readings in those categories, that silver might actually be a lightning bolt. As a reminder, there is no y/y CPI number today because of last year’s gov shutdown. The asterisk below denotes an interpolated baseline from Sept/Nov 2025.
- m/m Core CPI : .296 vs 0.22 f’cast
- y/y Core CPI*: 2.8 vs 2.7 f’cast, 2.6 prev
- Supercore: : .399%
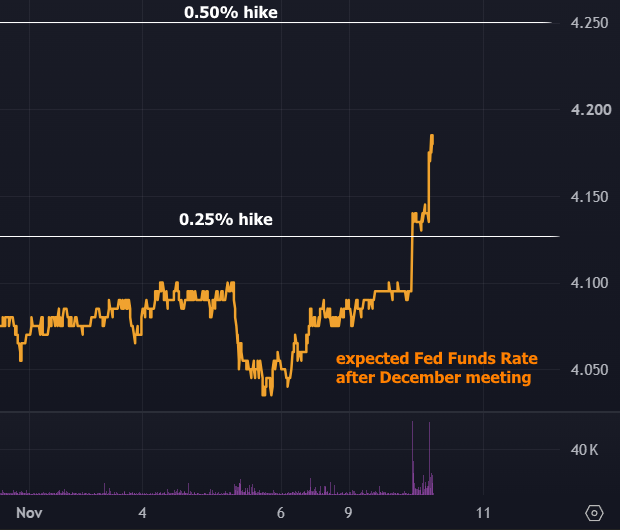
The bond market hit was immediate. As expected, shorter-term yields are hit hardest as they’re the most closely related to Fed Funds Rate expectations. December’s expected rate shot sharply higher in 2 phases. The first came before the data when Fed’s Waller (not Warsh) said they Fed should consider a 50bp hike if core CPI came it at 0.3% or higher. The second phase was in response to CPI itself. Markets are now pricing in a bit more than one full rate hike in December.