5 key lessons from Your Money or Your Life by Vicki Robin: How to achieve financial freedom while maximising your income
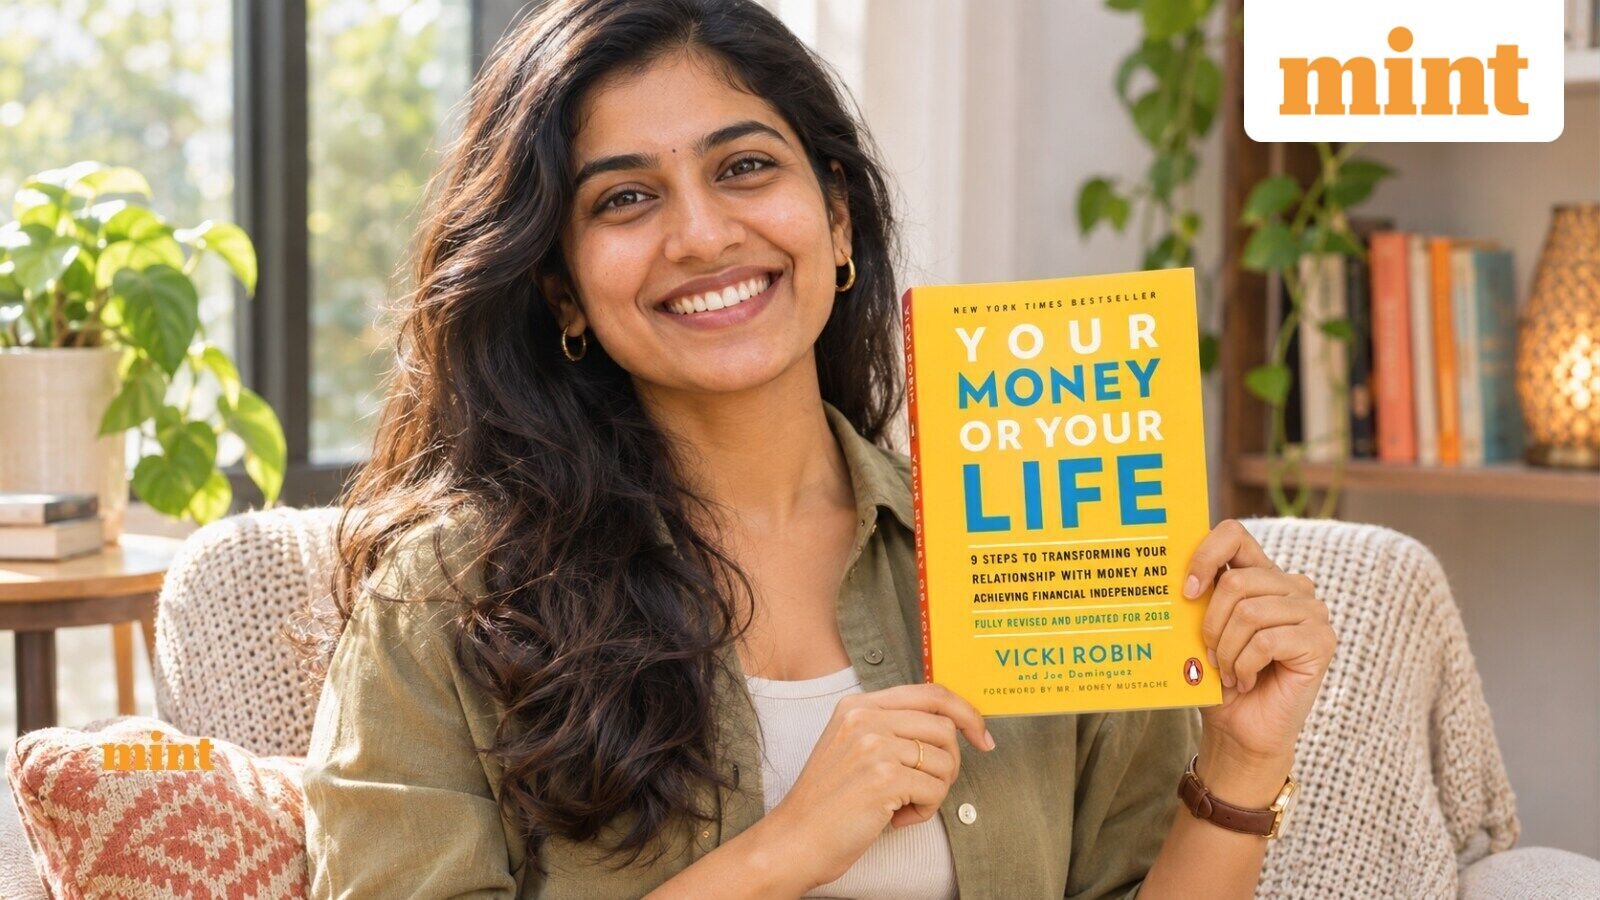
“Your Money or Your Life” offers a clear programme for financial independence. Vicki Robin wrote it with Joe Dominguez. Its big idea is simple. Money is something you trade your life energy for. Here are five lessons from the book.
Know what your pay really costs you
The book asks how much life energy you trade for each rupee or dollar. Most people divide pay by hours worked. The authors say this is too simple. Be ready to be surprised. Add the time and money your job demands.
Think of commuting, work clothes and meals bought because you are busy. Add the hours you need to unwind and the holidays you take to recover. Subtract these costs from your pay. The result is your “real hourly wage.”
Track every cent and ask three questions
The book asks you to total your monthly spending. Then convert each category into hours of life energy. Next, ask three questions about each one.
Did I get fulfilment in proportion to the life energy spent? Does this match my values and purpose? How would it change if I did not have to work for money? The authors call this the heart of the programme.
Decide what “enough” means
The book says “enough” is not bare survival. It is the exact amount that gives fulfilment without excess. Many people define enough as “more than I have now.” That keeps them feeling poor. The authors say your real enough may be smaller and closer than you think.
Maximise income, with integrity
The book asks you to earn the highest pay consistent with your health and integrity. The authors say this is not greed. It is about freedom. Suppose enough is $2,500 a month. At $25 an hour, you must work 100 hours. At $50 an hour, you could work 50 hours or save half your income.
The book blames passive attitudes for low pay. It gives two examples. Carpenter Ted Y. bid his jobs at much higher rates. Clients paid it, his hours fell, and his income rose.
Accountant Maddy C. found her real hourly wage was only $7.50 from a $90 fee. She raised rates by 23% and limited the number of clients and the number of hours. The book also says investing is a job. Ask what your real hourly wage is there too.
Aim for the crossover point
The book gives a monthly formula. Multiply your capital by the long-term interest rate. Divide by 12. The result is your monthly investment income. Plot it on a wall chart beside your expenses. When the investment line crosses the expense line, you reach financial independence.
The book uses 4% only as an example. It is not a promise. At that rate, you need 25 times your yearly expenses. Yearly spending of $36,000 needs $900,000.
Compound interest helps. At 4%, $100 doubles in 18 years. The book suggests three pillars. These are capital, a cushion of six months’ expenses, and a cache of surplus funds.
Disclaimer: This article is general information, not financial advice.