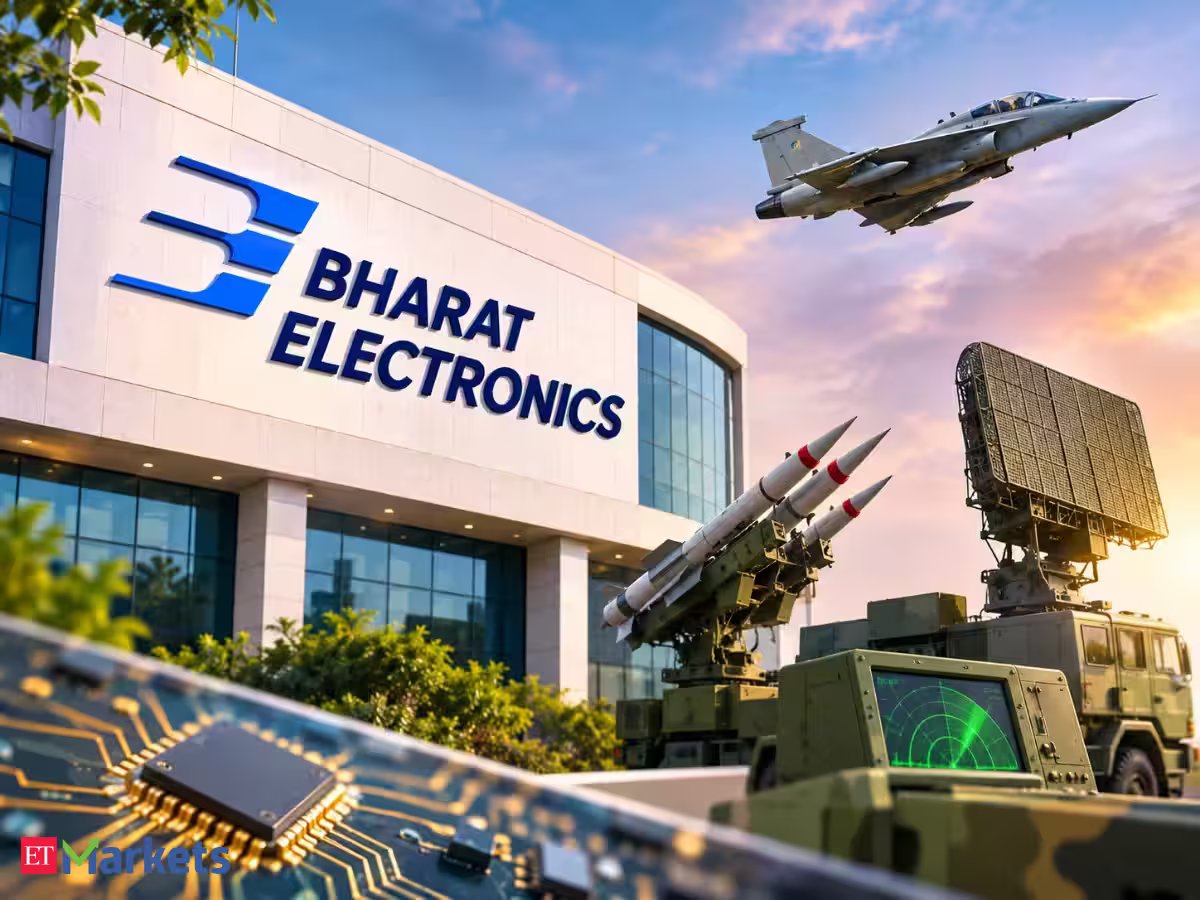
Bharat Electronics shares gain 3% as Motilal raises target price after Q2; Elara Capital upgrades to Buy
The upgrades come after the company’s analyst call on Tuesday, while the results were declared last week. Bharat Electronics reiterated its FY27 guidance, targeting 15% revenue growth, an EBITDA margin of 28% and order inflows of more than Rs 55,000 crore, including the QRSAM programme. The company plans to spend over Rs 2,200 crore on research and development and Rs 1,200 crore on capital expenditure during the year. It also expects to maintain a business mix of 90% defence and 10% non-defence.
Buy, sell or hold the stock?
Jefferies, with a target price of Rs 490, forecasts an upside of 30% from current levels. Management reaffirmed its confidence in achieving revenue growth of more than 15% in FY27, while indicating scope for an upside surprise given the 26% year-on-year growth recorded in the first half. Jefferies has largely retained its earnings per share estimates for FY28-FY30. The brokerage noted that indigenisation and economies of scale drove margin improvement in FY25 and FY26, and expects these factors to continue supporting margins over the medium term.
Elara Capital has upgraded Bharat Electronics to Buy from Accumulate, while setting a target price of Rs 465 per share (22.5% upside). The upgrade reflects expectations of healthy sales growth, margin expansion and potential order inflows.
The company reported a 27% year-on-year increase in sales to Rs 7,330 crore, which was 13% above estimates. EBITDA came in at Rs 2,040 crore, beating expectations by 15%.

Elara said Bharat Electronics’ FY27 order inflow guidance of Rs 55,000 crore, including the QRSAM programme, remains unchanged, although the Rs 30,000 crore QRSAM order has been delayed. The brokerage has, however, lowered its target price to Rs 465 from Rs 480 after reducing its valuation multiple. A slowdown in defence spending and delays in large orders remain key risks.
Motilal Oswal has raised its target price on Bharat Electronics to Rs 540 per share, implying an upside of 42% from the last closing price.The company’s order book stood at Rs 68,700 crore as of October 1, 2026, with around 90% comprising defence programmes and the remainder coming from non-defence businesses. The order book includes more than 300 projects, led by electronic fuzes worth Rs 4,200 crore, LCA Mk1 at Rs 3,200 crore, LRSAM at Rs 2,900 crore, BMP-2 upgrades at Rs 2,600 crore, Ashwini radar at Rs 2,500 crore, the EW suite for Mi-17 at Rs 2,200 crore and an export order worth Rs 1,700 crore. Together, these seven programmes account for around Rs 19,300 crore of the order book.
Excluding electronic fuzes, which have another six to seven years of execution remaining, most of these orders are expected to be completed over the next 3-3.5 years. Motilal Oswal expects these projects, along with other major programmes in the order book, to drive revenue during the second half of FY27.
BEL Q2 results
BEL reported a 19.8% year-on-year increase in standalone net profit to Rs 1,541 crore for the second quarter ended September 30. The company had posted a net profit of Rs 1,286 crore in the corresponding quarter of the previous fiscal year.
Operating EBITDA rose 20.4% year-on-year to Rs 2,040 crore from Rs 1,695 crore in the year-ago period. However, the operating EBITDA margin contracted by 140 basis points to 28% from 29.4% in Q2 FY26. On a consolidated basis, revenue from operations stood at Rs 7,328 crore, while net profit came in at Rs 1,540.4 crore. Consolidated net profit increased from Rs 1,287.2 crore in Q2 FY26.
Disclaimer: This article has been written by Veer Sharma, who is not a SEBI-registered Research Analyst or an Investment Adviser. Veer Sharma and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here