Rate hike kicks Canada’s housing market when it’s down
By Ari Altstedter
(Bloomberg) — The Bank of Canada raised its benchmark interest rate Wednesday in an effort to fight inflation. But for the nation’s housing market, the move is a heavy blow.
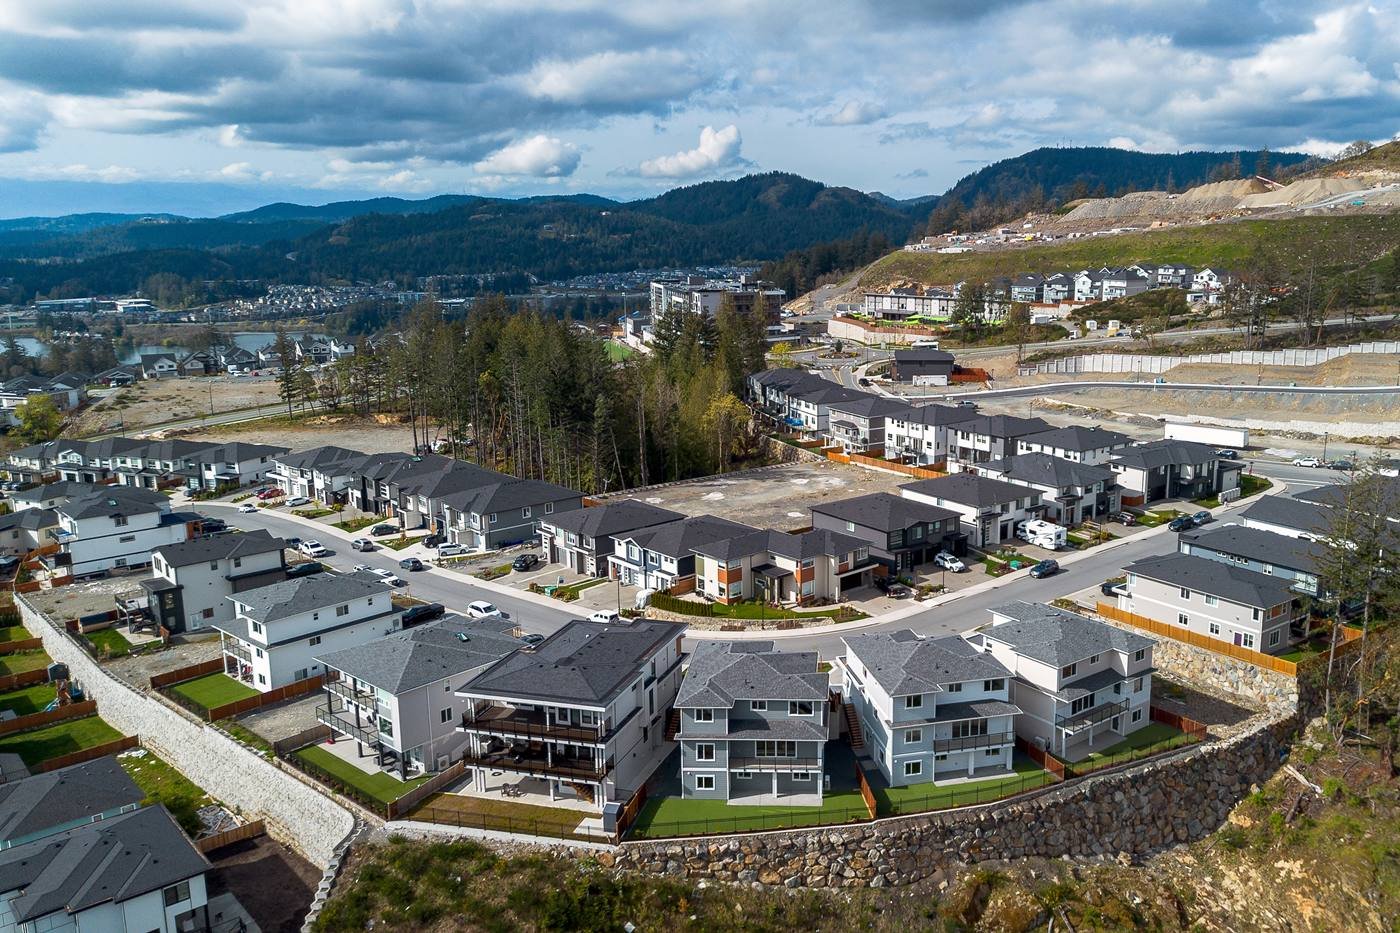
Unlike in the U.S., Canadians tend to renew their mortgages every five years or less. Variable-rate borrowing is also common. That means housing is one of the first parts of the economy affected when the central bank moves interest rates. And with Canada’s housing market cooling since 2022, the central bank’s policy move blunts hope for a recovery.
The Bank of Canada’s economic projections now show residential real estate making virtually no contribution to economic growth through 2028.
“Our outlook on housing is pretty subdued,” Senior Deputy Governor Carolyn Rogers told reporters Wednesday. “Certainly borrowing rates are currently weighing a bit on the housing market. An increase will add to that.”
Earlier this month, the Canadian Real Estate Association updated its forecast, and is now expecting a 5.2% drop in home sales from last year, with average prices changing little. The main reason was “higher fixed mortgage rates and uncertainty around how much variable rates will ultimately have to rise.”

The housing downturn that began in 2022 was preceded by a quarter-century in which prices rose steadily in Canada, becoming one of the biggest, longest housing booms in the world.
But the last stage of that boom was driven by a surge of borrowers into variable-rate mortgages. Those people will be among the first to feel this week’s rate rise. Soon to follow will be homeowners who borrowed in an era of low rates and are renewing their mortgages.
People with variable rates who didn’t make extra payments or lock into a fixed rate, and have to renew their loans soon, may receive a payment shock of roughly 50% this fall and winter, according to research from Desjardins analysts Royce Mendes and Tiago Figueiredo.
Though Canada’s portion of mortgages in arrears remains below historic levels, such shocks may nudge the rate higher, the analysts wrote in their Oct. 27 research note: “Mortgage renewals are entering a risky period.”
If housing activity plays out in line with the Bank of Canada’s projections through 2028, the country would be six years into a slump. That would rival the infamous 1990s, when national home prices took more than nine years to regain their previous high after a crash that began at the beginning of the decade.

There are similarities between Canada’s economic landscape in the 1990s and now. In both cases, the central bank was forced to raise interest rates despite a weak economy. But 35 years ago, Canada’s high public debt was a significant factor. Today, the biggest problems bedevilling the economy — inflation driven by higher oil prices and the trade war with the U.S. — are both largely outside the country’s control.
Elevated energy prices are set to affect housing costs too, as materials and equipment become more expensive, the central bank noted in its monetary policy report. Shelter services inflation is projected to rise from a little over 1% at the end of this year to about 2% in 2027 and 2028. But rent inflation is expected to ease next year.
Regardless, “there’s a number of things weighing on housing right now,” the central bank’s Rogers said Wednesday. With “the overall uncertainty in the economy, people don’t tend to make big purchase decisions like housing in that kind of an environment.”
©2026 Bloomberg L.P.
Visited 1 times, 1 visit(s) today
Bank of Canada bloomberg Dashboard real estate market
Last modified: October 29, 2026