Selling a house to clear your home loan? What an ITAT ruling on a ₹26 lakh cash advance means for property sellers
A Chennai bench of the Income Tax Appellate Tribunal (ITAT) has deleted a ₹26 lakh penalty imposed on a salaried taxpayer who accepted a cash advance for selling his house during demonetisation, ruling that his financial circumstances constituted reasonable cause for the transaction.
In its order dated 13 October 2026 in Murugesan Thulasimani v. ITO, Ward-1(6), Salem (ITA No. 859/Chny/2026), the tribunal held that the penalty under Section 271D of the Income-tax Act, 1961, was not sustainable after considering the taxpayer’s outstanding housing loan, the genuineness of the property sale and the circumstances in which he accepted the cash.
The ruling does not exempt cash property transactions from tax law. Instead, it highlights how the circumstances of an individual transaction can determine whether a penalty is justified.
Why the taxpayer was penalised ₹26 lakh
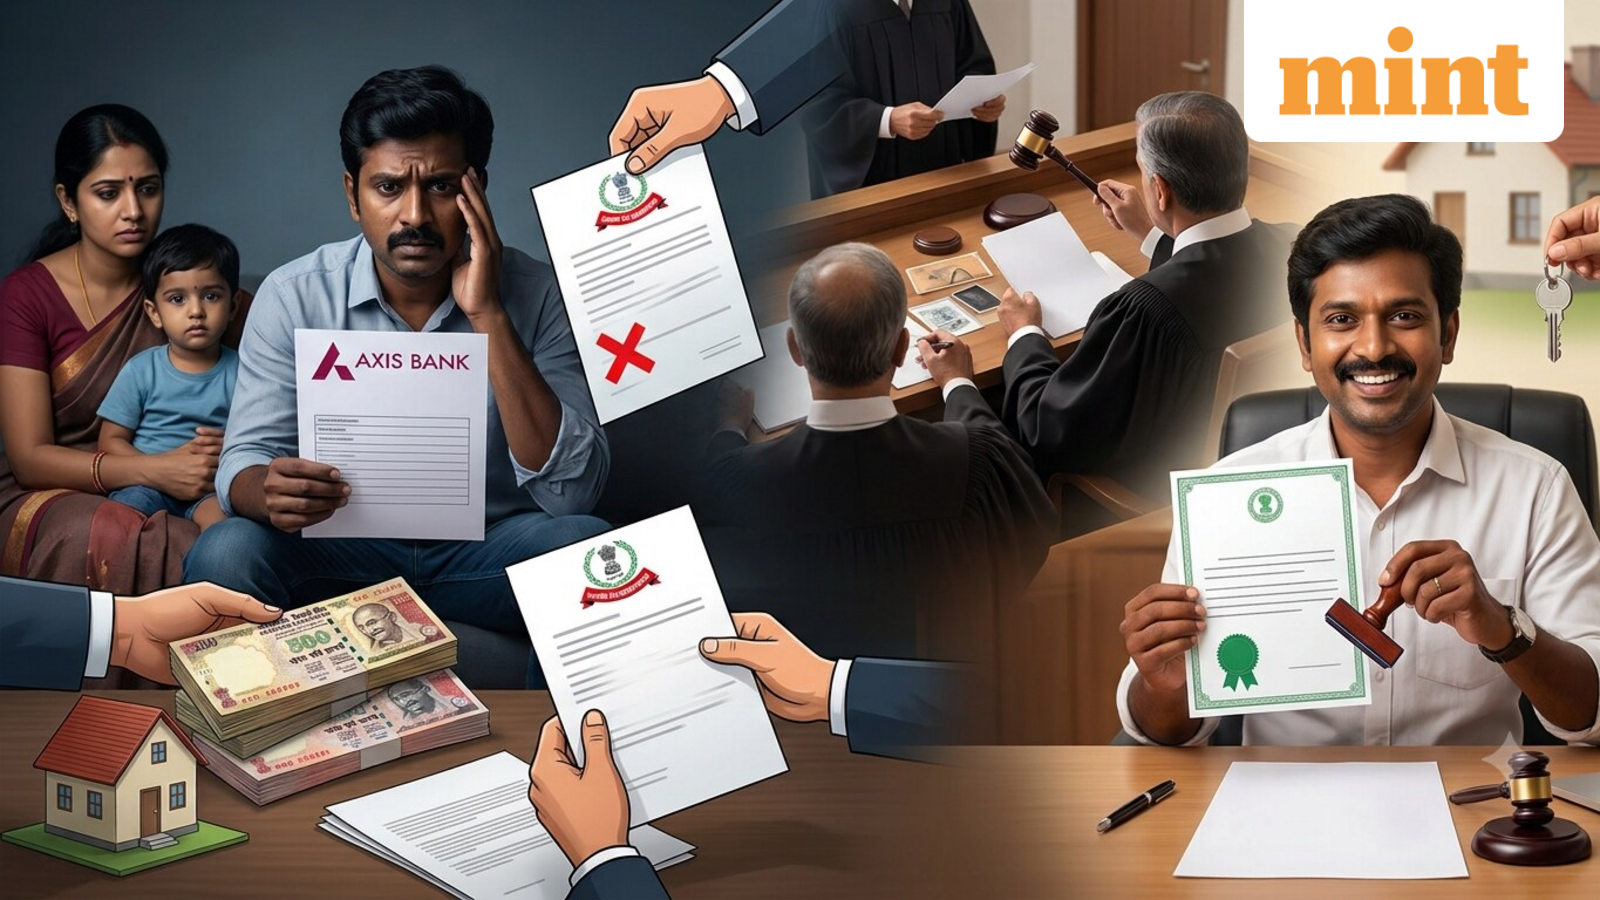
Thulasimani, a salaried employee with an annual income of ₹3.41 lakh for assessment year 2017-18, had an outstanding housing loan of ₹25.38 lakh from Axis Bank. According to the tribunal’s order, he had been trying to sell his residential property for several months to repay the loan.
On 24 November 2016, he entered into an unregistered sale agreement with a buyer and accepted an advance of ₹26 lakh in cash. The property sale was subsequently completed on 6 February 2017.
During the demonetisation period, the taxpayer deposited ₹24.13 lakh in cash into his bank account. The assessing officer questioned the source of the deposit and did not accept the explanation, although the sale transaction was confirmed by the seller and the buyer’s representative during the proceedings.
The tax department subsequently imposed a ₹26 lakh penalty under Section 271D for violating Section 269SS, which restricts the acceptance of specified sums relating to the transfer of immovable property through cash rather than prescribed banking channels.
The taxpayer challenged the penalty, but the Commissioner of Income Tax (Appeals), National Faceless Appeal Centre, upheld it on 31 January 2026. He then appealed to the tribunal.
Why ITAT ruled in the taxpayer’s favour
The tribunal examined whether the taxpayer had established reasonable cause under Section 273B, which provides relief from certain penalties where the taxpayer demonstrates reasonable cause for the failure to comply with the law.
It noted that the property transaction was genuine, had been confirmed by the parties and was subsequently completed. The outstanding housing loan and the taxpayer’s efforts to sell the property to discharge the liability were also relevant considerations.
The tribunal observed that the tax department had not produced evidence showing that the transaction was fictitious, that the taxpayer’s explanation about the loan was false, or that the transaction was designed to introduce undisclosed money or evade tax.
Considering these circumstances together, the bench concluded that the taxpayer had demonstrated a bona fide financial exigency and reasonable cause for accepting the advance in cash. It set aside the appellate order and directed the assessing officer to delete the ₹26 lakh penalty.
What the ruling means for property sellers
Section 269SS covers specified sums received in connection with the transfer of immovable property, including advances, even when the transfer has not yet taken place. A genuine transaction, therefore, does not automatically remove the requirement to follow the prescribed payment methods.
The ruling instead demonstrates the importance of Section 273B. The tribunal considered the taxpayer’s financial position, outstanding loan, supporting evidence and the subsequent completion of the sale before granting relief.
Property sellers should continue to use banking channels for advances and sale consideration and retain sale agreements, payment records and loan documents. If a cash transaction has already taken place, the outcome will depend on its specific facts and the evidence available.
The decision is a fact-specific ruling, not a blanket permission to accept cash for property transactions.