Where Incomes Rose Fastest in 2026—and Why Many Still Can’t Afford a Home
American incomes edged higher last year even as the gains failed to catch up with surging housing costs, new U.S. Census Bureau data reveals.
The national median household income reached $84,780 in 2025, up roughly 3.8% from 2024, according to the new American Community Survey data released by the bureau on Thursday.
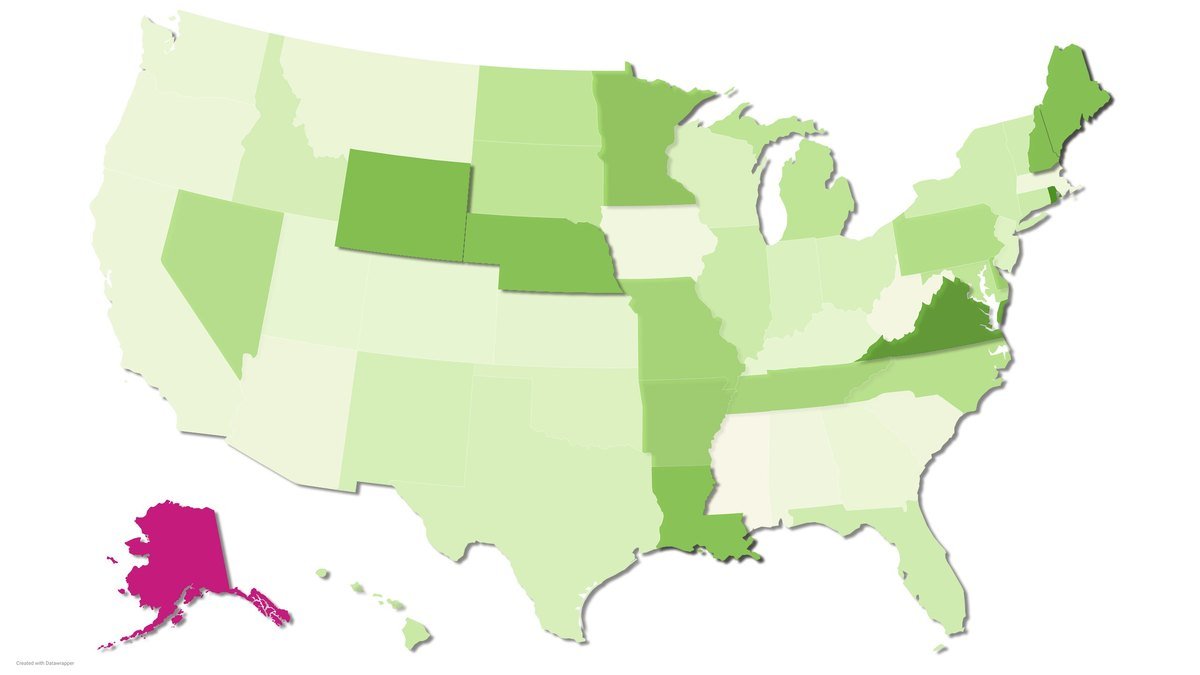
On a nominal basis, incomes rose in every state except Alaska (-0.47%). At the top were Rhode Island (+9%), Virginia (+7.9%), and Wyoming (+7.1%). (After inflation adjustments, only 37 states saw real gains.)
Yet, even in the best-performing states, inflation-adjusted income growth was insufficient to close the affordability gap created by high mortgage rates and elevated prices.
The latest data shows that the typical U.S. household in 2025 earned roughly 27%—or $31,136—less than what is recommended to purchase a $419,250 home, which was the national median listing price for September 2026, according to Realtor.com® housing and income data analysis.
By comparison, the median U.S. household income in 2024 was about 24% below the level required to buy a home, reflecting the deteriorating affordability.
A deepening deficit
The Realtor.com model assumes the latest mortgage rate of 7.32%, a 10% down payment, and 1.7% in combined annual property taxes and insurance. The findings rely on the “30% rule,” which dictates that buyers spend no more than 30% of their gross monthly income on housing costs.
Applying the same methodology to state-level housing and income data reveals that there is no place in the country where a median-income earner can afford to purchase the median-priced home without becoming cost-burdened.
“States have moved further from affordability on average, driven by higher mortgage rates,” explains Realtor.com senior economist Hannah Jones. She notes that the average rate on 30-year fixed home loans increased by more than 1 percentage point from a year ago, cutting into buyer budgets and offsetting the affordability gains from softening home prices and rising incomes.
“In September, home prices fell year over year in 40 of the 50 states and nationally,” adds the economist. “Incomes also rose slightly on average between 2024 and 2025, so higher mortgage rates account for the deterioration in affordability in almost every case.”
Across the 50 states and Washington, DC, the minimum required income to comfortably afford a median-priced home exceeds state-level earnings by anywhere between a manageable 2.9% and a staggering 56.1%.
In other words, while housing is unaffordable nationwide, the severity of the shortfall varies significantly by market.
Midwest remains attainable
The overall affordability picture is nearly identical to last year’s, with the Midwest maintaining its status as the most budget-friendly region.
For the second consecutive year, Iowa ranked as the nation’s most affordable state for buyers. In 2025, the typical local household earned $78,483, which was just $2,287—or 2.9%—shy of the minimum income needed to afford the median-priced $284,900 home.
“We have a strong job market, which I think is the biggest factor,” Chuck Simmons, broker and mortgage originator at Motto Mortgage in Des Moines, IA, tells Realtor.com. “Iowa has always been strong in the insurance and healthcare sectors, but the rise of data centers has brought a lot of additional good-paying job opportunities.”
Simmons also attributes Iowa’s relatively strong performance to the stability of its housing prices.
“This past year saw around 3% in appreciation, which is on the lower end compared to many other states. But it had led to a steady growth without any noticeable bubbles or risk of widespread depreciation,” notes the mortgage broker. “These factors, combined with a strong state housing program for first-time homebuyers, has created an environment where owning outweighs renting in most situations.”
Iowa’s strong showing should come as no surprise considering that the Hawkeye State earned an A grade and finished second nationwide, behind Indiana, in the 2026 Realtor.com Housing Report Cards on the strength of its affordability.
Still, Simmons cautions that high closing costs, insurance premiums, and property taxes continue to erode buyers’ purchasing power. Echoing Jones’ argument, he also stresses the need for lower borrowing costs.
“A 1% drop in rates on a $300,000 loan would lower a payment by around $200 a month on a 30-year loan,” points out the mortgage expert. “Or, for the same payment, a 1% drop in rates would increase a buyer’s purchasing power by around 10%. That kind of savings would definitely make a huge difference in affordability.”
Beyond Iowa, several Midwestern and Rust Belt states posted narrow income deficits, including Illinois, Pennsylvania, Ohio, and Kansas, where shortfalls range between 3.5% and 4.9%.
“Home prices in these states are well-aligned with local incomes,” says Jones. “Growing demand has pushed prices up and eroded some of that advantage, but they still perform best in today’s challenging market.”
The West and coastal states feel the pain
On the other side of the spectrum, high-priced coastal and Western states face the worst homebuying conditions, with Montana ranking dead last.
In the Big Sky State, the typical household earns $77,099, which is nearly 56%—roughly $99,000— below the income needed to finance a median-priced $635,000 home.
Chase Heiland, real estate broker with Keller Williams Montana Realty, argues that Montana’s massive gap between the median home price and the median household income is driven by a combination of sustained buyer demand and limited inventory.
“Prices only run that far ahead of local wages when more people want in than there are homes available,” Heiland tells Realtor.com.
On the supply side of the equation, the agent explains that Montana homeowners are sitting on significant equity and therefore are seldom forced to sell out of “desperation or foreclosure.” Those who do want to sell but cannot secure their desired price often opt to rent out their home.
Another factor that keeps inventory low in Montana is the high cost of new construction.
“Most of the materials have to be shipped in from out of state, Montana is short on construction workers in every region, and winter leaves builders only part of the year to work outside,” says Heiland. “So new homes cost a lot more to put up here than most people expect, especially when you combine that with impact fees most cities and counties impose.”
In the Realtor.com State Report Cards, Montana earned a D, held back by high prices and building costs far outpacing what average buyers can afford.
The affordability crunch has forced many median-wage earners in the state to rent longer or move to outlying commuter towns.
“I see the same thing in the Bozeman area, where people are heading out to Belgrade, Manhattan, and Three Forks for more house,” says Heiland.
At the same time, the agent says he is seeing some encouraging signs in the market that are giving him hope.
“I’ve worked with more local first-time buyers and move-up buyers than I have in years,” he notes. “Wages have come up, there’s more room to negotiate than there was a few years ago, and the people I’m working with are more ready to make decisions than I’ve seen before.”
He attributes this change to buyers’ gradual acceptance of the higher mortgage rate environment.
“A lot of buyers were holding out for interest rates to come down dramatically, and since that hasn’t happened, more people are planning around today’s interest rates,” says Heiland. “Life keeps moving forward for everyone, and they still want to make decisions about where they live and put down roots here.”
Over the long term, the real estate professional contends that for Montana’s housing to become meaningfully more affordable, a series of structural and policy changes are needed, which come with their own complications.
“Impact fees, permitting, and the regulations a builder has to work through all end up in the price of new-construction homes, so easing those where it’s reasonable would help supply,” he says. “That’s a bit of a catch-22, though, because more development changes how these towns feel, and a big part of why people choose Montana is that they don’t want suburban density.”
Additionally, cities and counties must invest in long-term solutions, such as permanent affordability trusts and income-restricted rentals to ensure that housing remains permanently attainable for low- and middle-income families.
“When cities set affordability targets, they usually use 60% or 80% of area median income, and for a lot of working households, that still isn’t a realistic or attainable number,” points out Heiland.
Montana is not alone in its struggle. Buyers in California have to contend with a 49% gap between earned income and the minimum required income to afford a home, followed by Idaho (48.6%), Hawaii (48.2%), and New York (46.7%).
“High demand and limited new construction keep inventory scarce and affordability strained in these states,” concludes Jones.
Reflecting those pressures, New York, Hawaii, and California earned failing grades in the report cards.
Get real estate news in your inbox