Inside Place, Envoy Mortgage’ sprawling real estate vision
- Key Insight: Learn why Place chose to acquire companies like Ardley and Maxwell instead of partnering.
- Expert Quote: “Mortgage tech is still way too fragmented.” — Chad Smith, CEO, Envoy Mortgage
Overview bullets generated by AI with editorial review.
Place and Envoy Mortgage are rapidly growing into significant industry competitors after Place’s spending spree this summer.
The real estate platform’s
Processing Content
“We didn’t want to be beholden to partnerships rather control those elements of the technology roadmap ourselves,” said Chris Stuart, president of Place.

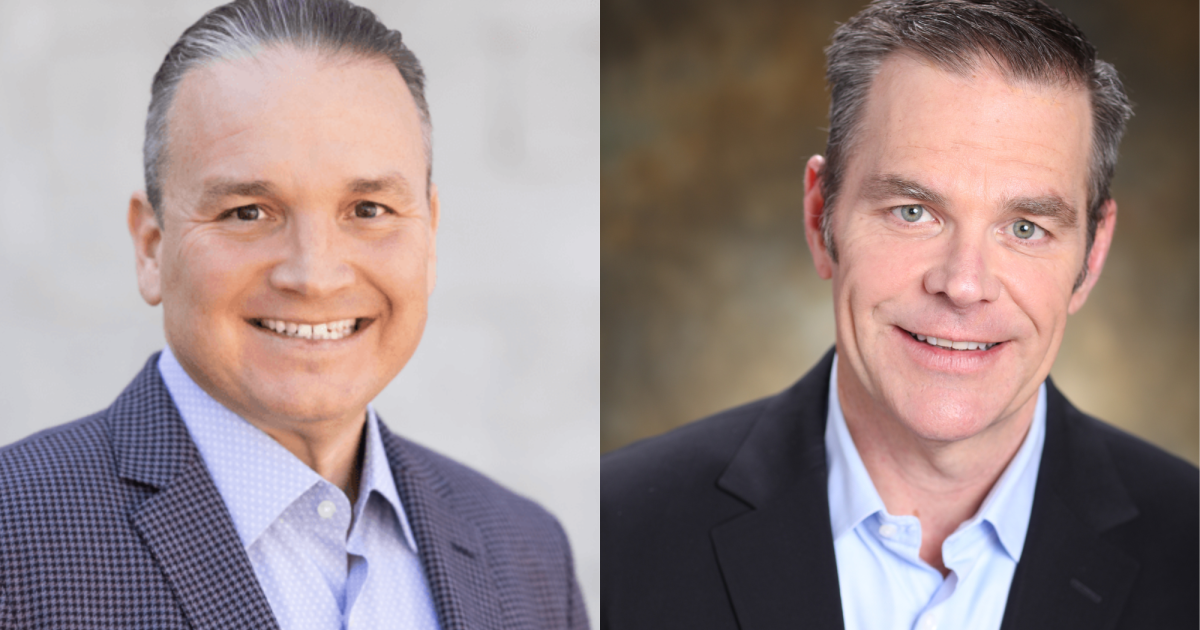
Courtesy of PLACE and Envoy Mortgage
A busy summer included tapping
Stuart and Smith spoke with National Mortgage News and explained the Place model, which combines tech services for its wide environment of top real estate agents, loan officers, and homeowners. The executives described their firm’s edge over industry competitors, and a “holy grail” its marching toward.
This interview has been edited for length and clarity.
What is PLACE, and how does it work with Envoy?
Stuart: Our business is organized around pillars. The first pillar are businesses that we’ve been selling to the industry, that suite of solutions for tens of thousands of agents. The second pillar are the teams powered by PLACE, a separate group of agents leveraging our tech at its core.
The third pillar are businesses like Envoy, adjacent businesses that we need to fulfill our mission. In that third pillar, we also operationalize property management, P&C insurance, a moving concierge and other related services.
Smith: Half of our volume comes from Place teams, and half of our volume comes from our retail originators and their own referral partners.
Why did PLACE buy Ardley, Maxwell and Radian this summer?
Stuart: If we’re going to stand up a parallel community of loan officers, and mimic the Pillar 1 audience of agents with a community of originators, and the Pillar 2 audience with direct captive retail LOs using our tech, we need to own key pieces of the mortgage experience.
We chose to not go back-to-front, with a loan origination system, but rather front-to-back, owning the point-of-sale, owning what top producing folks need to be more competitive. We didn’t want to be beholden to partnerships rather than control those elements of the technology roadmap ourselves.
Relative to
Smith: Having control over [artificial intelligence] and agentic workflows is really good. With Ardley, what I get very excited about is their proof over promise. There’s a 40% higher close rate based on Ardly recapture and retention services than without, and in many cases for our top clients, there’s $15 return for each dollar of invested capital.
What makes a good acquisition target?
Stuart: If it’s a smaller business, you’re looking at the nature of the tech, the key leaders, what is their strategy. Are they just looking to tap out and have a liquidity exit, or do they want to be a part of building what we’re building?
Smith: On the mortgage side, we’re looking at cultural alignment, production, geographical location, and, does everyone buy in? You’re not just making an announcement and then people are going all over the place.
On the mortgage tech side, I am a huge subscriber to [the idea that] mortgage tech is still way too fragmented. There’s a lot of opportunity for us to find things that maybe we don’t have or would get us further, faster in the mortgage stack. So, does it help us get to a less fragmented state faster, with people culturally aligned?
What is something PLACE is trying to solve for in the homebuying process?
Stuart: The largest expenses are tethered to the actual homeownership experience. For example, I’ve moved in but now there’s a leaky roof, my water heater is busted, I’ve got a flooded basement. We believe that the integration of other services, specifically leveraging AI to get preventative on how we serve the homeowner, is in fact kind of the holy grail, and that’s what we’re marching towards.
We want to leverage the rapport that our professionals — the LOs, the agents, the P&C insurers, the property managers — provide for our clients, to serve those homeowners in a more preventative and prescriptive way.
Smith: On the mortgage side, I hear a lot of, “We can close loans faster.” But someone has to move, right? We’re focused on how to create calmness. The lack of repeated asks of the consumer. Instead of speed to close, it’s speed to certainty. I think with Maxwell and Ardley, it’s about speed to certainty. And I think that’s where AI is really going to help.
How are you navigating today’s high-rate environment?
Stuart: There’s tens of thousands of agents that log in every day to one or more pieces of our technology. It’s a broad audience, and the benefit of what we’re building with Envoy is we can speak with them in real time and provide timely, accurate, relevant information that they can share with their real estate clients.
Right now in a high rate environment with inventory growing, it’s a great time to leverage that as a negotiation point for buyers. The normal run-of-the-mill agents might not be getting that direction from their respective teams or brokerages. Downpayment assistance and bond programs are a key piece of what we do at Envoy.
Smith: I like to tell people we have opportunities and areas where a lot of companies don’t have areas. I get to go in front of these agents, and a lot of people don’t get that opportunity.