Big Four probed on offshore tax shelter consulting
- Key insight: Find out how Senate investigators are targeting the Big Four’s offshore tax consulting practices.
- What’s at stake: Whether multinational corporations can continue using empty Malta offices to avoid billions in taxes.
- Supporting data: Four major accounting firms facing a Senate inquiry into offshore tax consulting.
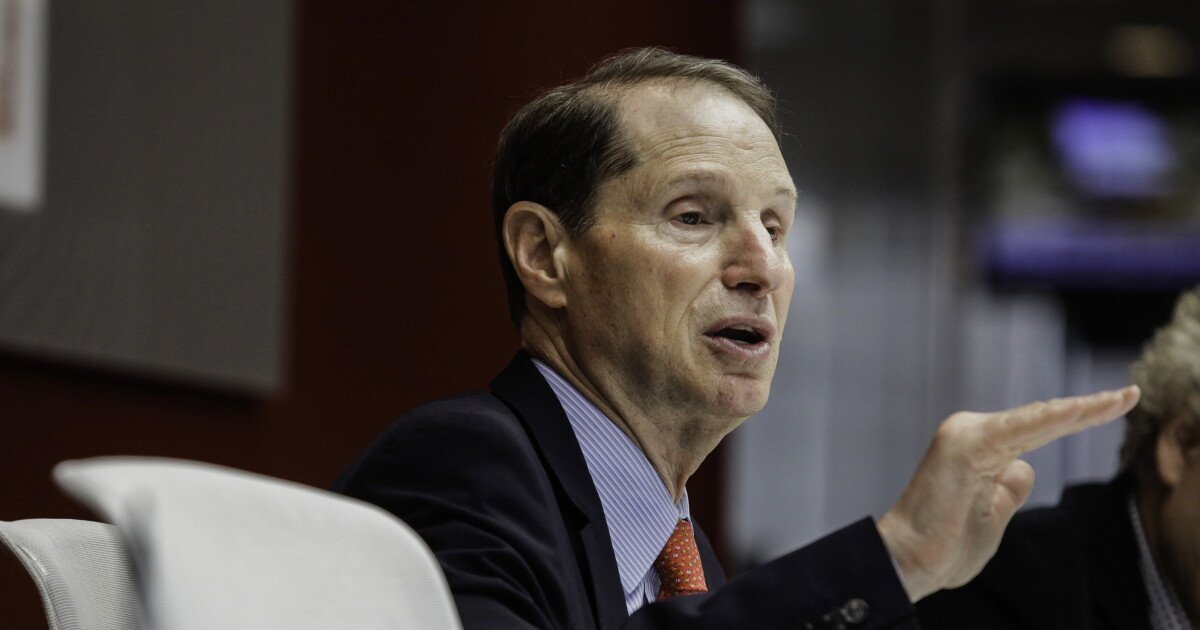
The top Democrat on the Senate Finance Committee, Ron Wyden, D-Oregon, has sent letters to the leaders of the Big Four Firms asking about their consulting work on offshore tax shelters.
Processing Content
The move comes after a report in
In
“For several years now I have been conducting an investigation into the means by which multinational corporations use subsidiaries in jurisdictions treated as foreign for tax purposes to avoid paying billions of dollars in U.S. taxes,” Wyden
Wyden said the tax strategies that giant corporations are exploiting were made possible by the Tax Cuts and Jobs Act of 2017, which allowed “round-tripping” and “global trending” that enabled corporations to avoid billions in taxes.
This summer, an independent investigator from The New York Times visited an office building in Malta where many of the Big Four clients have set up subsidiaries. The investigator only found empty offices, with the lights off and little to no employees. Wyden contended that the scheme to use employee-free shell companies in Malta to artificially drive down taxes merits further investigation.
“I have long been concerned by the extent to which schemes such as ‘global blending’ and ’round tripping’ are being used by multinational corporations to shift profits offshore,” he said. “While working class Americans dutifully pay taxes on every paycheck, sophisticated accountants and tax lawyers are devising clever strategies for corporate giants to continue exploiting offshore tax havens to avoid paying their fair share.”
In the letter, Wyden requested that CEO’s of these accounting firms answer the following questions by no later than November 10, 2026:
- Has [your firm] worked with U.S. corporate clients to develop and implement tax planning structures involving subsidiaries in Malta and allocating profits to subsidiaries in Malta? If yes, please describe these structures in extensive detail and how they help U.S. multinational corporations reduce their tax liabilities in the U.S. or globally.
- Has [your firm] advised corporate clients that U.S. or European multinational clients can use Maltese entities to avoid or reduce U.S. or foreign taxes, including those put in place under the Pillar 2 global minimum tax system? If yes, please describe how.
- Has [your firm] ever prepared any presentations, slide decks or other marketing materials (such as white papers, memoranda or legal briefs) for U.S. multinational corporate clients describing tax strategies involving the use of Maltese entities? If yes, please provide copies of these documents, with redactions of personally identifiable information or other data that would reveal the identity of the client(s).
- Has [your firm] ever memorialized in written materials the extent to which tax strategies involving Maltese entities have helped, or can help, U.S. multinational corporations reduce U.S. or foreign tax liabilities? If yes, please provide any documents outlining how much in U.S. corporate income taxes, other U.S. or non-U.S. tax liabilities, U.S. clients have avoided paying, or would expect to avoid, as a result of tax planning strategies involving Maltese entities.
- Has [your firm] generated any fees devising or marketing tax planning strategies involving Malta to U.S. multinational corporations? If yes, please provide the number of clients who have paid for these services as well as the total dollar amount of fees these services have generated.
- Has [your firm] ever worked with any local Maltese law firms or tax advisers to help U.S. multinational corporations devise or implement tax reduction strategies involving the use of Maltese subsidiaries? If yes, please describe these efforts.
- Has [your firm] ever worked with Maltese government officials to devise or implement strategies to help U.S. multinational corporations implement tax reduction strategies involving the use of Maltese subsidiaries? If yes, please describe these efforts.
Introductory bullet points created by AI with editorial review.