U.S. Virgin Islands proposes $250 million bond sale

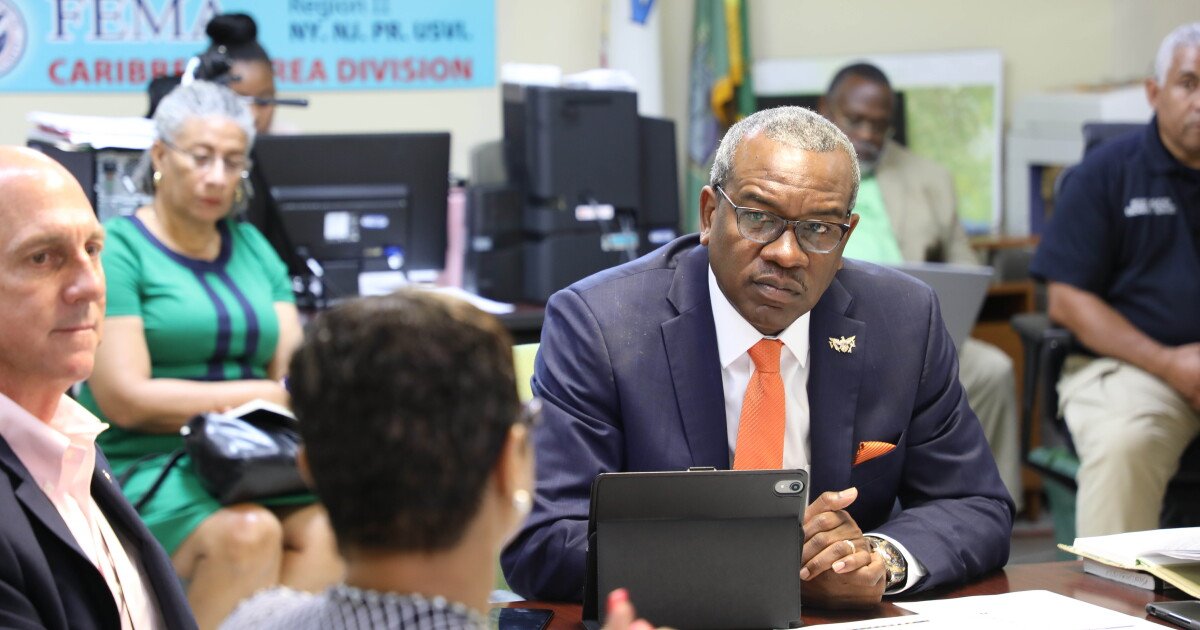
U.S. Virgin Islands Gov. Albert Bryan, Jr., is proposing the government issue $250 million gross receipts tax bonds to address overdue obligations and pressing needs for itself, two public utilities and two hospitals.
Processing Content
“These are obligations and financial pressures that already exist and continuing to carry them without a comprehensive solution has a cost of its own,” Bryan said.
The islands’ government,
The bonds would provide $85 million of funding to the hospitals, $80 million to public authorities, $70 million to the central government for past due obligations and about $15 million for capital needs in the legislative and judicial branches and economic development initiatives.
“Bonding for operations is usually a red flag and this is essentially borrowing for operations,” said Joseph Krist, publisher of Muni Credit News. “In this case, it may be the only way to fund liquidity given the Trump administration’s general attitude toward the U.S. possessions. The gross receipts tax is a proven credit so using that issuance is the best cost source of borrowing the Virgin Islands has at present.”
“It is never ideal to bond for back wages and vendor payments,” said John Hallacy, president of John Hallacy Consulting, LLC. “However, if it is done in concert with a budget reform plan to prevent further deterioration, it passes muster.
“However, this approach should be completed on a one-time basis and not as an ongoing technique,” Hallacy said. “Staving off sliding into receivership has a value.”
“Participating institutions would be required to develop five-year financial sustainability plans, strengthen financial reporting and audit compliance, and establish measurable goals for improving operational efficiency and reducing their dependence on central government assistance over time,” Bryan’s office said in a statement.
The
Schneider Regional Medical Center would receive $45 million and Gov. Juan F. Luis Hospital and Medical Center would receive $40 million to address pressing needs.
WAPA and the Virgin Islands Waste Management Authority would each get $40 million to address outstanding financial obligations.
The bulk of the money for the central government would be broken down so that $30 million would go to retroactive wages payments and outstanding tax refunds, $10 million would go to government vendor payments and $30 million toward repaying a line of credit.
An outside consultant in January told the central government WAPA needed to clear $375 to $498 million in debt — or to obtain roughly similar amounts of cash without further debt — to be solvent.
The proposal for the bond issuance now goes to the legislature for approval.
The WAPA power division had $203.6 million in bonds and bond anticipation notes outstanding as of June 30, 2024, the latest available information. It had liabilities of $1.242 billion.
The WAPA water division had $2.7 million of long-term debt and $109 million of liabilities.
The USVI Office of Management and Budget reports that as of April 30, 2025, it had $457 million of gross receipts revenue bonds and $54 million of Garvee bonds outstanding.
In 2022 the islands sent up the Matching Fund Special Purpose Securitization Corporation, which sold about $920 million of rum tax-backed bonds.