Greg Abel Says Every Point of BNSF Profit Margin Adds About $230 Million of Cash Flow for Berkshire Hathaway
You likely know that Berkshire Hathaway (BRKA +0.22%) (BRKB -0.15%) is ultimately a massive insurance operation that owns a combination of publicly traded stocks and privately owned enterprises (like Duracell, Clayton Homes, and flooring company Shaw). What’s less obvious is just how much cash these wholly owned businesses generate every year. In 2025, Berkshire’s private companies produced $44.5 billion in operating earnings.
Even more surprising is where a sizable chunk of it comes from. Although insurance is (usually) its single-biggest cash cow, Berkshire Hathaway’s railroad BNSF — you may know it better as Burlington Northern Santa Fe — accounts for more than 10% of the conglomerate’s total operating income.
And CEO Greg Abel expects that number to grow for the foreseeable future.
Berkshire Hathaway CEO Greg Abel. Image source: Getty Images.
It’s clearly on Abel’s mind, and for good reason
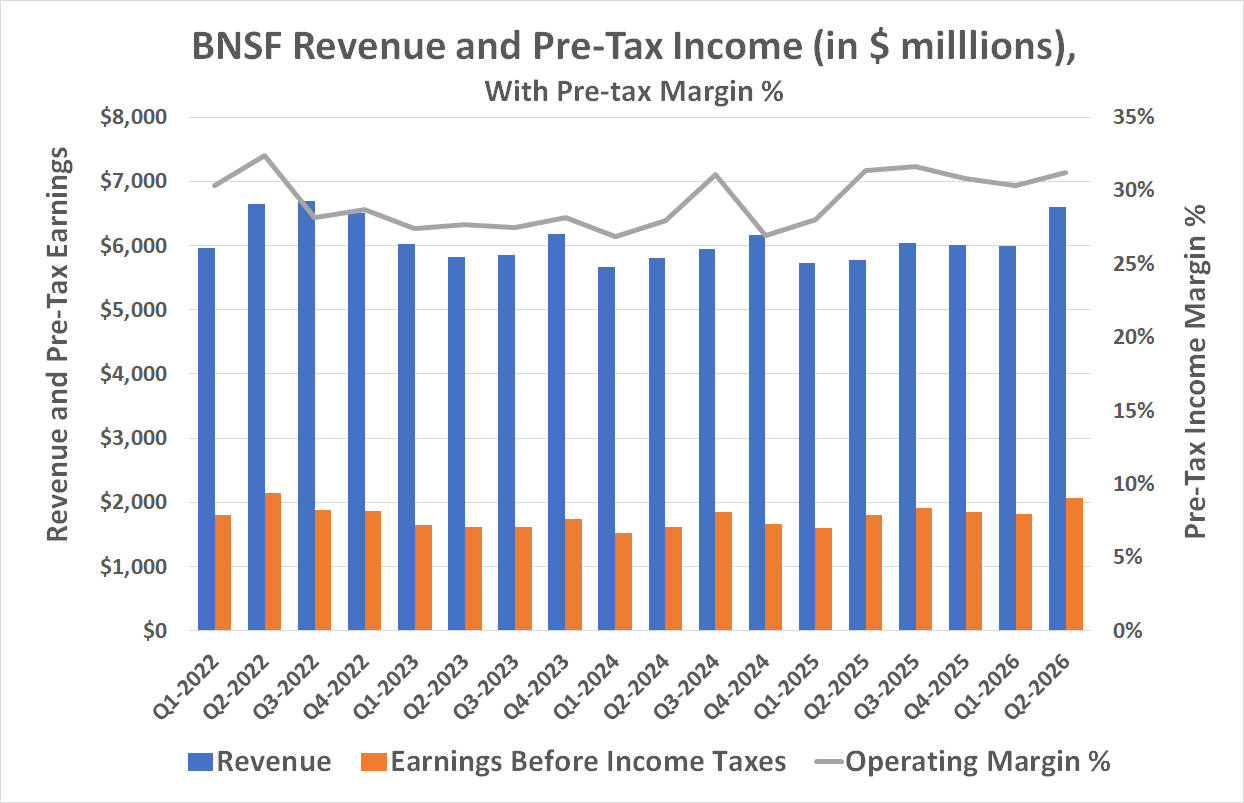
How do we know Abel is eyeing something bigger and better for BNSF? In his first-ever letter to Berkshire shareholders published in February, Warren Buffett‘s replacement plainly stated about the railroad, “The team recognizes the significance of this opportunity, and we will be disappointed if we do not deliver a substantial improvement over the next few years.” He even offered specific numbers, explaining, “Each one-percentage-point improvement in operating margin generates approximately $230 million of incremental operating cash flow for our owners.”
BRKB Berkshire Hathaway
$538.99-$0.83 (-0.15%)
NYSE · As of 4:00 PM ET 10/21/26
For perspective on that figure, BNSF’s 2025 revenue was $23.5 billion. With a 34.5% operating margin, that amounts to about $8.1 billion in operational cash flow from this one business.
And there’s opportunity ahead to be sure. While intermediate-term growth outlooks for the entire domestic rail industry are only in the mid-single digits, more efficiency, like that BNSF began achieving last year, will translate into a better bottom line. These efforts are already making a positive impact.
Data source: Berkshire Hathaway. Chart by author.
Rival railroads point to what’s possible
As for what’s realistic here, obviously nobody owns a functioning crystal ball. We do, however, know that rival railroad Union Pacific (UNP +0.09%) is turning roughly 40% of its revenue into operating earnings right now, while CSX‘s (CSX +0.67%) operating margin rate is in the ballpark of 38%, pointing to what’s possible. If BNSF can pump up its operating margins on its current revenue by just three percentage points to CSX’s levels, that’s roughly $700 million in additional annual pretax income.
And that’s without any revenue growth whatsoever. If revenue can also grow at a 3% annual rate, BNSF’s contribution to Berkshire Hathaway’s bottom line could approximately double within five years, putting it in the ballpark of $10 billion per year. That’s not chump change.
Readily addressable opportunity with immediate impact
Of course, the conglomerate’s other privately owned businesses, such as Berkshire Hathaway Energy and the recently acquired homebuilder Taylor Morrison, are also being managed to maximize profit growth.
Improving BNSF’s fiscal performance, however, looks like the low-hanging fruit to pick right now, with the most immediate potential for near-term impact. Don’t be surprised to see more of the narrative regarding Berkshire focusing on this particular business for the foreseeable future.
It’s another reason to be bullish on this conglomerate at this time, even if it’s not the primary one.