Mutual fund growth vs IDCW plans: Top 5 schemes’ returns compared, NAV differences — What investors should know
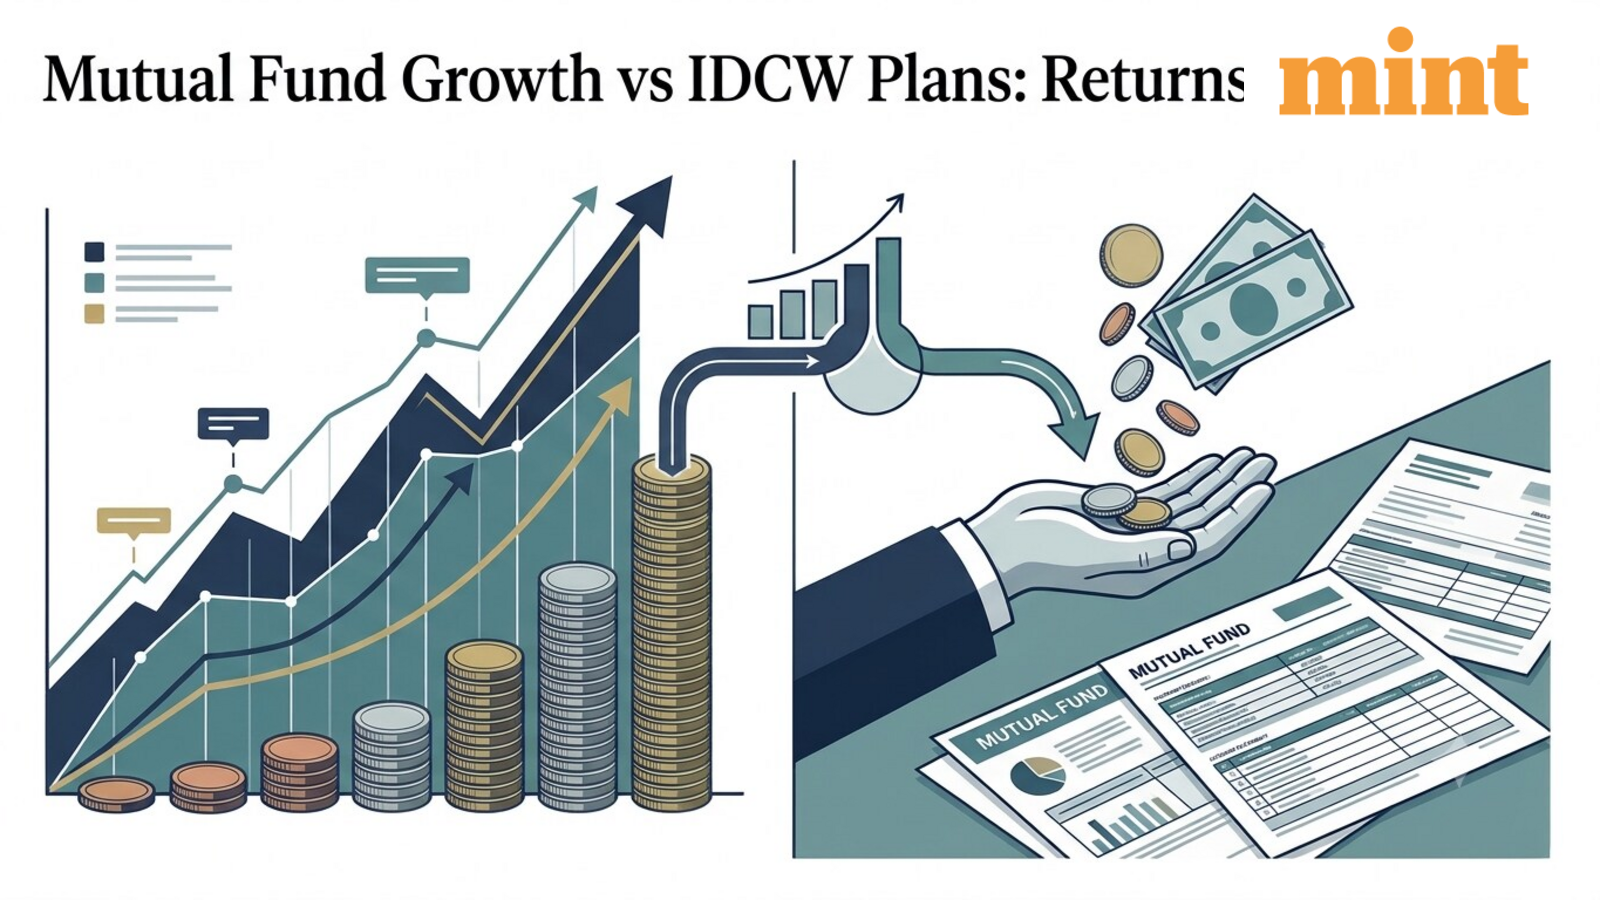
If you invest in mutual funds, you may have noticed two options under the same scheme: Growth and Income Distribution cum Capital Withdrawal (IDCW). While both options invest in the same underlying portfolio, they differ in how earnings are handled, which can affect your cash flows, the number of units you hold, and the way your investment grows over time.
Understanding these differences is important when comparing mutual fund returns. A higher or lower Net Asset Value (NAV) does not, by itself, indicate which option has delivered better returns. Investors must also account for distributions and the reinvestment of payouts.
What are growth and IDCW mutual fund plans?
Growth option: Under this option, earnings remain invested in the scheme rather than being distributed to investors. The value of the investment grows or falls with the scheme’s performance, reflected in its NAV. Investors realise gains when they redeem their units.
IDCW option: Under this option, the mutual fund may distribute a portion of its distributable surplus to investors, subject to availability and the scheme’s terms. The amount distributed is not guaranteed, and the NAV falls by an amount corresponding to the distribution, all else being equal.
The Securities and Exchange Board of India (SEBI) renamed the dividend option as IDCW, effective April 1, 2021, to clarify that distributions may include both income and capital. Therefore, an IDCW distribution should not automatically be viewed as additional profit.
IDCW has two common variants. Under the IDCW Payout option, the profits are paid to the investor, and NAV falls. Under the IDCW Reinvestment option, the distribution is used to purchase additional units. In the latter case, the investor holds more units, but the NAV adjusts for the distribution.
In a Growth option, earnings remain invested in the mutual fund scheme, contributing to its NAV and allowing returns to compound over time. In an IDCW Reinvestment option, distributions declared by the scheme are used to purchase additional units at the applicable NAV.
How do the returns of the top 5 equity mutual fund schemes compare?
The figures below show the returns and NAVs of the schemes across their Growth, IDCW Reinvestment (IDCW-R), and IDCW Payout (IDCW-P) options.
| Mutual fund scheme | Option | YTD Returns (%) | NAV ( ₹) |
| Bank of India Small Cap | Direct Growth | 28.88% | ₹64.89 |
| Bank of India Small Cap | Direct IDCW-R | 28.88% | ₹48.60 |
| Bank of India Small Cap | Direct IDCW-P | 28.88% | ₹48.60 |
| TrustMF Small Cap | Direct Growth | 23.65% | ₹13.49 |
| TrustMF Small Cap | Direct IDCW-R | 23.65% | ₹13.49 |
| TrustMF Small Cap | Direct IDCW-P | 23.65% | ₹13.49 |
| Motilal Oswal Focused | Direct Growth | 20.29% | ₹62.33 |
| Motilal Oswal Focused | Direct IDCW-R | 19.91% | ₹25.62 |
| Motilal Oswal Focused | Direct IDCW-P | 19.91% | ₹25.62 |
| Motilal Oswal Small Cap | Direct Growth | 18.81% | ₹17.03 |
| Motilal Oswal Small Cap | Direct IDCW-R | 18.81% | ₹17.03 |
| Motilal Oswal Small Cap | Direct IDCW-P | 18.81% | ₹17.03 |
| Union Small Cap | Direct Growth | 18.97% | ₹64.41 |
| Union Small Cap | Direct IDCW-R | 17.25% | ₹42.38 |
| Union Small Cap | Direct IDCW-P | 17.25% | ₹42.38 |
*Source: Morningstar, Data as on 19 October 2026
The three Bank of India Small Cap options and the three TrustMF Small Cap options reported identical returns across their Growth, IDCW Reinvestment, and IDCW Payout options.
For Motilal Oswal Focused, the Growth option delivered a year-to-date (YTD) return of 20.29%, compared with 19.91% for both IDCW options.
However, the NAV figures show notable differences across some options. Bank of India Small Cap’s Growth option had a NAV of ₹64.89, compared with ₹48.60 for both IDCW options.
Similarly, Motilal Oswal Focused’s Growth option had a NAV of ₹62.33, while its IDCW Reinvestment and IDCW Payout options had a NAV of ₹25.62. TrustMF Small Cap’s NAV was ₹13.49 across all three options.
These differences do not necessarily indicate that the Growth option has performed better. NAV represents the per-unit value of a scheme, not the investor’s total return.
Over the long term, the growth option can help investors build a larger corpus by keeping earnings invested and allowing them to compound. Under the IDCW Payout option, distributions are paid to investors, reducing the amount retained within the scheme.
The choice depends on the investor’s cash-flow needs and investment objective. Investors seeking long-term wealth accumulation may find the growth option simpler because earnings remain invested. Those who prefer periodic cash distributions may consider IDCW.
Disclaimer: This is purely for educational/informational purposes and should not be taken as any sort of investment advice. Always consult a SEBI-registered advisor before making any investment decisions.