Munis strengthen on the short end despite heavy calendar
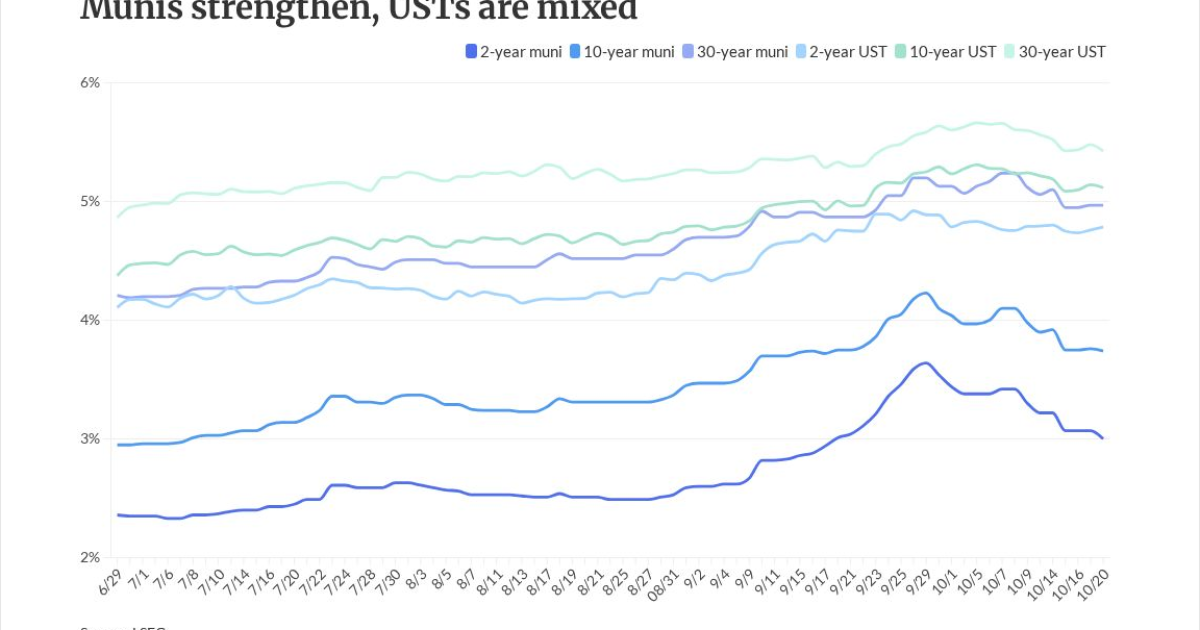
Munis were firmer on Tuesday, as U.S. Treasuries were richer out long and equities ended mixed.
Processing Content
Muni yields richened by up to seven basis points, depending on the scale, with gains at the front of the curve. USTs richened by one to five basis points five years and out.
Heading into the week, the consensus was that a larger new-issue calendar would cause weakness in munis, according to Chris Brigati, managing director and CIO at SWBC. That hasn’t materialized, Brigati said, suggesting that there was enough value and pent-up demand for munis to weather the bigger supply.
In USTs, “we saw a notable shift last week,” Brigati said. The higher inflation data created “a flight to quality in Treasuries out of the high-flying AI trade.”
However, the underlying inflationary pressures that have plagued USTs still exist, Brigati said, so the UST weakness likely isn’t gone for good.
CUSIP requests rise
In September, the aggregate total of identifier requests for new municipal securities — including municipal bonds, long-term and short-term notes, and commercial paper — rose 2.0% versus August totals.
On a year-over-year basis, overall municipal volumes were down 1.5% through the end of September.
Texas led state-level municipal request volume with a total of 184 new CUSIP requests in September, followed by New York (175) and California (104).
For the specific category of municipal bonds, there was a drop of 2.4% month-over-month, and requests are down 3.5% year-over-year.
New-issue market
In the primary market Tuesday, Jefferies priced for the California State Public Works Board (Aa3/A+/AA-/) $485.34 million of lease revenue bonds, Series 2026D, with 5s of 10/2027 at 2.98%, 5s of 2031 at 3.37%, 5s of 2036 at 3.79%, 5s of 2041 at 4.42%, 5s of 2046 at 4.83% and 5.25s of 2051 at 4.92%, callable 10/2036.
In the competitive market, the Virginia Public Building Authority (Aa1/AA+/AA+/) sold to BofA Securities $475.42 million of public facilities revenue bonds, Series 2026A, with 5s of 8/2027 at 3.06%, 5s of 2031 at 3.38%, 5s of 2036 at 3.81%, 5s of 2041 at 4.42% and 5s of 2046 at 4.80%, callable 8/2036, except for the 2036 maturity, which is noncall.