How should you withdraw money after early retirement? Expert explains the 3-bucket strategy for your FIRE corpus
Building a corpus for financial independence and early retirement (FIRE) requires a different investment strategy from saving for short-term financial goals. While investors need sufficient equity exposure to grow their wealth over the long term, they must also ensure that their money can support regular expenses once they stop working. The challenge is to build a corpus that can sustain decades of withdrawals without making retirement income overly dependent on short-term market movements.
Jasmeet Singh, executive director at Anand Rathi Wealth, says asset allocation should depend on the time remaining until financial independence rather than age alone. The strategy should also change once investors move from accumulating wealth to withdrawing money to fund their lifestyle.
How should you allocate investments as you approach FIRE?
Consider two investors aged 40. One plans to achieve financial independence at 45, while the other intends to retire at 60. The first has five years to build the remaining corpus, while the second has 20 years to benefit from potential equity-market growth. Their investment strategies, therefore, should differ despite being the same age.
Investors with longer investment horizons can maintain higher equity exposure, depending on their risk appetite. Those approaching their FIRE target should gradually increase their debt allocation to reduce the impact of market volatility on their retirement plans.
Financial responsibilities also influence the amount available for investment. Home loan repayments, children’s education and supporting parents can affect monthly contributions towards FIRE. Investors should periodically review their target corpus, contributions and asset allocation to assess whether they remain on track.
Equity mutual funds or index funds for FIRE?
For long-term wealth creation, Singh favours actively managed equity mutual funds because they offer the potential to outperform market indices.
During the accumulation phase, investors with a long investment horizon and suitable risk appetite can consider an allocation of 80% equity and 20% debt. Within the equity portion, Singh suggests allocating 50-55% to large-cap funds, with the balance spread across mid-cap and small-cap funds, depending on risk capacity.
This allocation is a suggested approach rather than a universal prescription. The appropriate mix depends on the investor’s financial position, risk tolerance and time remaining until financial independence.
However, building a retirement corpus and drawing an income from it require different strategies. Once investors achieve FIRE, they need to meet regular expenses while ensuring that their investments continue to grow over the years.
How the three-basket strategy can help manage FIRE withdrawals
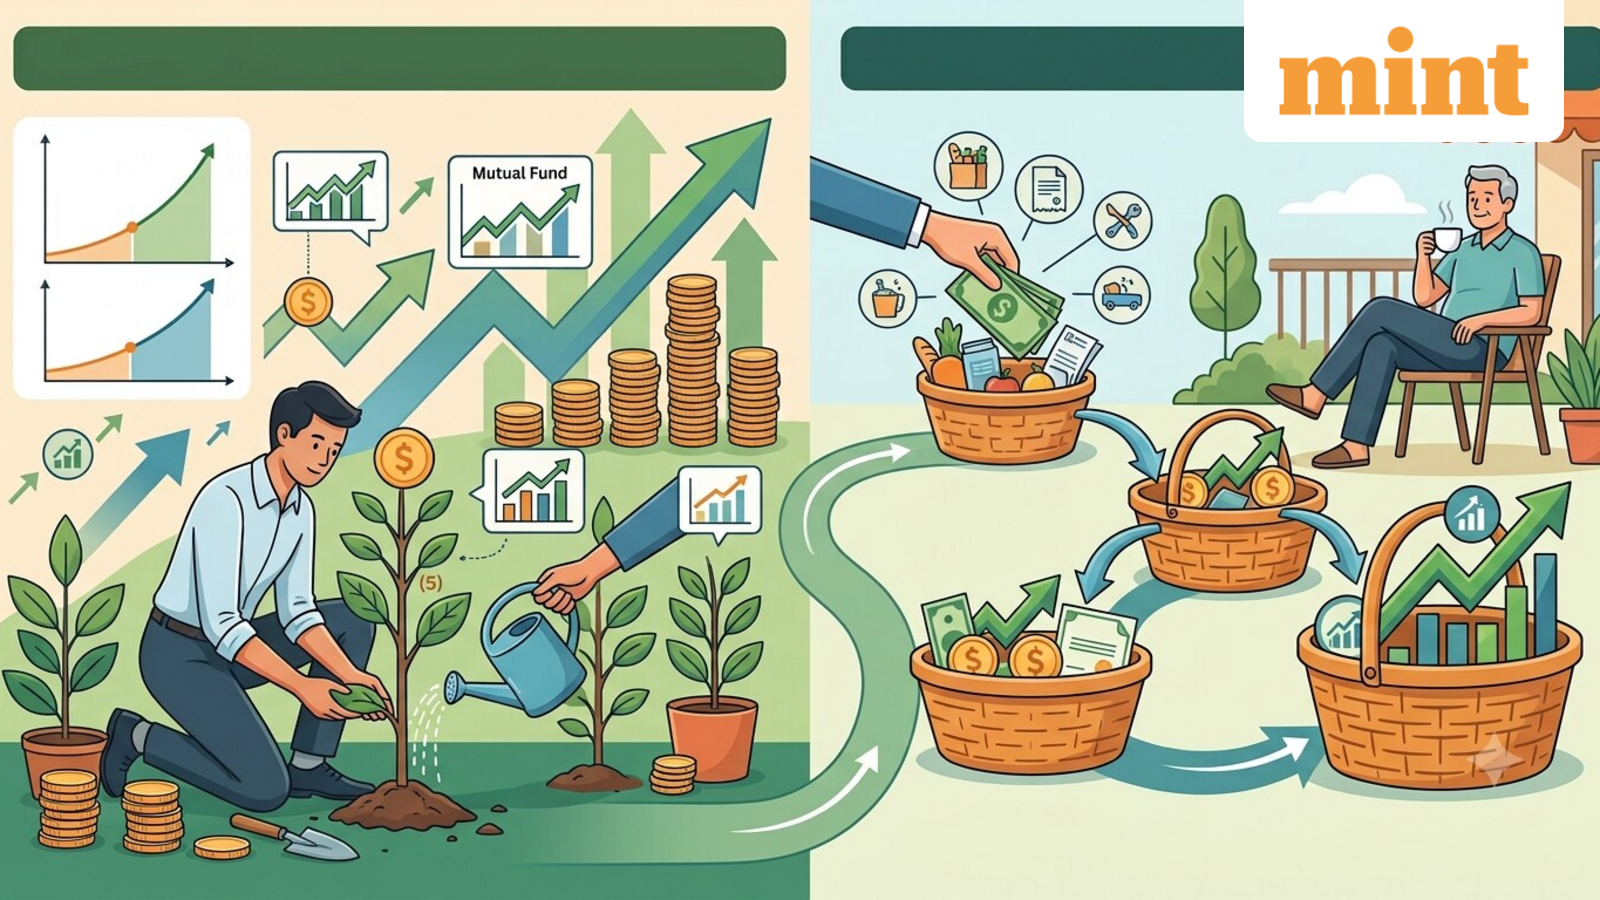
Singh suggests a three-basket approach to help investors manage withdrawals after achieving financial independence.
Basket A: Immediate expenses. Keep approximately two years of expenses in low-risk, liquid instruments. This reserve can help investors meet near-term needs without selling equity investments during market corrections.
Basket B: Medium-term expenses. Maintain a mix of 60-70% equity and 30-40% debt, where suitable. This basket aims to balance growth and stability while periodically replenishing the first basket.
Basket C: Long-term growth. Maintain approximately 80% equity and 20% debt for expenses that are several years away. The equity component aims to support long-term growth, while debt provides diversification.
The idea is to avoid relying entirely on equity investments to fund immediate expenses. If markets decline, the liquid reserve can help cover near-term withdrawals, reducing the need to sell equity at unfavourable prices.
The three baskets should not be treated as fixed allocations for every retiree. The amount held in each will depend on expected expenses, the size of the corpus, risk tolerance and the investor’s withdrawal requirements.
Ultimately, FIRE planning involves more than reaching a target corpus. Investors must also decide how to allocate their assets as retirement approaches and how to fund expenses once regular employment income stops. Periodic reviews of the portfolio and withdrawal needs can help keep the strategy aligned with the lifestyle they intend to maintain.