Breakfast News: Stocks to Think About Selling
Ask investors about their best decision, and they’ll tell you about a stock they bought. Almost nobody brags about a sale. Selling gets far less attention, even though it matters just as much. Money parked in a business that’s unlikely to beat the market over the long term could work harder somewhere else. The company doesn’t have to be in trouble for that to be true.
So we asked our analysts, two each from Team Rule Breakers and Team Hidden Gems, a pointed question: Which stock would you consider selling now, and why? Their answers aren’t official recommendations and may not reflect each team’s broader view. But they’re investors first, and they build a sell case with the same rigor as a buy case here. Let’s hear from them.

1. What Makes Zoom Head Higher?
Jason Moser
Team Rule Breakers
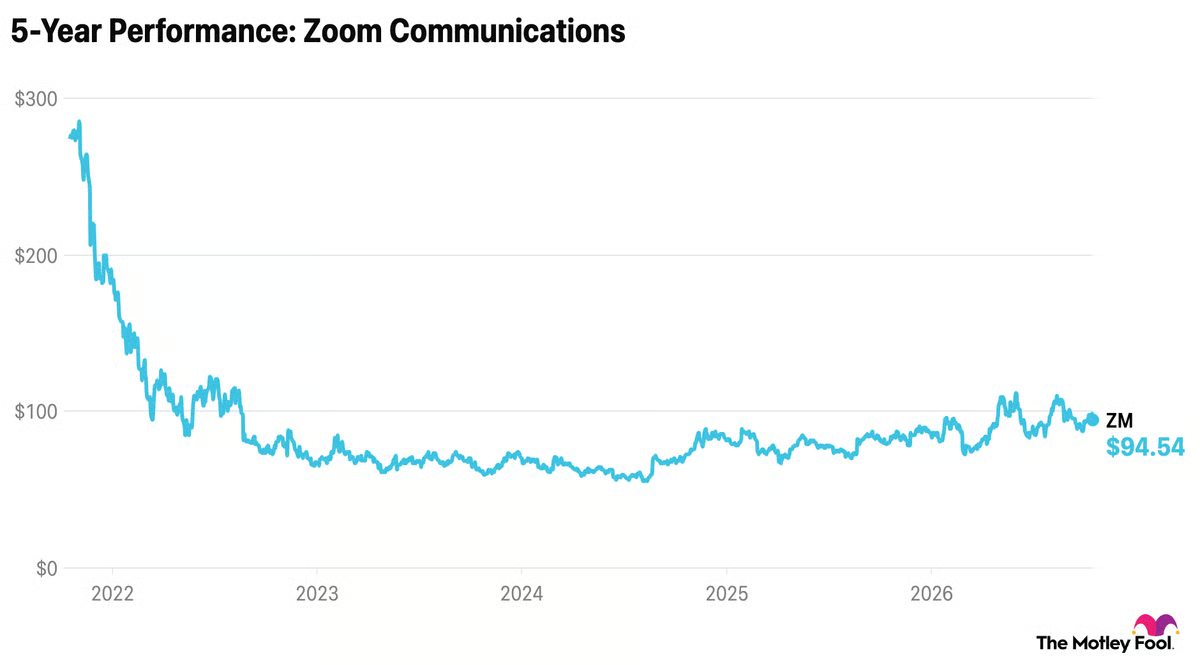
The world was a different place six years ago. Remote work took over, and how we communicate and work with each other underwent massive changes. At the time, it looked like Zoom Communications (ZM -4.38%) was going to grow to the sky given its slick, easy-to-use interface.
Today, while Zoom remains a useful tool for many businesses, it’s simply never evolved past what made it so popular early on: a video chat app. Most companies have gone back to the office to work together in person. While we hear about Zoom’s investments in AI, nothing has fundamentally changed with its core offering. This has slowed growth and raised questions about what’s next.
In the past five years, revenue has grown just 6.5% annualized. To be fair, Zoom has done a good job bringing it all down to the bottom line — its net income rose 26.5% annualized over the same period. Still, the stock continues to languish.
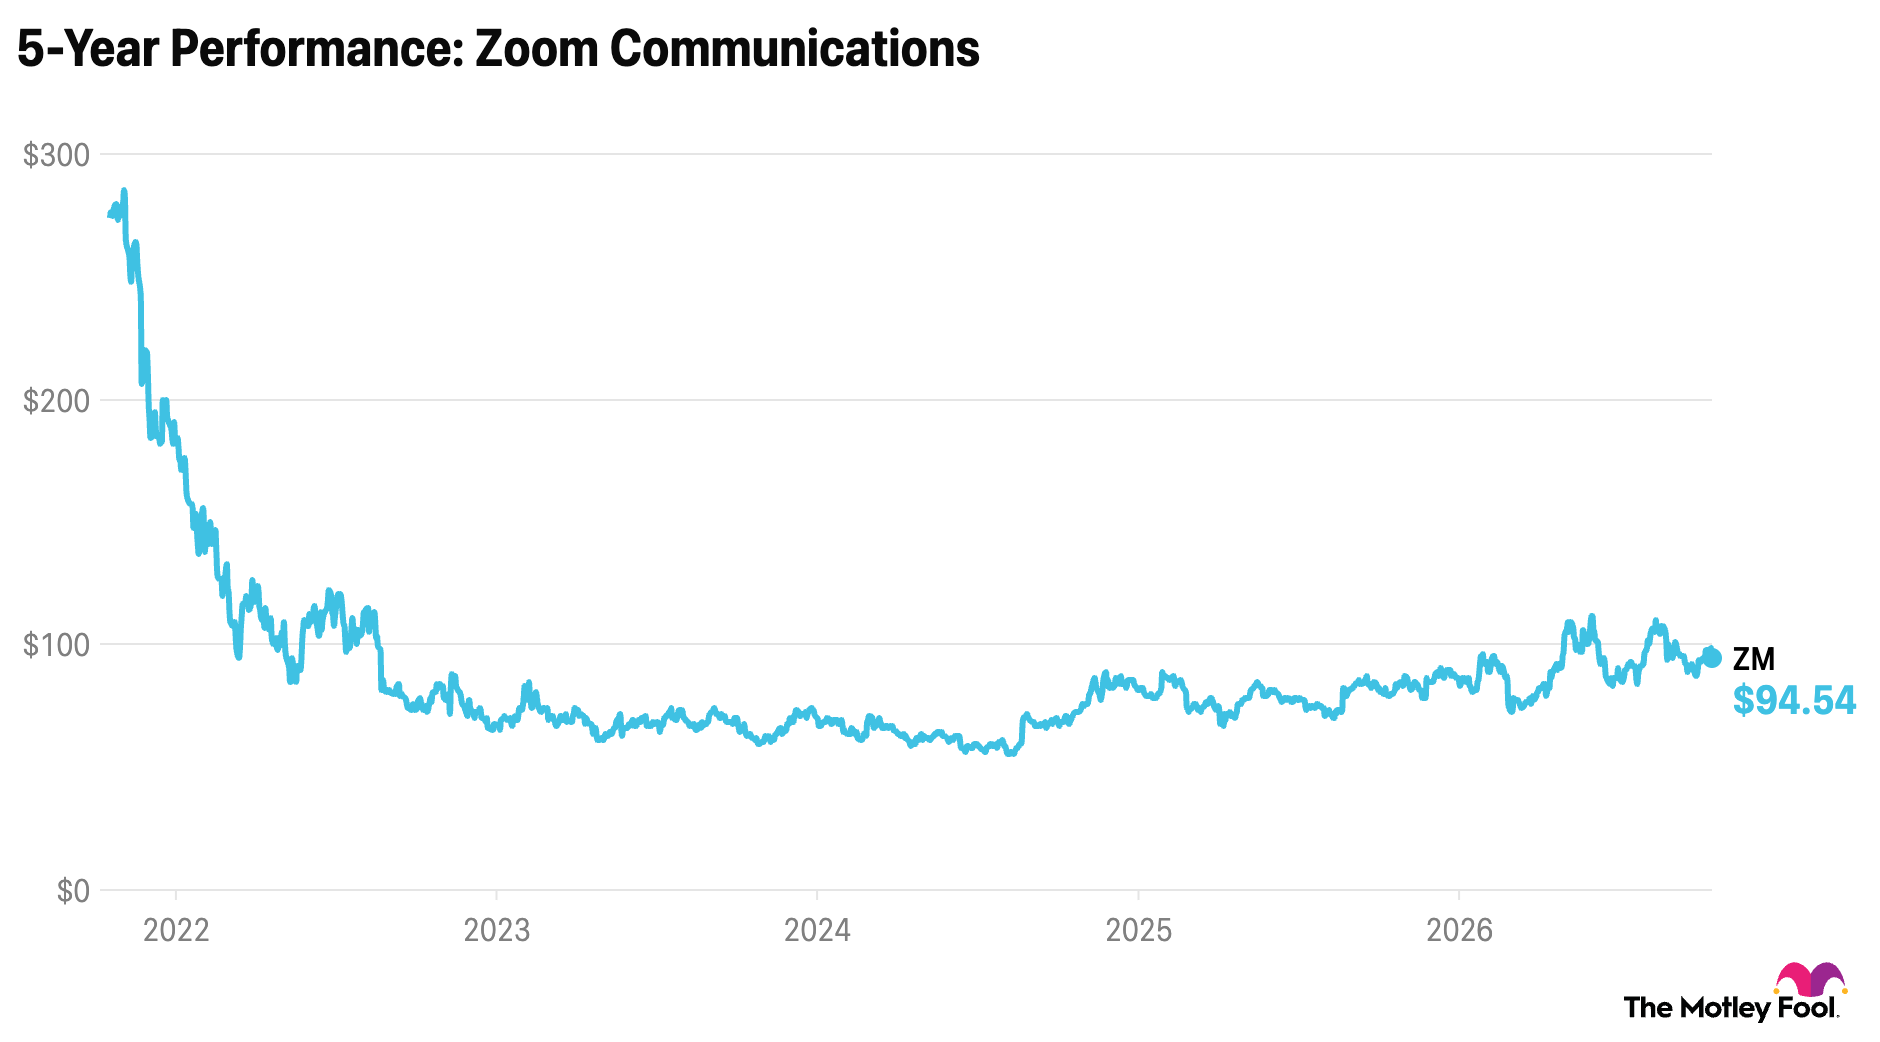
There’s always the possibility that Zoom will be acquired. But, that’s not a thesis, and it’s hard to see where growth is going to come from in the near term. That makes Zoom one worth at least considering cutting loose, in my opinion.
2. Has Block Hit a Roadblock?
Danny Vena
Team Rule Breakers
When Block (NASDAQ: XYZ) — then Square — first debuted its smartphone-friendly mobile credit card reader, it was a game changer for small businesses. The company’s payment processing business grew rapidly, cementing it as a fintech leader. Over the ensuing 17 years, the world has changed, and Block was forced to change with it. The addition of Square Capital and Cash App helped the company maintain its upward trajectory.
In recent years, however, Block hasn’t lived up to its promise. Cash App’s active users and organic growth have slowed to a crawl. Block’s reliance on Bitcoin (BTC -1.55%) has made its results uneven, and profits (and the stock price) continue to lag despite revenue growing at a respectable pace.. Block’s recent focus on efficiency and profitability is admirable, but it could be too little, too late.
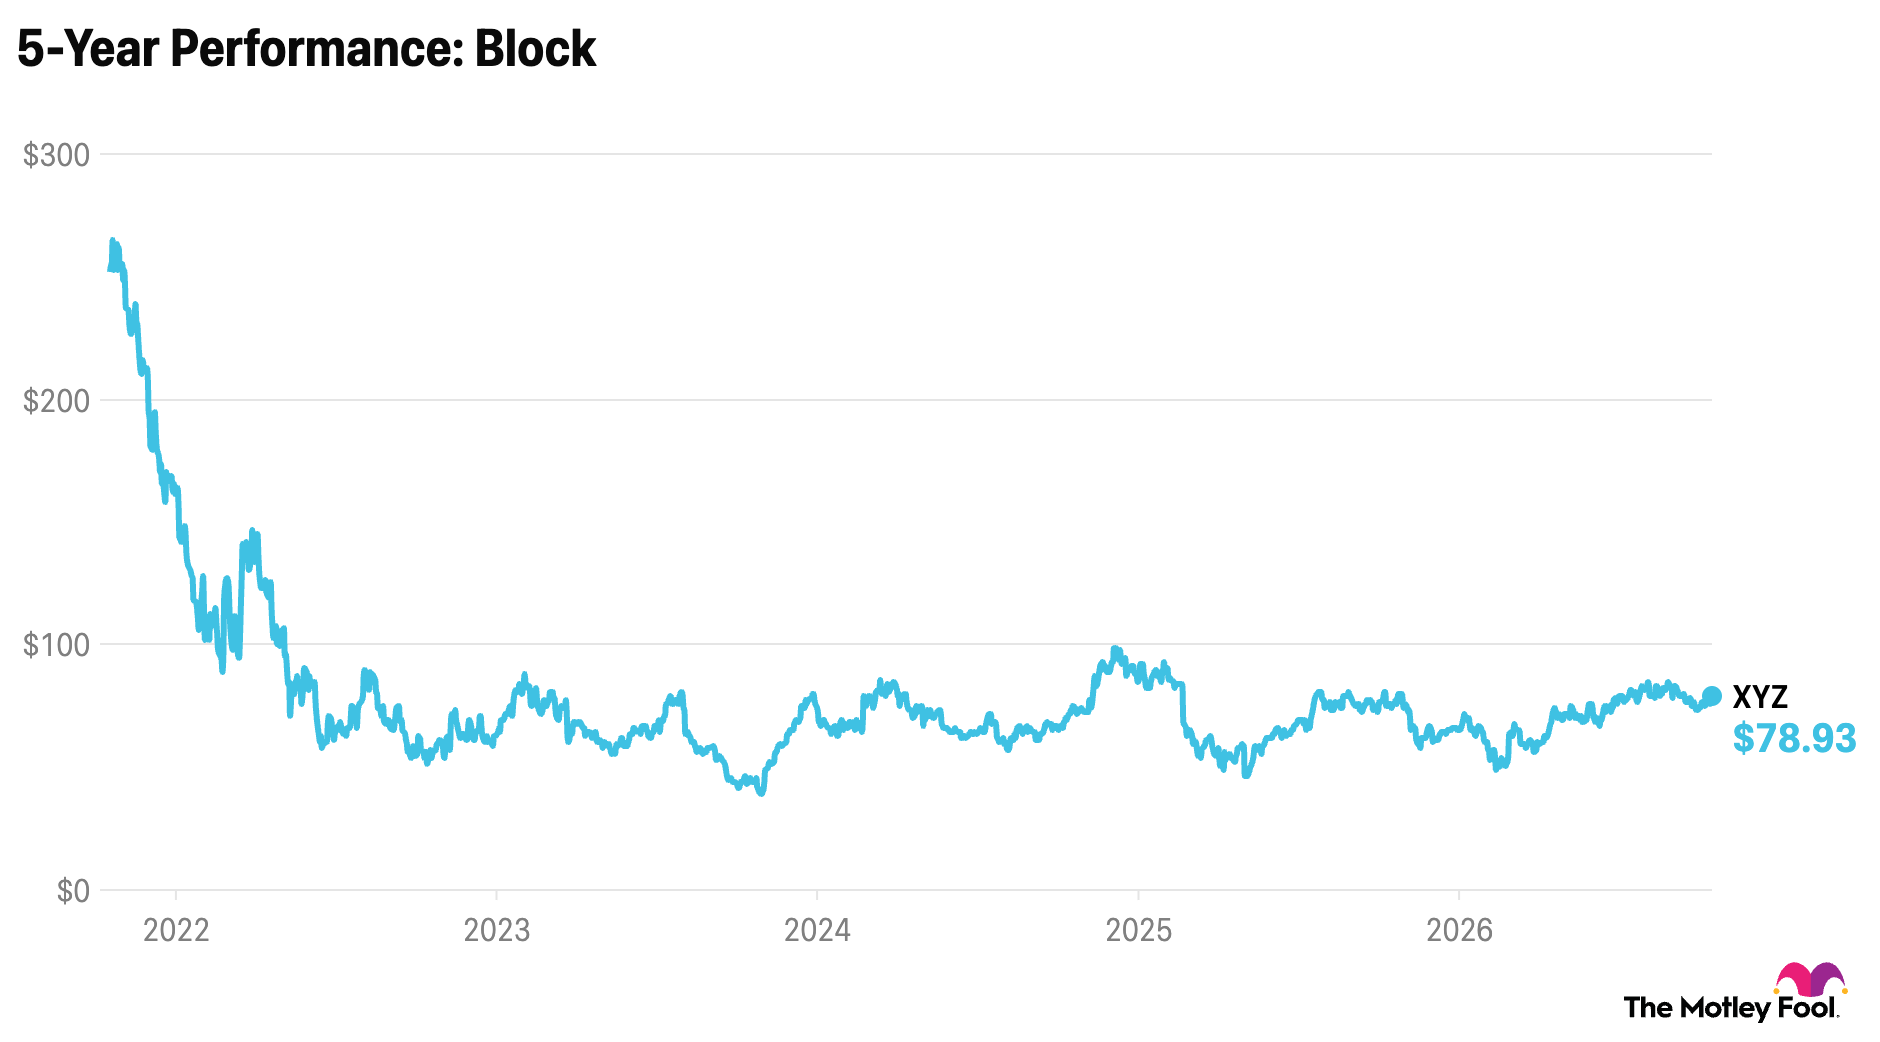
It’s certainly possible that Block could do well going forward, but I suspect its growth from here will be tepid at best. I don’t believe the stock will beat the market over the coming five years, and if I owned it in my portfolio today, it might be time to part ways.
3. Cellebrite’s Growth Outlook is Hazy
Lou Whiteman
Team Hidden Gems
Cellebrite (CLBT -3.08%) has an amazing product: technology that allows law enforcement and other users to extract digital evidence from encrypted devices. Alas, it has yet to establish itself as an amazing stock.
I see the bull case here. Customers rely on the product and are likely to renew out of necessity, generating a loyal base and predictable recurring revenue. But government budgets are slow-moving, and a few large contracts can swing a quarter. Encryption keeps tightening, creating ongoing costs to stay ahead of the latest standards. And public scrutiny of how the tools are used creates reputational risk.
Wall Street rewards growth. Axon Enterprises (AXON -6.45%), the stock Cellebrite is most often compared to, has been a winner because of its ability to repeatedly layer new offerings to its established base. Cellebrite, so far, has not shown the same ability, and with Axon occupying so much of the niche, there are fewer lanes for expansion.
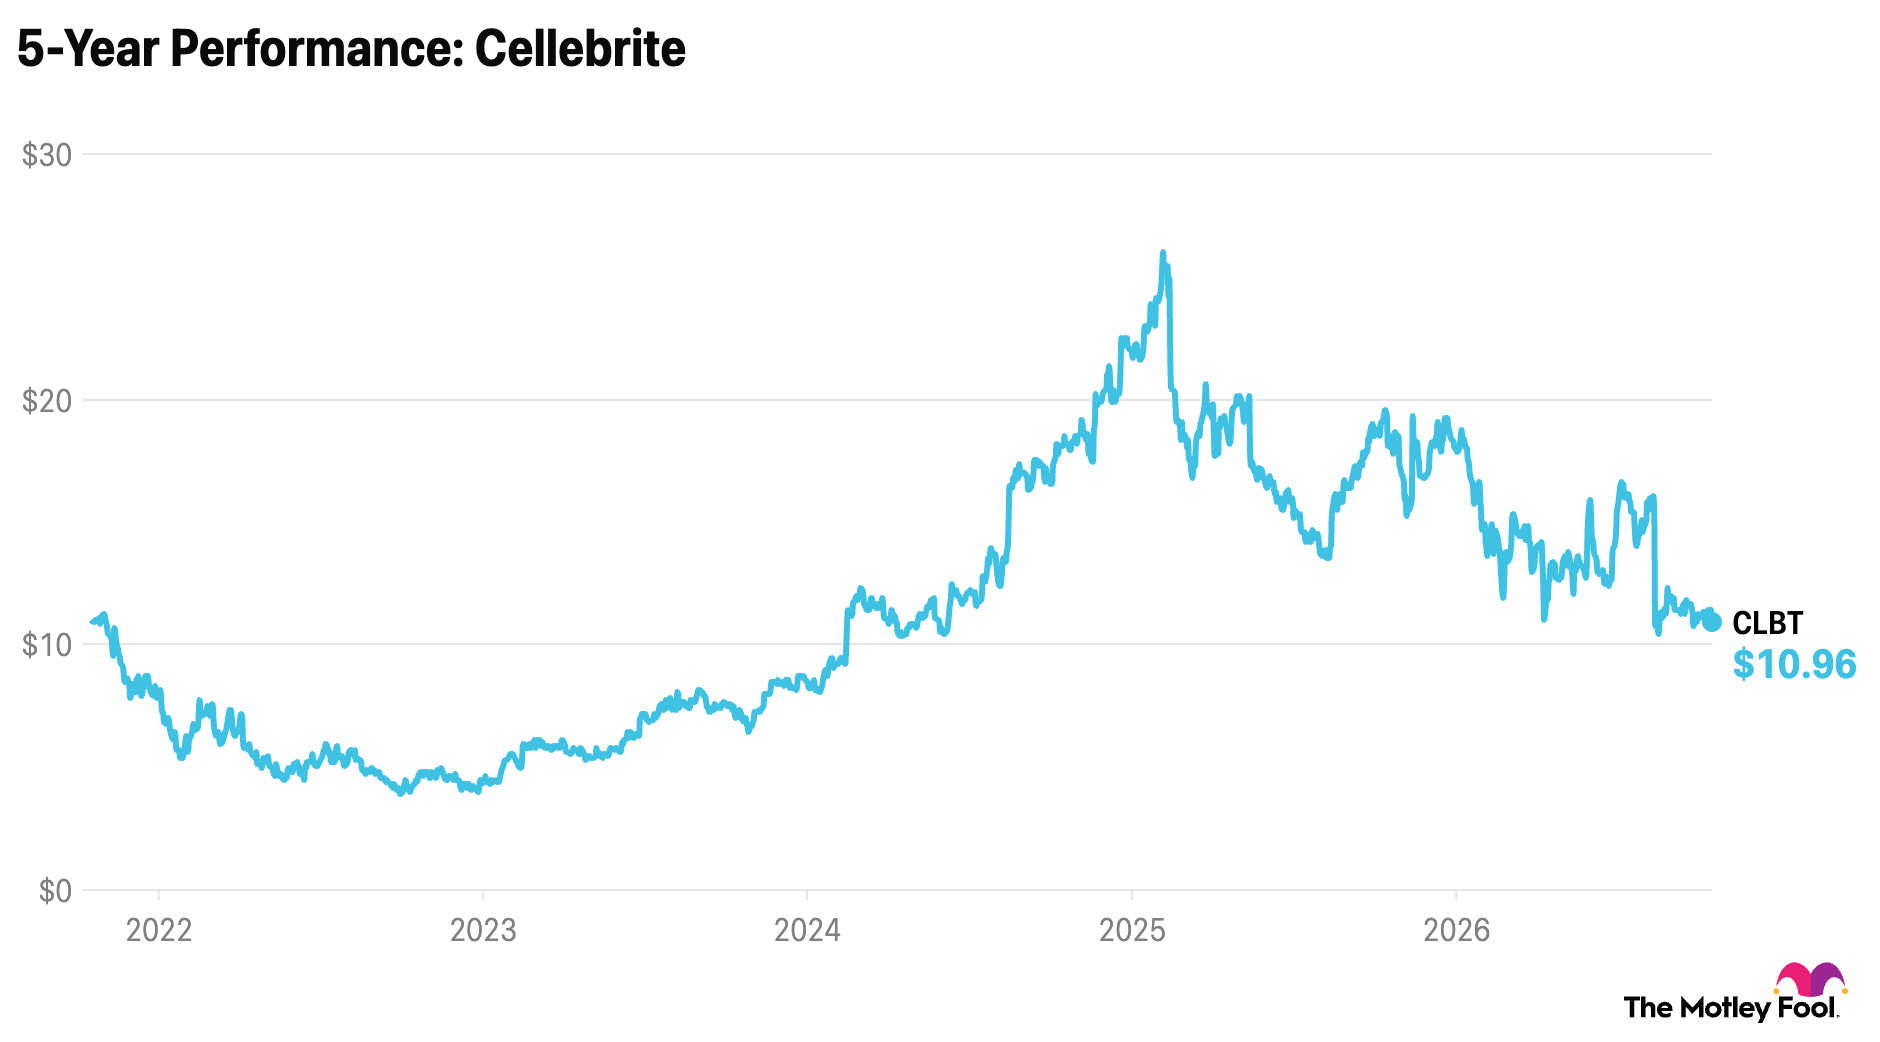
I don’t see a risk of Cellebrite going away, but I’m also hard-pressed to see how this stock delivers market-beating growth over time. With that in mind, I’d rather deploy my capital elsewhere.
4. Workday Faces AI, Market Headwinds
Andy Cross
Motley Fool CIO
For shareholders like me, it’s been nice to see the stock of Workday (WDAY -2.96%) rebound from its spring lows of the Saaspocalypse days. That 75% bump might be the time to take those chips off the table.
While the steepness of that sell-off was a bit drastic, I don’t think the spirit was misaligned. The power of AI models, from Anthropic and others, including open source models, gets stronger with every release.
Workday has been plowing ample cash into its own AI and agentic solutions that are showing an impact. At its recent investor day the company announced that AI tie-ins make up 50% of recurring revenue, with a goal of moving that to 70% by next year.
Co-founder and former CEO Aneel Bhusri stepped back in as CEO earlier this year after Workday parted ways with its prior CEO.
But I’m not convinced Workday will be an ultimate long-term winner. It’s not just because of AI disruption, because it is building real tools into the platform. But margins might come under pressure (though no real signs yet), competitive start-ups emerge, and budgets shift from complex HR/finance systems to AI and home-grown solutions.
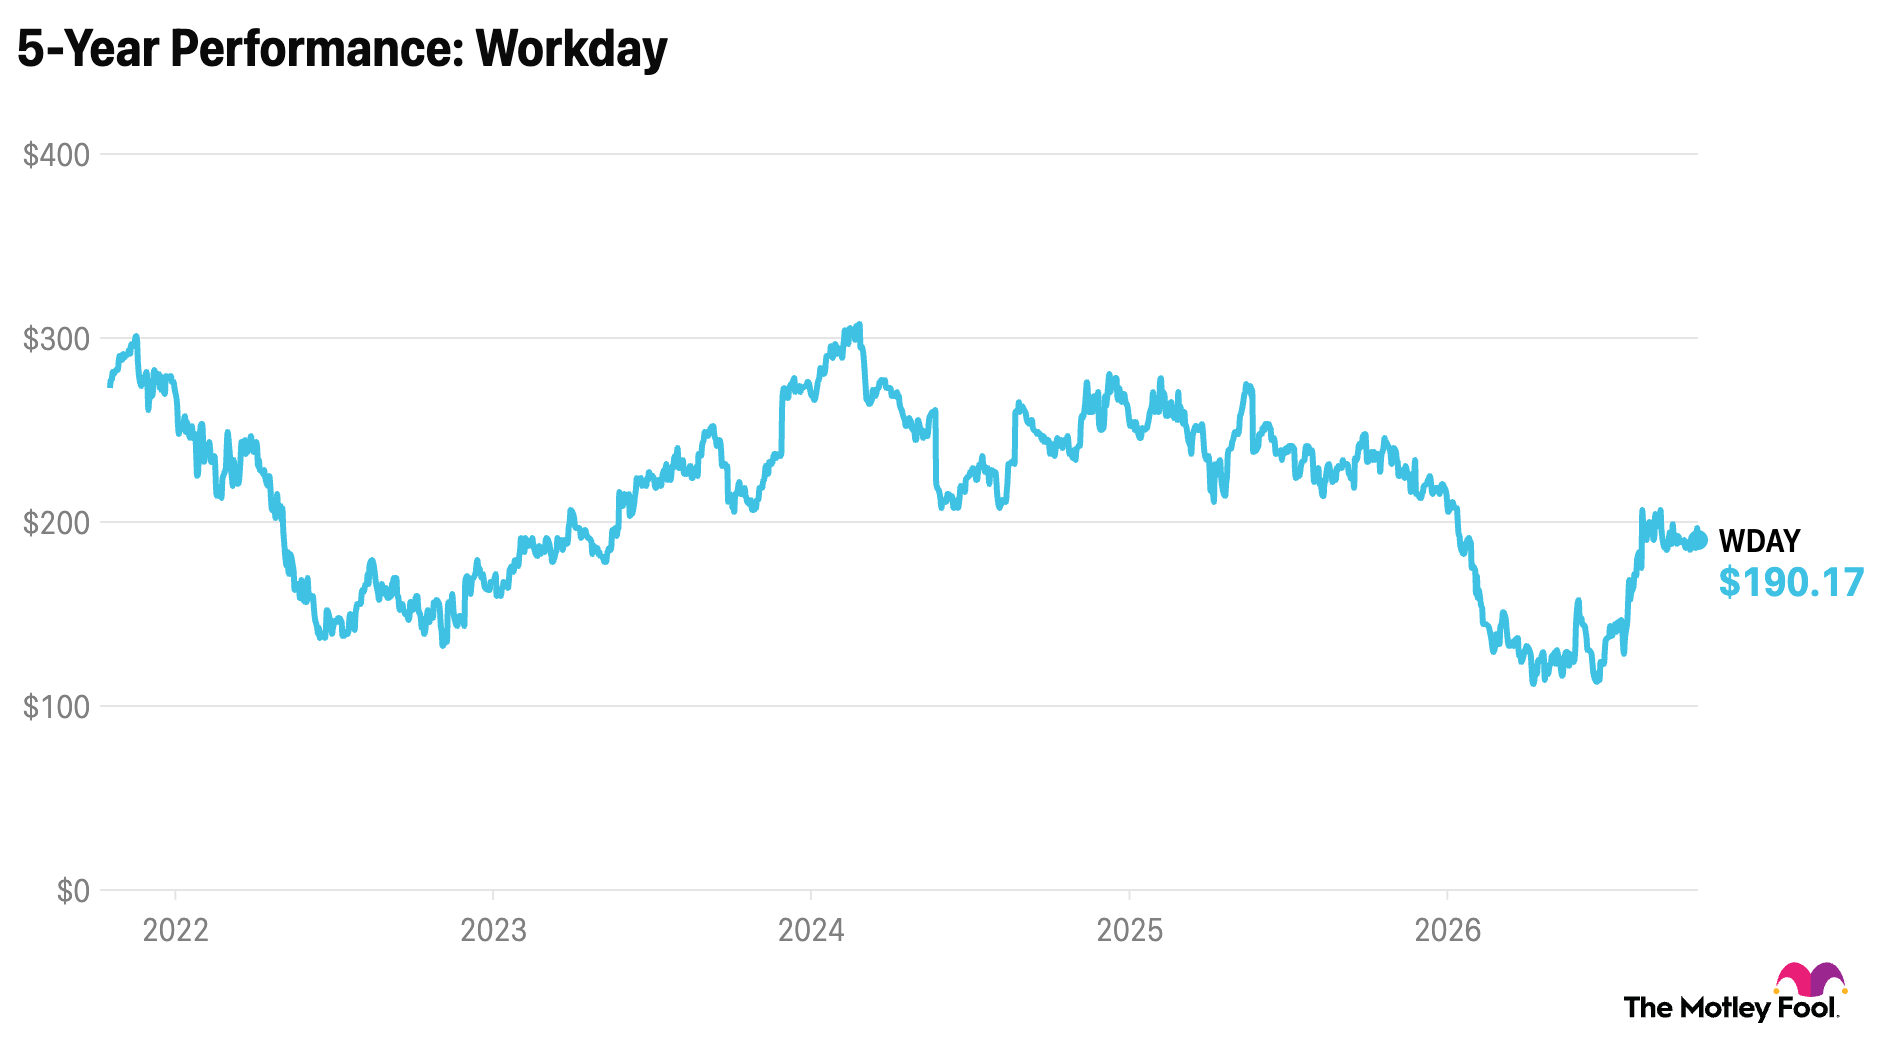
I think the stock could continue to recover but not be a significant market-beater. I’m expecting more like 6% to 8% growth per year, or a stock between $250 and $280 within five years.
5. The Foolish Bottom Line
Letting go of a stock can be hard, particularly one that’s done well for you in the past. Yet loyalty is a poor reason to hold something if the underlying thesis has evidently changed. Every so often, ask yourself if you’d buy this stock today for the reason you bought it in the first place. If the answer is no, that money can probably work harder somewhere else.
As a reminder, none of these insights above are sell recommendations, and our analysts may not always agree with one another. Treat this commentary as a push to run the test yourself. If your original thesis for buying no longer holds, that money may be better spent elsewhere.
6. Today’s Question!
Is there a stock you know you should sell, but you keep talking yourself out of it? What’s holding you back?
Discuss with friends and family, or become a member to hear what your fellow Fools are saying!