Why a higher salary may not improve your financial security: 5 money habits that can eat into your savings every month
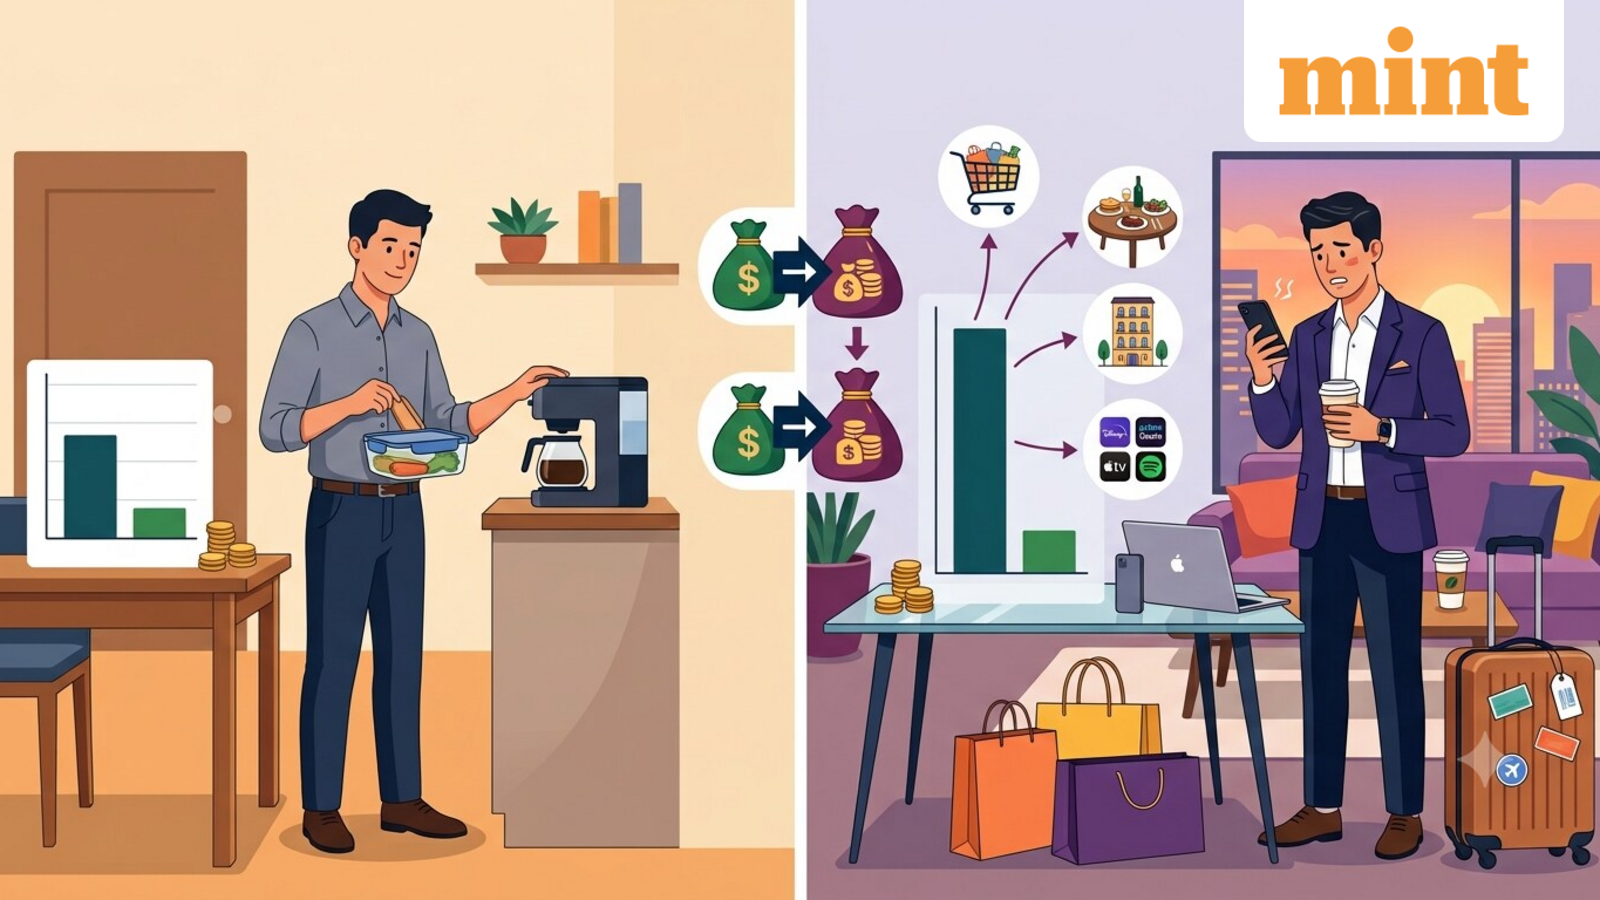
A salary hike is often seen as a step towards financial security, but higher earnings do not always translate into higher savings. As young professionals earn more, rising rent, lifestyle expenses and discretionary spending can absorb much of the additional income, leaving little money to build a financial cushion.
The problem is not necessarily how much a person earns, but how they manage the money that comes in each month. Uttam Agarwal, chief business officer at BajajCapital – La Premièr, said lifestyle expenses often rise alongside income as young professionals spend more on better housing, convenience, travel and new experiences.
The challenge arises when spending increases without a corresponding rise in savings and investments. Here are five money habits that can prevent young professionals from building wealth even as their salaries grow.
1. Allowing lifestyle expenses to rise with every salary hike
A higher income can make it easier to upgrade housing, eat out more often, travel frequently and pay for greater convenience. These expenses may be manageable individually, but together they can consume a large share of a salary increase.
In metro cities, rent can already account for a substantial part of monthly income. Add food deliveries, subscriptions, shopping and other discretionary expenses, and the additional earnings may leave little surplus.
The problem is not necessarily spending more as income grows. It is allowing expenses to rise so much that the amount saved remains unchanged.
Agarwal said the key is to ensure that spending does not increase without a corresponding increase in savings. Young professionals can allow themselves some lifestyle upgrades while directing part of every salary hike towards their financial goals.
2. Saving only what is left at the end of the month
One common mistake is to spend first and save whatever remains. This makes savings dependent on how much is left after monthly expenses, which can fluctuate considerably.
A more consistent approach is to set aside a predetermined amount for savings and investments at the beginning of the month, then plan spending around the remaining income.
Agarwal recommends that working professionals aim to save and invest around 20-30% of their monthly take-home pay, depending on their financial obligations and lifestyle.
For someone earning ₹1 lakh a month, this would mean targeting savings and investments of ₹20,000 to ₹30,000. Those who cannot initially set aside that much can begin with a smaller amount and gradually increase it as their earnings grow.
The objective is to make saving a regular part of monthly financial decisions rather than something that happens only when expenses are unusually low.
3. Underestimating the impact of recurring expenses
Rent, loan EMIs, food deliveries, subscriptions, eating out and credit card expenses can gradually reduce the amount available for savings. Because many of these payments are spread across the month, it can be difficult to see how much they add up to.
A higher salary can create the impression that there is more room to spend, even when fixed commitments have already consumed a significant share of income.
Tracking monthly expenses can help identify where money is going and which costs are taking up more of the budget than expected. This does not mean eliminating every discretionary expense. Instead, the aim is to understand how recurring costs affect the amount available for savings and investments.
The balance becomes particularly important when taking on new fixed commitments, such as a higher rent or an additional loan EMI, that may continue for years.
4. Neglecting an emergency fund
Building wealth is difficult if unexpected expenses repeatedly force a person to dip into long-term savings or borrow money. Medical bills, family responsibilities and temporary interruptions to income can put pressure on even a well-managed budget.
Agarwal recommends maintaining an emergency fund covering at least six months of essential expenses. This reserve can help individuals manage unexpected financial needs without immediately disrupting their regular investments or relying on expensive borrowing.
Adequate health insurance and term insurance, where needed, can also help protect finances against unforeseen events.
For young professionals, these safeguards are important alongside regular investing. An emergency fund may not generate the same excitement as investing for long-term goals, but it provides a financial cushion when income or expenses change unexpectedly.
5. Treating savings as a burden instead of a long-term habit
Trying to save an aggressive share of income immediately can be difficult, particularly for young professionals managing rent and other living expenses. If the target leaves too little room for everyday needs and personal interests, it may become difficult to sustain.
Agarwal suggests starting with an achievable savings amount and increasing it gradually as income rises. For a 25-year-old, saving around 20% of monthly take-home pay can be a starting point, with the aim of moving towards 25-30% as earnings grow.
Time can work in a young investor’s favour, as consistent investments made over a longer period can contribute towards long-term financial goals. However, financial discipline need not mean giving up every experience or lifestyle choice.
Agarwal said the aim is to balance enjoying life today with securing one’s financial future. As salaries increase, young professionals can direct part of each increment towards savings while allowing some room for lifestyle improvements.