ARMs, non-QM are the 4Q opportunities, rate lock data says
Processing Content
- Key Insight: Why lenders should pivot toward non-QM and adjustable-rate mortgages.
- Expert Quote: “Purchase demand… may not fit into the traditional conforming box.” — Brennan O’Connell, Optimal Blue
- Forward Look: On the horizon: Record-breaking non-QM issuance expected in the fourth quarter and 2027.
Overview bullets generated by AI with editorial review.
High mortgage rates during September were largely responsible for a 26% drop in rate lock activity during the month compared to a year earlier.
But a pair of products benefitted from those elevated rates. Non-qualified mortgage locks grew 8% versus August, while adjustable rate mortgages recorded their highest share since Optimal Blue started its Market Advantage reports in 2019. Rates
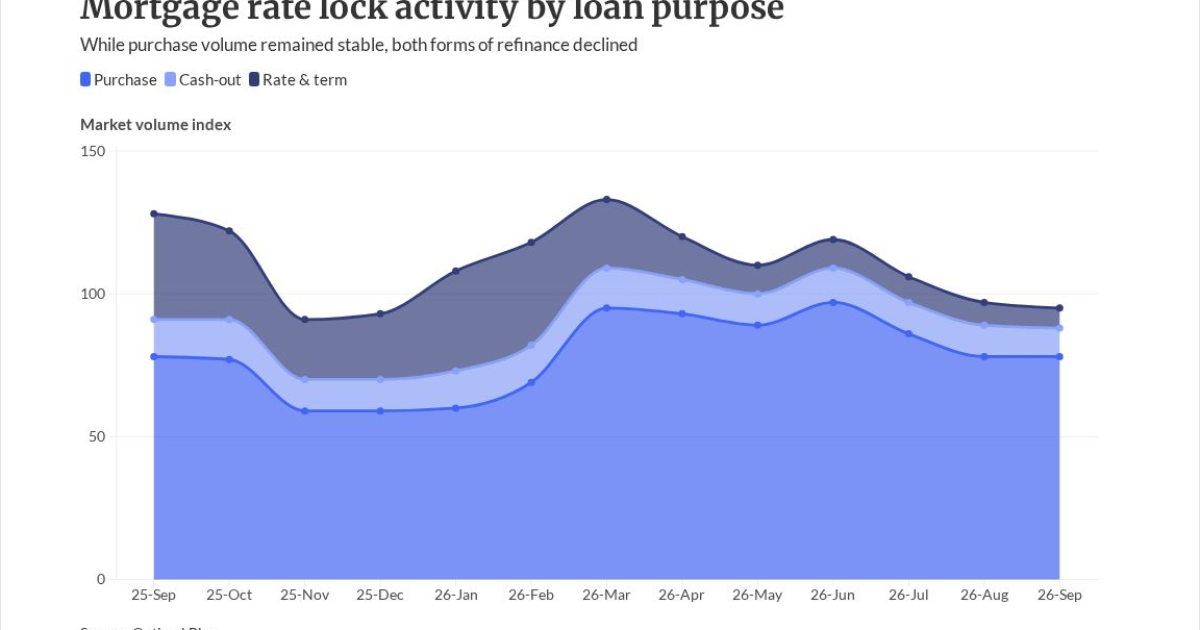
September’s Market Volume Index of 94
The purchase component was virtually unchanged with both the prior month and previous year. But rate-and-term refinancings were down 82% from September 2025, and the market reported 23% fewer cash-out locks.
“What stands out in September is how much product mix is doing the work of keeping purchase activity moving,” said Brennan O’Connell, director of data solutions at Optimal Blue, in a press release. “Conforming lost share while non-QM volume grew and ARM usage reached its highest level seen in our report. That tells lenders there is still purchase demand to serve, but increasingly it may not fit neatly into the traditional conforming box.”
Nonconforming mortgages, where Optimal Blue reports non-QM data, had a 23.6% share in September. Conforming was less than half of the total volume at 46.2%.
Loans the Federal Housing Administration insured had an 18.4% share of the market, followed by mortgages the Department of Veterans Affairs guaranteed at 11.1%. U.S. Department of Agriculture products made up just 0.7% of locks.
Meanwhile, ARMs reached 14% of total lock volume in September, up from 10.5% in August
“In this rate environment, production opportunity is going to depend in part on how broadly lenders can meet borrowers across different credit, income and payment scenarios,” O’Connell said.
The latest Mortgage Bankers Association Weekly Application Survey had ARM volume at 10.5%,
Its data found the 30-year conforming fixed-rate mortgage averaged 7.5%, marking its highest level since November 2023.
“As a result, borrowers continue to rely more on ARM loans to help lower their monthly payments,” said Joel Kan, deputy chief economist, in a press release. “The ARM share was at its highest level since October 2025.”
Meanwhile, the latest non-agency weekly report from Bank of America Securities said the non-QM wave is not abating soon.
“Despite
So far this year, $80 billion of non-QM has been securitized, of which $33 billion came from 2025 production. This means a significant amount of this year’s projected $175 billion in total non-QM production will come to the securitization market before the end of the year and in 2027, Bank of America Securities said.