Gold vs equity vs real estate: How much would ₹1 lakh invested 20 years ago be worth today? Gold leads the pack
When deciding where to invest, people often compare equity, gold, debt and real estate based on their recent performance. But the longer-term picture can look very different, as returns vary across asset classes and the leader in one period may not remain the best performer in another.
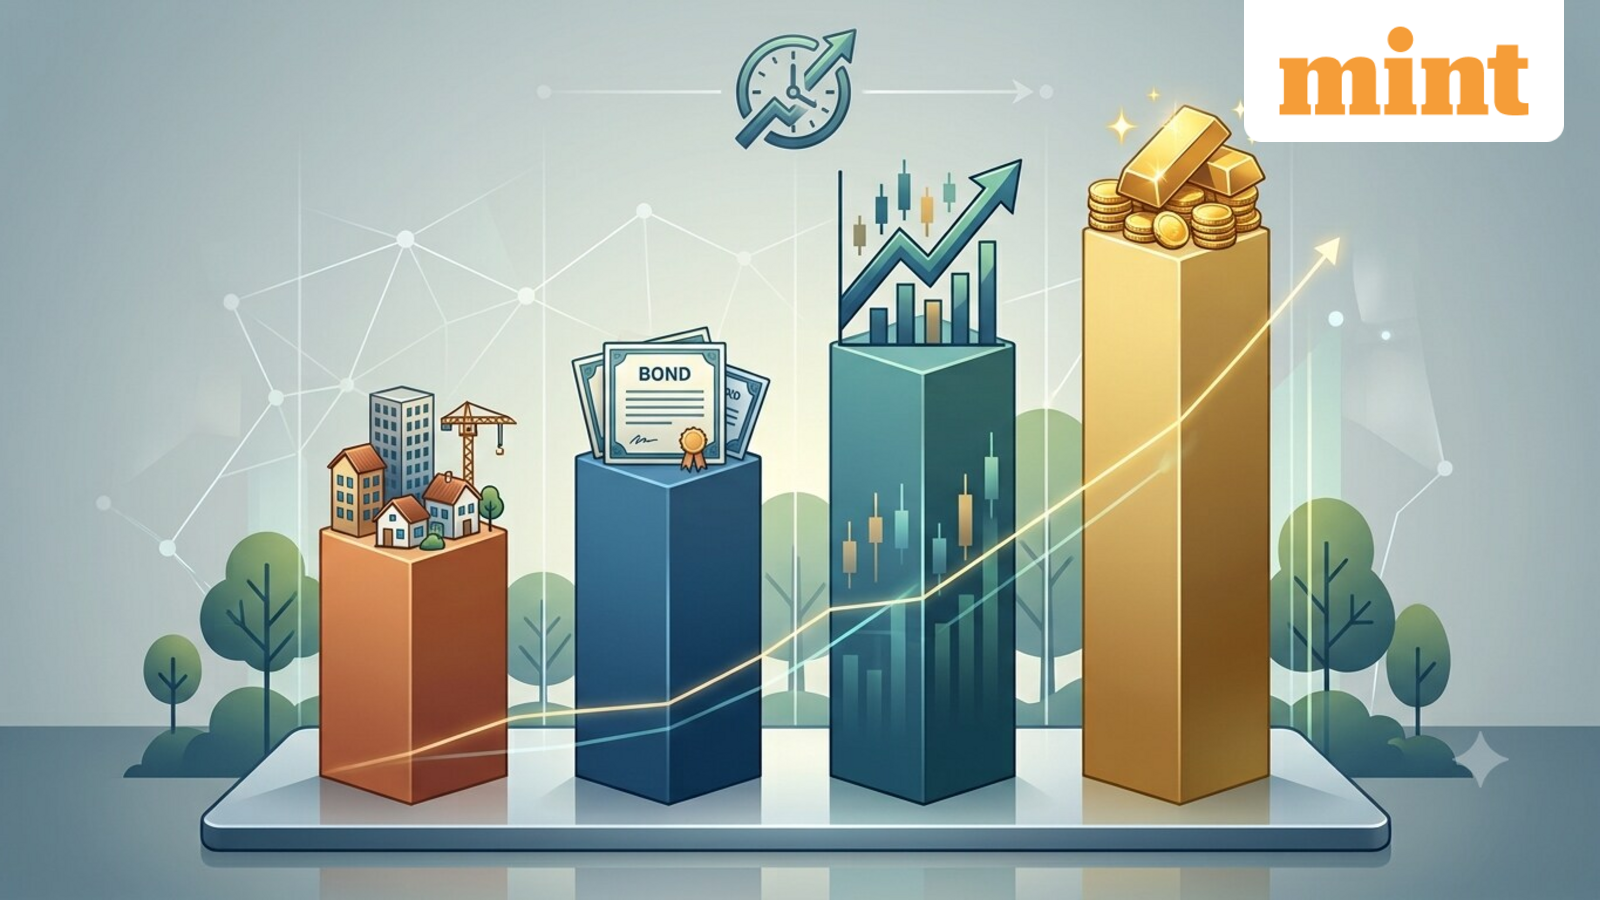
A 20-year comparison by FundsIndia, using data as of 30 September 2026, shows how differently these investments have grown. An investment of ₹1 lakh in gold would have grown to ₹14.6 lakh, compared with ₹8 lakh in Indian equities. Debt and real estate delivered lower growth over the same period, with ₹1 lakh growing to around ₹4.3 lakh and ₹4.2 lakh, respectively.
The comparison offers a perspective on how different assets have performed over the long term. However, historical returns do not guarantee future performance, and the figures should be read in the context of how each asset class is measured.
How ₹1 lakh grew across asset classes in 20 years
|
Asset class |
Annualised return |
Value of ₹1 lakh after 20 years |
| Gold | 14.3% | ₹14.6 lakh |
| Indian equity | 11.0% | ₹8 lakh |
| Debt | 7.5% | ₹4.3 lakh |
| Real estate | 7.5% | ₹4.2 lakh |
| Source: FundsIndia’s October 2026 report. Data as of 30 September 2026, except real estate, which is updated through June 2026. Values are based on the report’s rounded wealth multiples. | ||
Gold delivered the highest annualised return among the four asset classes over this period. Its 14.3% annualised return translated into a 14.6-fold increase in wealth. Indian equities returned 11% annually, turning ₹1 lakh into approximately ₹8 lakh.
Debt and real estate generated annualised returns of 7.5% each. The report estimates that ₹1 lakh invested in debt would have grown to ₹4.3 lakh, while the same investment in real estate would have grown to ₹4.2 lakh.
These figures show the difference that variations in annualised returns can make over two decades. Even a few percentage points of difference, compounded over a long period, can lead to a substantial gap in the final investment value.
What the numbers tell investors
Gold outperformed Indian equities over this particular 20-year period, but that does not establish gold as the better investment for every investor or every time horizon. Returns depend on the period measured, and leadership among asset classes can change from year to year.
Indian equity returns in the comparison are based on the Nifty 50 Total Return Index (TRI), which accounts for dividends reinvested in the index. The debt figure is based on a calibrated index using selected low-duration and corporate bond funds.
The real estate estimate is based on the National Housing Bank’s Residex property price index. It tracks property-price movements and is not the net return earned by an individual homeowner. It does not account for factors such as rental income, maintenance, transaction costs or taxes, so actual property returns can differ.
Should investors change their asset allocation?
The comparison highlights the importance of looking beyond the most recent market performance when building a portfolio. Gold has delivered the strongest returns among these four asset classes over the period studied, but investors should not shift their entire portfolio towards it based only on historical returns.
Equities can play a role in long-term growth, but they are exposed to market volatility and can experience prolonged periods of weak performance. Debt investments can provide stability and serve different income or liquidity needs, depending on the instrument. Gold can diversify a portfolio, while real estate involves higher transaction costs and is generally less liquid than listed financial investments.
The appropriate allocation depends on an investor’s financial goals, investment horizon, ability to withstand losses and need for liquidity. Rather than trying to identify the next best-performing asset, investors should consider how different investments work together in a diversified portfolio.