UPI MDR: From 0.40% to 0.08% what IIT Bombay report has proposed and why it wants new fee structure, explained
A technical report by researchers associated with IIT Bombay has warned that the revised merchant discount rate (MDR) on select UPI transactions could indirectly burden customers and proposed changes to the government’s fee model, ANI reported today.
While estimating that the MDR framework could generate about ₹18,000 crore annually for payment service providers, the report argued that customers may feel the burden through higher retail prices, despite merchants being barred from directly passing on the charges.
The report titled ‘UPI at a Crossroads: Reintroducing the MDR’ warned that businesses may incorporate the additional expense into their general selling prices to protect profit margins, potentially making even customers undertaking transactions below ₹2,000 bear part of the cost, the report added.
“UPI may lose public trust if it is floated as per the presently proposed MDR framework,” the report said, adding that the framework must be “tweaked and rationalised before implementation”.
Argument against MDR on UPI: What IIT Bombay says
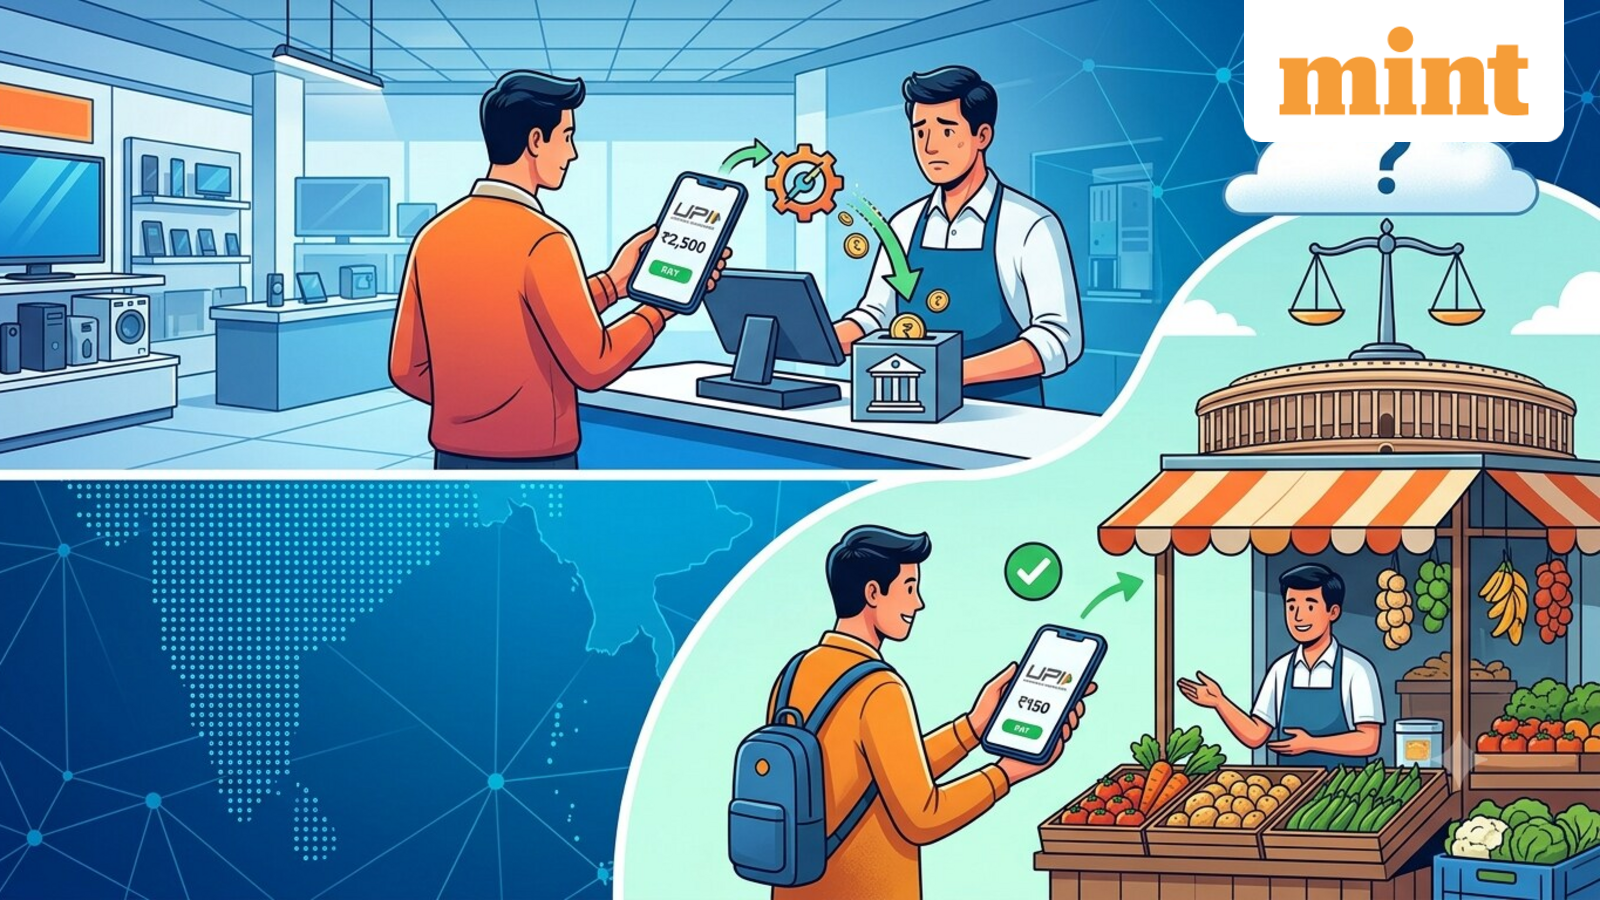
Under the revised framework, merchant payments above ₹2,000 can attract an MDR of up to 0.40%, capped at ₹300 per transaction. Person-to-person (P2P) transfers and merchant payments up to ₹2,000 remain free.
Certain essential-sector transactions attract a flat fee of ₹5, while capital market transactions carry a charge of 0.02 per cent, subject to a ₹300 cap.
- The report also highlighted the contrast between charging for digital payments and maintaining free ATM withdrawals, despite the high cost of currency management.
UPI MDR: From 0.40% to 0.08% what is proposed
The report recommends restricting charges to online merchants and businesses with annual turnover above ₹50 crore, capping percentage-based MDR at ₹40 and directing revenue towards the continued expansion and security of UPI.
- To run and improve the UPI ecosystem, banks should carve out, say, about 3% of the funds ( ₹15,000 crore) sacrificed by CASA depositors and not rely on MDR revenue sharing, it added.
- The paper argued that there appears to be “no rationale for the credit card’s MDR model to be used for UPI” and added that if the ‘ad valorem’ is adopted for UPI, the maximum cap should not exceed ₹40 per transaction.
- It added that remuneration for the UPI ecosystem can be harnessed by restricting it only to merchants with annual turnover of over ₹50 crore (about 4 crore per month), it said, adding that this would account for about 90 per cent of NPCI’s proposed MDR.
- “There is a potential for NPCI to introduce a reasonable charge on merchants, within the legal mandate, across all online person-to-merchant (P2M) UPI transactions,” it noted.
(With inputs from Agencies)