Live a little: how to cash in on the “experience economy”
The rise of the so-called “experience economy” offers a welcome alternative to our increasingly digitised life. It promises highly curated, in-person experiences offering the sense of community and direct physical engagement with the world that has been stripped from the daily rhythms of life.
It is a truism that people’s lives are increasingly digitalised, but the data still retains the capacity to shock. UK adults spent 4.5 hours per day online in 2025, according to Ofcom. For 18-to-24-year-olds, the figure was six hours and 20 minutes, mostly on their smartphones. And it’s not as though we are spending these digitalised lives with others. A significant number of people work remotely, at least some of the time. Over 40% of UK workers spend part of their week working from home.
More unsettlingly, when we are online, we often consume content that isn’t even generated by a fellow human being. The marketing platform Ahrefs recently conducted a remarkable study showing that almost 75% of new websites contained significant AI-generated content. The machines aren’t just delivering entertainment; they’re creating it.
But as investors, we know that when something becomes abundant – screen time, digital content, isolation – something else becomes scarcer, and, typically, more valuable. Today, some of that scarcity seems to be migrating towards the experience economy.
An “experience” might be a trip to a concert or a sports match. It might be dining at a restaurant whose kitchen offers a special menu, or taking a trip to a beach with the softest sand and the bluest water. This isn’t new. Business strategists Joseph Pine and James Gilmore coined the phrase “experience economy” in 1998, with the idea that companies could command pricing power through events that engaged consumers on a memorable, emotional level. But the forces that created the need for such an economy have only become stronger over the last quarter of a century.
What is the experience economy?
The evidence for an experiential boom in spending is already widespread. In its 2026 State of the Consumer report, consultancy McKinsey highlighted that the global experiences market between 2023 and 2025 grew more than three times faster than spending on non-essential goods. Mastercard recently found that 88% of British consumers would be happy to redirect their spending on things towards experiences.
Michelle Evans, data group Euromonitor’s Global Lead on Retail & Digital Consumer Insights, says there is a broad rotation among consumers from “owning more to experiencing more”. The trend has been building for over a decade, but has accelerated since Covid.
It seems to be a reaction to digital saturation: “In an increasingly digital world, consumers are placing greater importance on experiences that improve wellbeing, create memories, strengthen relationships and feel genuinely human.” And young consumers, those most exposed to digital lives, are leading the rotation.
Live music and sports are among the purest embodiments of these experiential urges. Think of Taylor Swift’s Eras Tour, the 149-concert extravaganza in 2023 and 2024, which became an economic phenomenon in its own right. It was the most financially successful tour of all time, generating over $2 billion in direct box-office sales, more than twice its nearest rival.
How Swifties are fuelling the experience economy
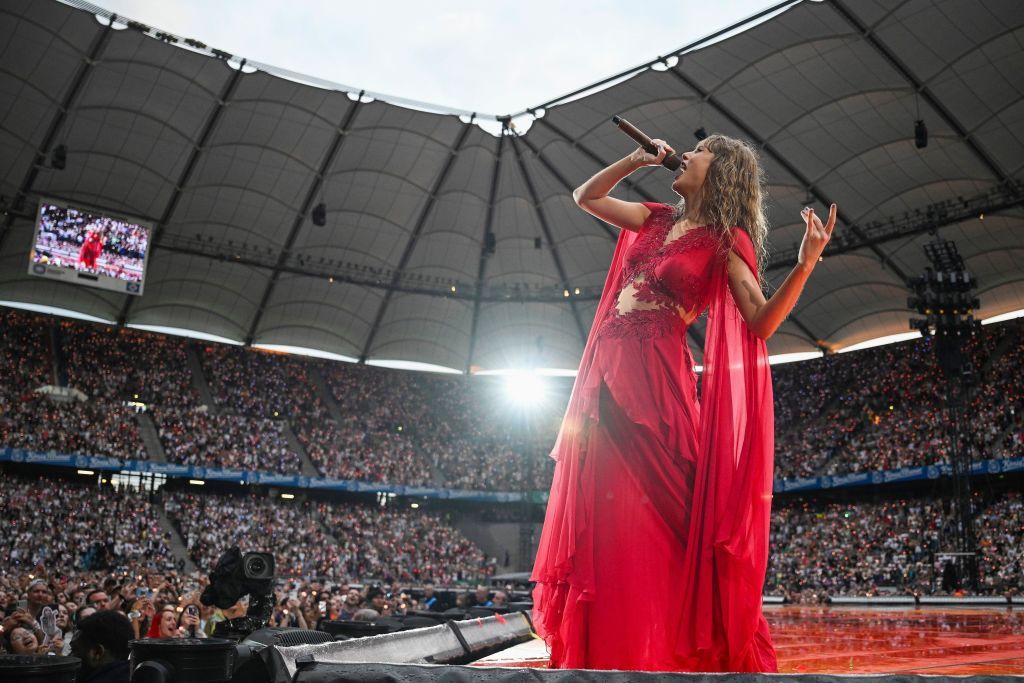
Twenty-two million people joined the virtual queue to buy tickets for Swift’s Singapore concert, almost four times the country’s population. The vast majority of these would-be attendees were planning to fly in from overseas; they were going on a musical pilgrimage. The quasi-religious nature of this fandom is underlined again by the fact that in Philadelphia over 20,000 ticketless fans stood outside the stadium during the concerts, night after night, just to be physically close to the Swiftian phenomenon.
A similar devotion characterises live sports. According to entertainment analytics firm Two Circles, 79.4 million fans attended ticketed professional sports events in the UK in 2025, 1.7 million more than the year before, and this despite a 5% increase in ticket prices. Attendance levels are far above pre-Covid figures.
When the Premier League first started, in the early 1990s, stadium utilisation rates sat at 70%. In the 2024-2025 season, that had risen to 98.8%. There is a sense in which attending a concert, or a Premier League match, is not just entertainment; it is a way for people to forge their identities and feel part of something larger than themselves.
This matters economically. AI may be able to commoditise digital content, but it cannot replicate the experience of standing next to 60,000 people at Anfield. “Travel, wellness, live events and community-based experiences all benefit from the fact that they are difficult to replicate digitally and often become more valuable as consumers spend more of their lives online,” says Evans.
Economist Alex Imas has argued that as AI makes some forms of production abundant, scarcity will not disappear, but will relocate towards what he calls the “relational sector”, where the human element itself contributes to the value of the product. As investors, we want to be in the businesses of monetising this relocated scarcity.
There are several ways we can invest in the experiential economy. Live Nation Entertainment (NYSE: LYV) is the world’s largest live-entertainment company, operating concert promotion, venues and ticketing services. It is positioned between consumers and the increasingly valuable experiences they are seeking. Concerns over competitive practices have dogged the stock. A federal jury earlier this year found it operated a monopoly, and it is unclear how this will be rectified.
The experience economy is safe from AI
However, the underlying business, protected by exclusive, multi-year venue and artist contracts, remains structurally difficult even for AI to disintermediate. The extraordinary demand for the sort of experiences it facilitates was illustrated by the collapse of Ticketmaster’s system under the weight of 3.5 billion ticket enquiries for Taylor Swift’s Eras Tour.
Airbnb (Nasdaq: ABNB), the world’s largest platform for booking alternative accommodation, is another interesting play on the experiential economy. The company has a valuable set of inventory consisting of millions of homes across the world, which it has spent almost 20 years building. While its product (accommodation) isn’t scarce, Airbnb’s value lies in facilitating the increasingly valued experience of global travel, taking a healthy commission in the process.
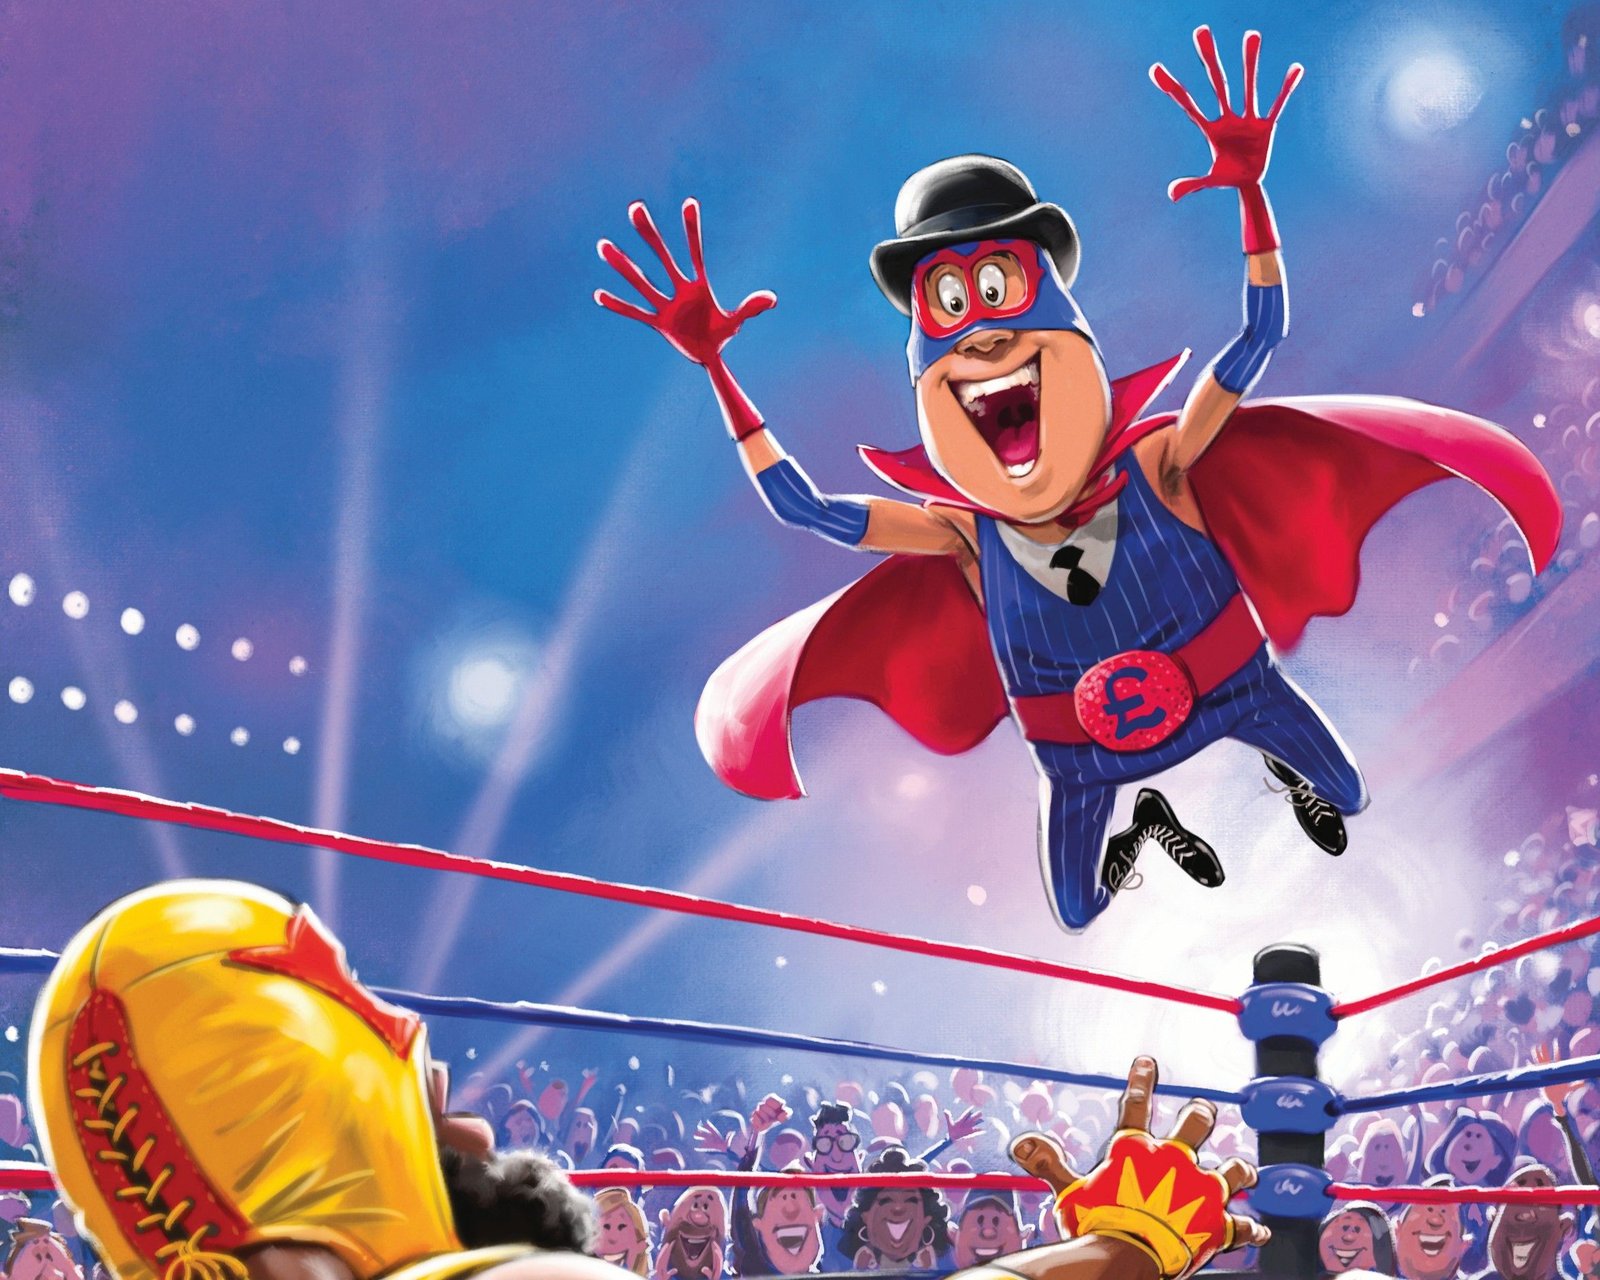
A third way to play consumers’ strong desire to invest in live experiences is TKO Group (NYSE: TKO), a firm roughly split between the UFC, the world’s leading mixed martial-arts business, and WWE, the dominant player in the world of professional wrestling. These distinct, but related, businesses are near-monopolies in their respective domains.
TKO Group differs from Airbnb or Live Nation. It is not an intermediary; it owns the product itself. Live sports are perfectly placed to resist the commoditising effects of AI. Their essence is that they are unique and occur in real time; even if you cannot be there in person, you must be sitting in front of a screen as the event unfolds. The fact that there is no algorithmic substitute for their product gives them low price sensitivity.
This article was first published in MoneyWeek’s magazine. Enjoy exclusive early access to news, opinion and analysis from our team of financial experts with a MoneyWeek subscription.