MBA: With 7% rates into 2027, win on revenue, not cost cuts
- Key Insight: Find out how the MBA is shifting their expectations for 2027.
- What’s at Stake: Smaller mortgage players face a widening profitability gap against their top competitors.
- Expert Quote: “There are real risks that we get a significant slowdown.” — Mike Fratantoni, MBA
Overview bullets generated by AI with editorial review.
Processing Content
Even the economists at the Mortgage Bankers Association, seen by some as the most optimistic of home lending forecasters, predict a tough road ahead for the industry.
Expecting two more hikes from the Federal Reserve, one in December and one sometime in the first quarter of 2027, the trade group’s latest outlook sees 7% mortgage rates for the full year of 2027, with originations decreasing by 5% over this time.
With rates for the 30-year-fixed expected to remain elevated, the MBA at its annual conference in Chicago Sunday night announced that it will be publishing more detailed numbers on adjustable rate mortgage share, which currently make up about 10% share of loan count and a 20% share of the dollar volume of business. The MBA expects
The organization is calling for just under $2 trillion in volume next year. This includes a 0.8% year-over-year increase in purchase activity to $1.42 trillion. But refinance originations will decline by 17% in the high interest rate environment to $571 billion.
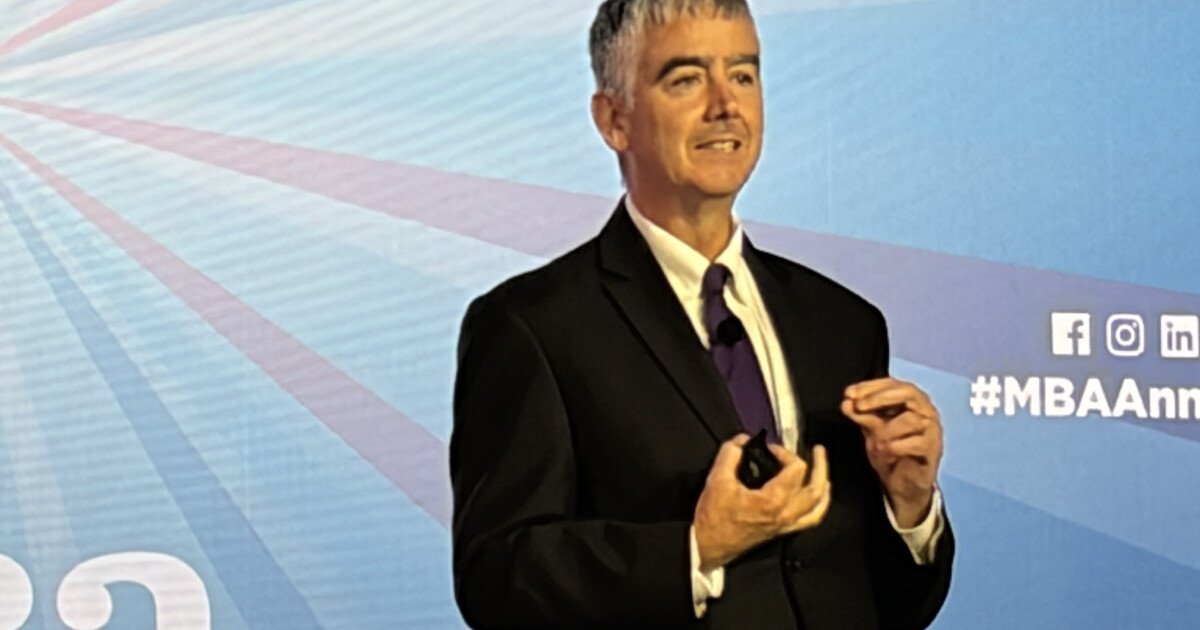
The likelihood of an economic downtown was also up significantly, according to MBA Chief Economist Mike Fratantoni, who detailed the organization’s response to a Wall Street Journal survey about economic expectations.

Heidi Patalano/National Mortgage News
“Even in reasonably good times, we give an answer like 15, 20%” for a chance of recession, he said. “The most recent answer we gave was 35%. There are real risks that we get a significant slowdown.”
MBA expects the 10-year Treasury yield to ease to about 5% through 2027, but mortgage rates won’t follow it all the way down. At the close of trading on Oct. 9, this yield was 5.24%.
Fratantoni said the global rate volatility of recent weeks has raised prepayment risk, pushing the spread between mortgages and Treasuries back up to roughly 220 basis points after it spent much of this year near 200.
“I just don’t think investors are going to quickly forget this level of volatility that we’ve just lived through,” he said, adding that the MBA now expects the spread to stay wider than it had previously forecast.
The home equity opportunity
With roughly half of homeowners locked in at 4% rates or below,

Heidi Patalano/National Mortgage News
“Thinking about the…lack of a cash-out refi opportunity for many borrowers, this might be one of the few ways that they can tap equity going forward,” said Vice President and Deputy Chief Economist of the MBA, Joel Kan.
Who’s doing the most lending?
Out of the 4,600 entities making mortgages in the market now, the top 50 lenders in the country are doing half the business, said Marina Walsh, the MBA’s head of industry analysis.
About 175 independent lenders have disappeared over the last four-to-five years, but independents still hold about 67% to 68% of production market share, she added. The top 50 lenders account for only half of retail, wholesale, and consumer direct volume, so the remainder is spread across many smaller players.

Heidi Patalano/National Mortgage News
She noted that the profitability gap between top and bottom lenders comes mostly from revenue, not cost.
“The big difference, folks, is on the revenue side. Why is that? Due to
Independent mortgage banks have averaged positive net production income for five straight quarters, at about 25 basis points or roughly $775 per loan. That remains below the 39 basis point average since 2008.