Sunday Summary: Welcome Back, Speyer! – Commercial Observer
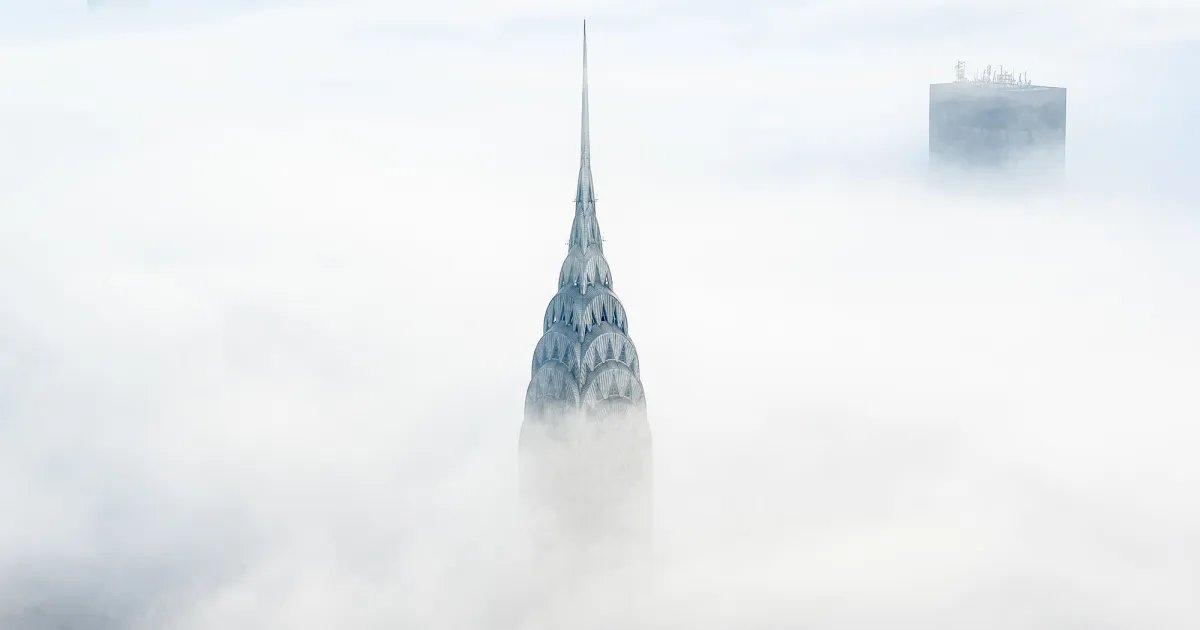
Back in 1997, one of the storied New York City real estate firms — Tishman Speyer — purchased one of the storied New York City properties: the Chrysler Building.
Well, technically, what Tishman Speyer purchased was the skyscraper’s ground lease. The site was still owned by Cooper Union. Moreover, it was a ground lease that would get progressively more expensive in the coming years. (Shrewdly, Tishman Speyer sold a 90 percent interest in the building to the Abu Dhabi Investment Council in 2008 for $800 million.)
When the property went up for sale again in 2019, expectations were significantly lowered about the value of the deal, given that the yearly payments to Cooper Union had by then ballooned from $7.8 million a year to $32.5 million.
Still, market observers figured Chrysler was iconic, eye-catching, centrally located and beloved enough to fetch at least $500 million. After all, how many other properties of such status go on the market every day?
But, when the ground rent was factored in, along with the fact that the property was in need of serious updates and repairs, the offers started coming in far, far lower than hoped for. The winning bid from RFR Realty was only $150 million.
However, even that discounted price might have been too much. It wasn’t long before RFR and Cooper Union began butting heads about missed rent payments, necessary improvements and more. (RFR also had the poor luck of closing the deal in 2019, just before the office market was about to go into deep freeze.) RFR was eventually pushed out, and Cooper Union began looking around again for a savior.
They apparently found one last week in the form of … Tishman Speyer?
How much Tishman paid is still unknown, but the preliminary details indicate that the new land lease will last 150 years, and Tishman is putting up $235 million for improvements to the property.
“We are pursuing an ambitious plan for the Chrysler Building at a historically strong moment for the Manhattan office market,” Rob Speyer said in a statement. “Just as we have done through new developments like The Spiral and our continuous reinvention of Rockefeller Center, we will create an environment that will make our customers proud and excited to work here every day.”
In the spirit of our inner-Vinnie Barbarino, we say to Mr. Speyer: Welcome back, welcome back, welcome back!
‘A historically strong moment’
Speyer is very much onto something when he said that the timing was right to make an investment in a Midtown office building.
Despite everything — record fuel prices, war in the Persian Gulf, tariffs, a jaggedly up-and-down Dow and Nasdaq, looming elections and more — the office market doesn’t seem to be in any danger of losing its mojo.
“There’s sort of two economies,” said Nicholas Farmakis of Savills. “There’s the asset-based economy, which New York kind of runs off of, and then there’s the average U.S. citizen economy. There may be a bit of a spread there, but as far as the folks in New York, on a macro basis, the economy is doing well. Consumer spending is relatively high. The stock markets are at or close to all-time highs. Venture funding continues to flow. There are a couple of sort of cloudy spots on the horizon as there always are, but as of now, everything’s firing on all cylinders.”
And that has redounded to New York office’s benefit: The volume of available space is at its lowest point since 2020. (If Morgan & Morgan’s 70,602-square-foot lease at 199 Water Street last week doesn’t impress you, what about Seward & Kissel’s 171,112-square-foot renewal at One Battery Park Plaza reported on Friday? Or Brex, the AI firm, taking 93,779 square feet at GFP Real Estate’s 200 Varick Street?)
Asking rents are up to $84.56 per square foot on average, and the seemingly distant figure of $400 per square foot was recently nearly reached. And nothing in the 7.9 million-square-foot pipeline of supply is coming online before 2028. (Plus, much of that new construction is already spoken for.)
This is the kind of data that explains why DRA Advisors is taking a 49 percent stake at 1301 Avenue of the Americas. (The recent deal with Rithm Capital valued the property at a whopping $1.3 billion.)
But, while much of the office world views this largely as a New York phenomenon, there have been stirrings in previously moribund markets on the West Coast, too.
While Los Angeles has been largely written off since COVID, investors are starting to see well-priced real estate that they’re finally willing to buy. “The overwhelming impression was that there are so many assets here, and this downtown was hopping along until the pandemic, and there’s no reason it can’t return and will return,” said Marilee Utter of Citiventure Associates.
Indeed, L.A. County just recorded the best quarter for office leasing since 2019, with 4 million square feet of space signed over the summer.
Just last week, Silverstein Properties announced some 55,349 square feet of deals at the U.S. Bank Tower in Downtown L.A.
But it’s not just office activity in Southern California. An affiliate of Nexus Development scored $276 million in refinancing for senior housing developments Vivante Newport Mesa and Vivante Newport Center in Newport Beach, Calif.
On a slightly less cheerful note, GEO Group got a $950 million payday for selling three detention centers in the Inland Empire to U.S. Immigration and Customs Enforcement (aka ICE).
And, in Orange County’s Huntington Beach, Westwood Financial plunked down $56.2 million for the grocery-anchored Peninsula Marketplace shopping center.
AI, AI oh!
Math nerds the world over were left dumbfounded last week by the announcement that OpenAI had solved mathematical equations that had bedeviled humanity for generations.
Hey — did you know that AI can also be used to efficiently schedule the meeting rooms at the office?
While perhaps not as ethereal as solving the “quasi-Riemann hypothesis” (don’t ask — we don’t know what this means, either) AI has become pretty much the lifeblood of proptech — and we see it running through all of this year’s Power Tech and AI list.
The list is a great collection of companies that have endeavored to integrate technology into real estate — and to pay for it.
Speaking of the latter, after going through Power Tech and AI, you should take the time on this long weekend to read our interview with one of the honorees: Fifth Wall’s Brendan Wallace. Wallace has been on the cutting edge for a lot of the companies that are remaking the market.
See you next week!