Applying for multiple loans in a week? Understand the impact on your credit report
When in need of borrowing funds, submitting several personal loan and credit card applications may seem completely harmless. Especially when the need for funds is urgent and required to meet a health emergency or another similar expenditure.
Still, it is vital for aspiring borrowers to keep in mind that when they submit several different credit applications, i.e., personal loan, home loan, or credit card applications, within a short period of time, such behaviour can adversely impact their credit profiles. This is because such a behaviour is carefully scrutinised by the lenders.
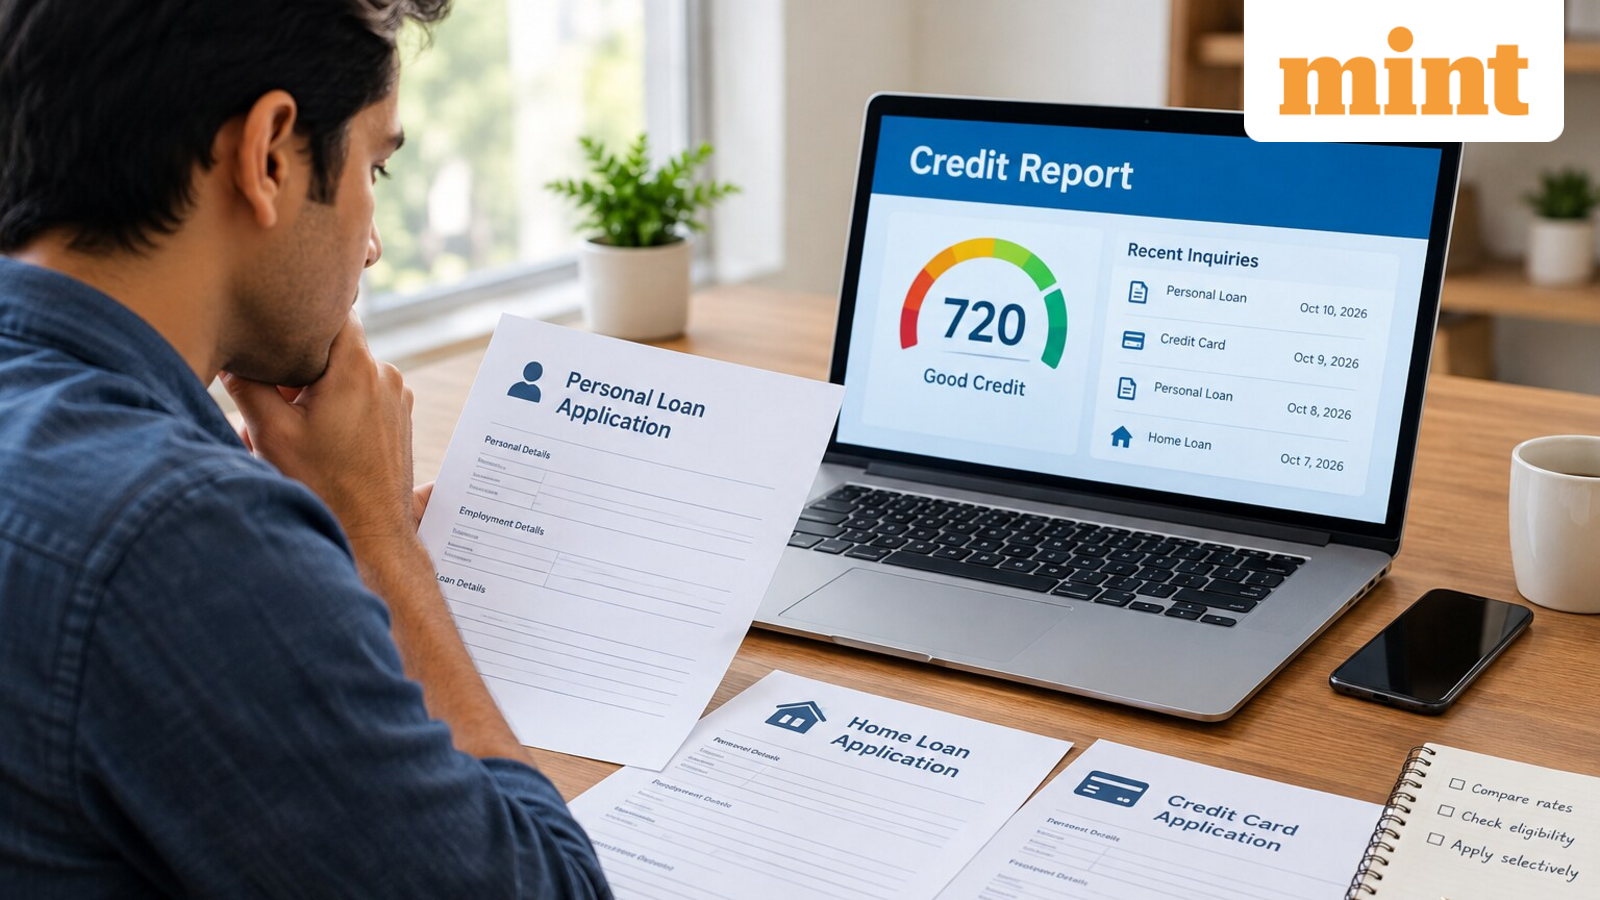
Every time you apply for credit, a lender may check your credit report, creating a hard inquiry. While a single inquiry usually has a limited impact, multiple inquiries in quick succession may raise concerns about your borrowing behaviour. It influences how lending institutions assess an individual’s repayment capacity.
Why multiple hard inquiries can concern lenders
Lending institutions analyse and assess several key factors when evaluating a new credit application. This includes repayment history of the applicant, total outstanding debt, credit utilisation, and recent borrowing activity. A cluster of hard inquiries within a week is a clear indication of the fact that the borrower is actively seeking fresh credit from multiple institutions and is ‘credit hungry.’
Now this does not automatically mean ‘financial trouble’ or distress or guaranteed rejection, lending institutions may interpret frequent applications as a sign of increased credit risk. Multiple hard checks can also result in a temporary dip in an individual’s credit score, although the impact depends entirely on the individual’s current credit score and the scoring model used.
Raj P. Narayanam, Founder & Executive Chairman, Zaggle, explained this in detail, stating, “Multiple hard inquiries within a short window send a clear signal to lenders, this borrower is actively seeking credit, possibly out of financial stress. Each inquiry shaves a few points off your score, and the cumulative effect compounds quickly. Lenders interpret a cluster of inquiries as elevated risk, even if each application was exploratory. The discipline is simple: research thoroughly, choose one lender and apply once. Your credit report is a reputation; protect it accordingly.”
It is vital to note that Zaggle’s consumer payments and credit card platform is Zaggle. money. Therefore, it is essential for aspiring borrowers to be careful and plan before submitting any new credit applications to protect their creditworthiness.
How to avoid unnecessary credit inquiries?
When you are planning to submit an application for fresh credit, never do it in haste. Carefully compare interest rates, processing fees, eligibility criteria and repayment terms. Furthermore, you should also be clear about the objective of the loan. Do you actually need it? How will you plan the repayment? These questions should be answered first to avoid panicking and submitting multiple credit applications.
You can also use the lending institutions’ eligibility calculators or pre-qualification facilities, where available. It is also wise to check whether such a process requires a hard check before initiating the application.
Avoid submitting multiple credit or debt request applications simply to improve your chances of approval. Instead, focus on strategic planning, shortlist suitable lenders and apply selectively. If you are denied credit, understand the reason before applying elsewhere.
In summary, responsible borrowing involves more than timely repayments. It involves showcasing consistent borrowing behaviour for years together. Limiting unnecessary hard inquiries can help protect your credit profile and present a more stable borrowing history to prospective lenders.