Parents funding your home down payment? Is the money tax-free, can it invite scrutiny, documents needed — FAQs answered
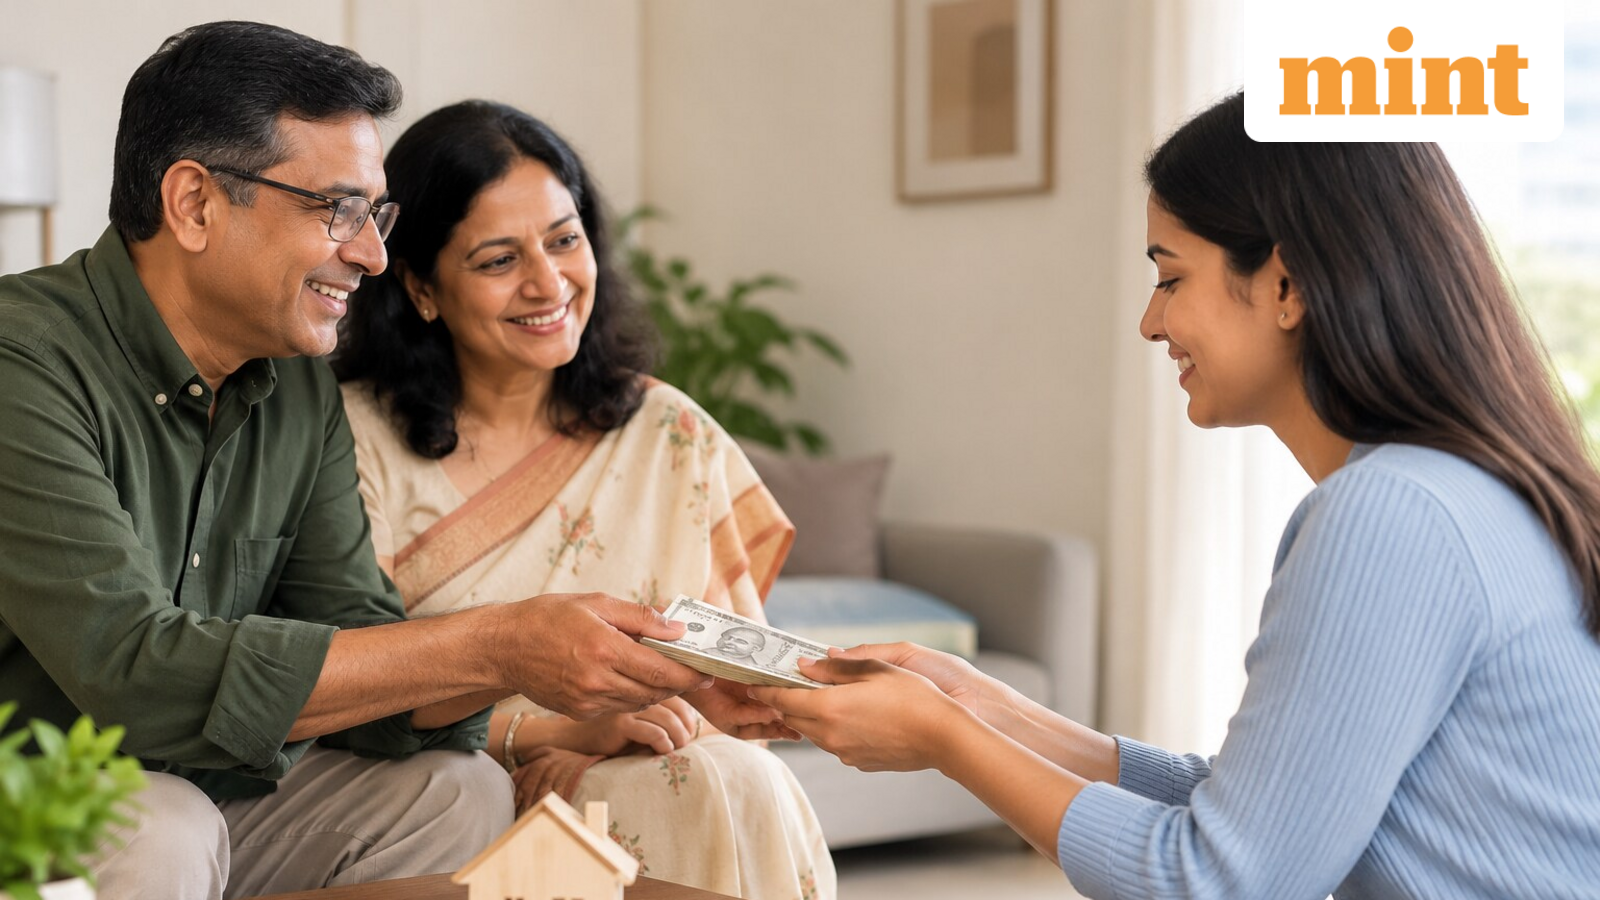
Purchasing a house is a major life goal for many Indians, but rising property prices and salaries that have not kept pace with it can make arranging the down payment challenging. This is when some young homebuyers may turn to their parents for financial support to bridge the gap.
The challenge is becoming more pronounced as affordable homes make up a shrinking share of the market. Homes priced below ₹50 lakh accounted for just 17% of housing supply in the first half of 2025, down from 52.4% in 2018, Livemint reported earlier, citing expert data.
A ₹50 lakh home could require around ₹12.5 lakh upfront, while a ₹75 lakh property may need ₹18.75 lakh and a ₹1 crore home around ₹25 lakh, including a 20% down payment and an allowance for other upfront costs, the report further stated. Actual expenses, however, vary by city and property type.
Is money gifted by parents tax-free?
Any monetary gift received from parents is considered tax-free in the recipient’s hands, regardless of the amount. This is because parents fall within the specified relatives category, under the Income Tax Act, 2025.
However, gifts received from non-relatives are taxable if their aggregate value exceeds ₹50,000 in a financial year. In such cases, the entire aggregate amount is taxable, not just the portion exceeding ₹50,000.
An exemption applies to gifts received on the occasion of the recipient’s own marriage, among other specified circumstances.
But, receiving a large sum from parents does not mean that the transaction can never attract questions from the income tax department. While such support can definitely ease the burden of arranging funds, a large transfer between family members can also raise questions about its source.
When can it attract tax scrutiny?
In India, when acquiring a property valued at ₹30 lakh or more, income the tax department mandates the registrar or sub-registrar to report the transaction under the Statement of Financial Transactions (SFT), as per income tax law.
This measure is implemented to counteract tax evasion and prevent money laundering activities. For instance, if a parent gifts you ₹30 lakh but cannot explain the source of the funds, the tax department may seek clarification.
What proof should the homebuyer keep?
To establish the genuineness of the transaction, homebuyers should keep the following documents handy as proof of the source and transfer of funds:
- Bank statements: Show the transfer from the parent’s account to the child’s account, preferably through formal banking channels.
- Proof of relationship: Keep documents such as a birth certificate or other records establishing the parent-child relationship.
- Parent’s source of funds: Retain relevant salary slips, bank statements, investment redemption records or other evidence showing where the money came from.
- Property payment trail: Keep the agreement for sale, home-loan documents and receipts showing how the gifted money was used for the down payment.
These records help establish the nature and source of the transaction if the income department asks questions later. If you are uncertain or have concerns regarding the declaration of the source of funds, it is advisable to seek advice from a qualified tax advisor for personalized guidance.
Upholding transparency and adhering to tax regulations is essential for prudent financial management and mitigating potential legal complications.