UK mortgage lending falls as lenders predict modest recovery
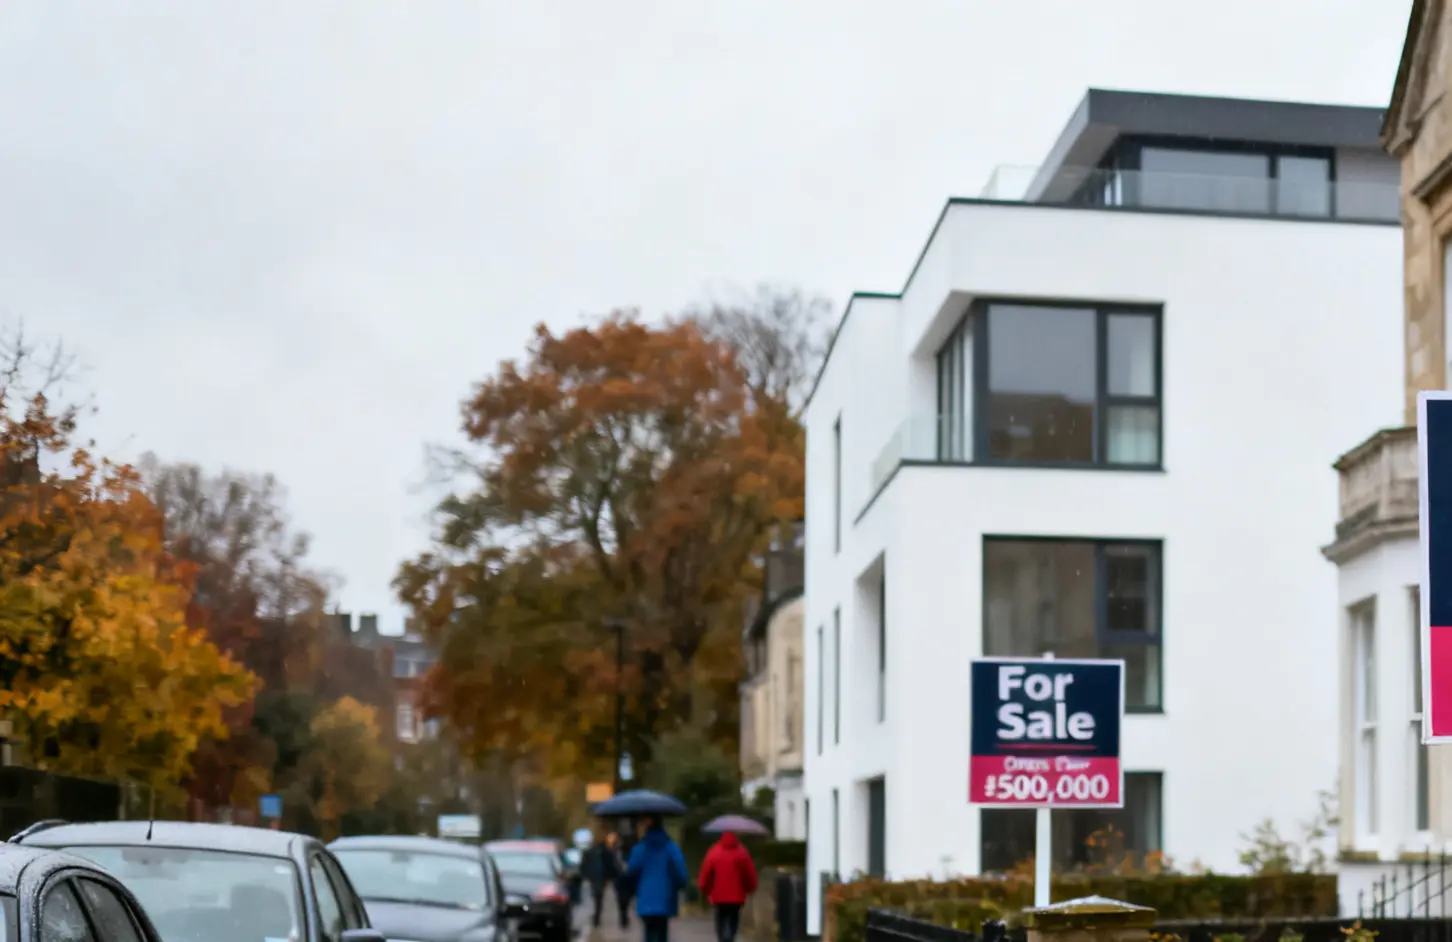
UK mortgage availability and demand declined in the third quarter of 2025, with lenders anticipating only a marginal improvement in the final three months of the year, according to Bank of England data.
The Bank of England’s Credit Conditions Survey revealed that the availability of secured credit to households decreased in the three months to the end of August. Lenders expect a slight increase over the next three months to the end of November.
Demand weakens across sectors
Demand for secured lending for house purchases fell in the third quarter, with lenders projecting a modest rise in the fourth quarter. Remortgage demand followed a similar pattern, declining in Q3 but expected to increase slightly in Q4, according to the Bank’s figures.
The decline in lending activity comes as affordability concerns continue to challenge buyers, particularly first-time purchasers. Recent analysis by Moneyfacts showed that fixed mortgage deals priced below 5% have virtually disappeared, with the number of such products collapsing by 99% in a single month.
Industry response
Nathan Emerson, CEO at Propertymark, said: “It is encouraging to see growing confidence around the potential demand for secured lending for house purchases and remortgaging in the months ahead. While the year has proved challenging for many consumers from an affordability perspective, improved access to finance could provide an important catalyst for greater confidence across the housing sector as we approach the end of the year and head into 2027.”
Ryan McGrath, Director of Second Charge Mortgages at Pepper Money, noted caution on both sides of the market. “The latest Bank of England Credit Conditions Survey shows caution on both sides of the market. Lenders reported that the availability of both secured and unsecured credit to households decreased in Q3, while demand for mortgages, for both house purchase and remortgaging, also fell.”
Market implications
The data suggests the UK housing market faces continued headwinds as buyers struggle with affordability challenges and lenders maintain cautious lending criteria. The modest upturn predicted for Q4 indicates any recovery in mortgage activity is likely to be gradual, with sustained access to competitively priced lending remaining a key factor for market momentum heading into 2026.